


EN
Eversource Energy (ES) Following Weaker Q3 Results And The Fair Value Debate
Eversource Energy Q3 results and what they might mean for investors
Eversource Energy (ES) has just released third quarter 2026 earnings, with both revenue and net income lower than the same period last year. This places profitability and investor expectations under closer scrutiny.
Eversource Energy’s share price has climbed 5.92% over the past month and now trades at $69.62, even though the latest quarter brought lower revenue and earnings. The three year total shareholder return of 42.22% highlights how sentiment has shifted over a longer stretch.
Compare how Eversource Energy stacks up against other regulated utilities by scanning our hand picked 42 power grid technology and infrastructure stocks for ideas that fit a similar profile.
Eversource Energy shares have climbed even as quarterly earnings softened, which leaves a straightforward question: Does the recent rebound still compensate you for the hit to profitability, or has the easier part of the risk-reward profile already played out, as the valuation now suggests?
Most Popular Narrative: 3% Undervalued
Eversource Energy last closed at $69.62, compared with a fair value of $72.00 in the analyst consensus Narrative on Simply Wall St, which builds that estimate from aggregated forecasts for revenue, earnings and risk.
Accelerated investment in grid modernization continues, supported by a 5 year US$26.5b capital plan through 2030 and potential upside from nearly US$1b of advanced metering infrastructure in Connecticut and new substations. These investments could improve reliability and operating efficiency and support net margins.
See why 23 investors see Eversource Energy as 3% undervalued.
Result: Fair Value of $72 (UNDERVALUED)
Still, the Eversource Energy story can change quickly if regulators continue to tighten storm cost recovery or if additional Revolution Wind charges affect reported earnings again.
Find out about the key risks to this Eversource Energy narrative.
Another View: Cash Flows Paint A Different Picture
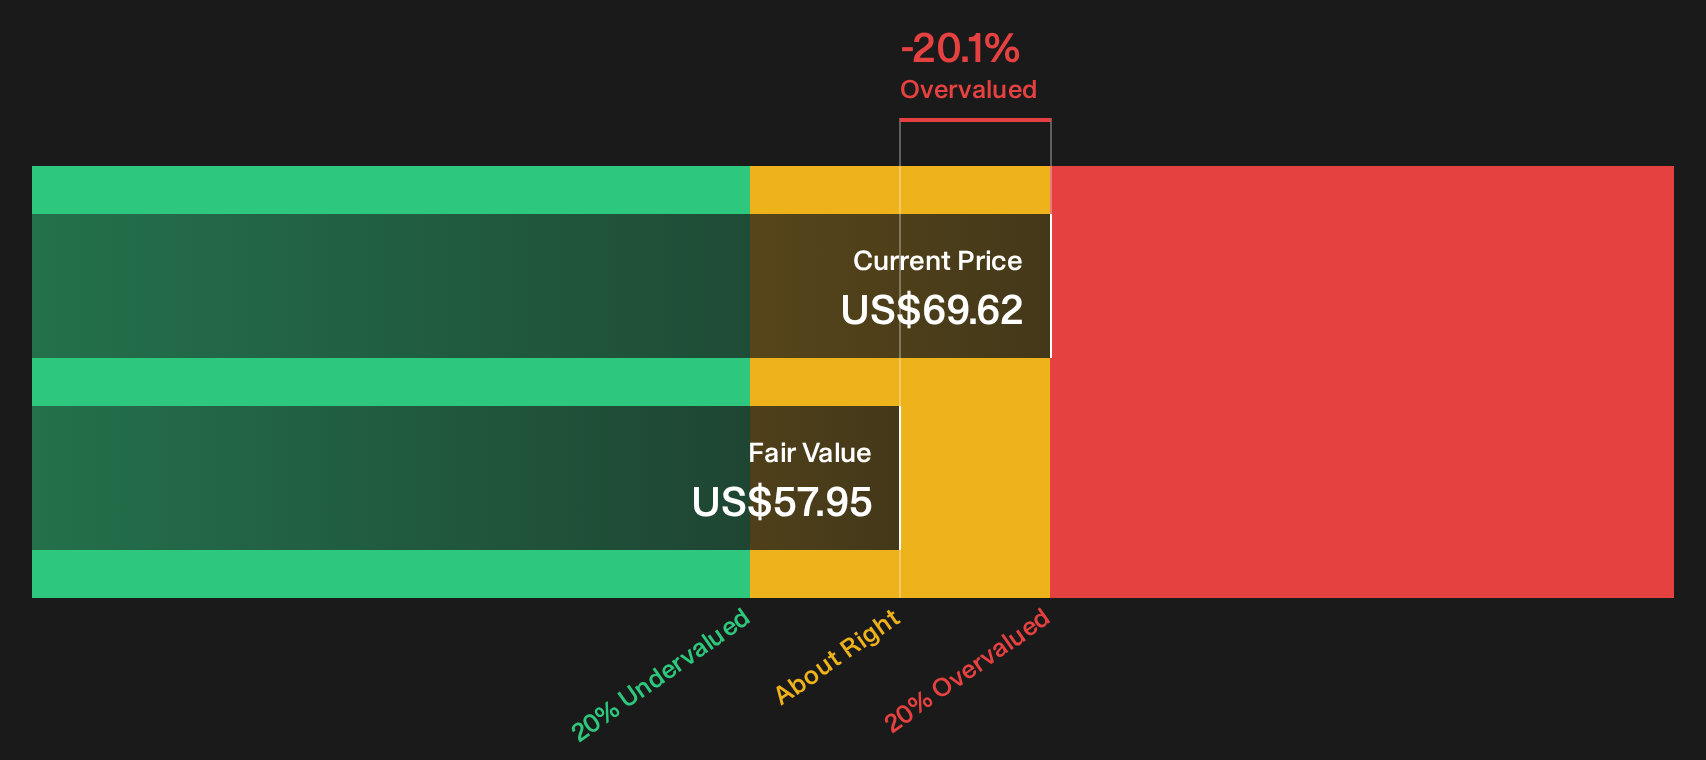
The first take on Eversource Energy leans on analyst targets and earnings based fair value of $72.00, which suggests the stock is 3.3% below that mark at $69.62. Our DCF model tells a different story. It points to a value of $57.95, which implies the share price is running ahead of its discounted cash flows rather than behind them.
That gap matters. It means investors who focus on P/E and analyst targets see some upside, while anyone anchored on cash generation sees limited room for error. The question is simple. Which lens do you trust more when future cash flows are doing less of the heavy lifting than headline earnings imply?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eversource Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Eversource Energy so far. If the push and pull between risks and potential rewards has you undecided, take a closer look at the details and stress test your own thesis with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Eversource Energy?
Do not stop with Eversource Energy. Cast a wider net using focused screeners that surface clear, data backed ideas before the crowd catches on.
- Target resilience first and narrow in on 30 resilient stocks with low risk scores that aim to keep portfolio swings in check while still leaving room for upside.
- Hunt for mispriced opportunities and filter for 33 high quality undervalued stocks where fundamentals and share prices tell very different stories.
- Strengthen your core holdings by scanning the list of solid balance sheet and fundamentals (25 results) so you are not relying on fragile financial footing when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com