


EN
How Westermann School Deal At Pearson (LSE:PSON) Has Changed Its Investment Story
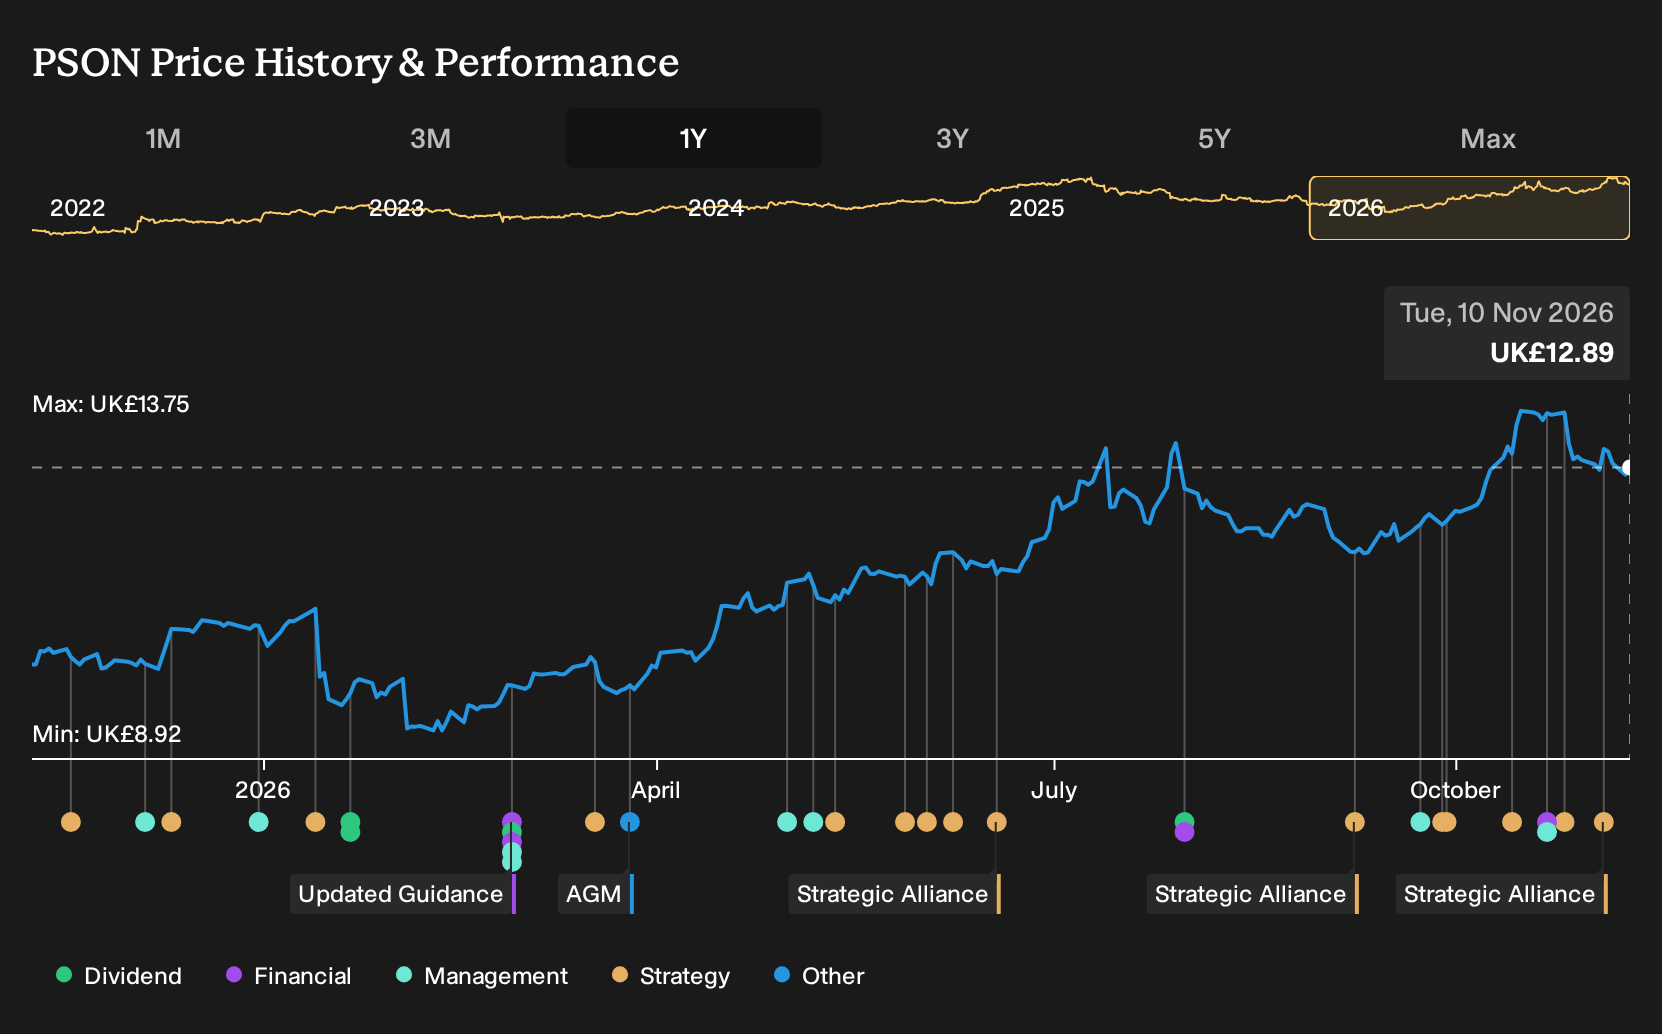
- Pearson and Westermann recently agreed a collaboration that will bring PTE Academic and Versant English assessments, plus AI-enabled prep tools, to thousands of German schools from January 2027.
- The alliance integrates Pearson’s English exams directly into Westermann’s long-established K-12 relationships in Germany, embedding assessment, preparation content and credentials into day-to-day learning flows.
- We will now look at how Pearson’s Westermann English testing rollout could influence the investment narrative built around assessment scale.
Scan beyond Pearson to other education and AI-enabled learning stocks by reviewing the hand picked 42 profitable AI stocks that aren't just burning cash that are already turning digital tools into real earnings power.
Pearson Investment Narrative Recap
To own Pearson, you need to be comfortable with a slow and steady education group that leans heavily on assessments, digital delivery and skills credentials. The analyst consensus Narrative on Simply Wall St hinges on mid single digit revenue growth and gradual margin improvement. The Westermann deal fits that story, although on its own it looks more like a supportive proof point than a major near term catalyst.
The bigger swing factor still sits in execution of the 2027 reorganisation and whether Enterprise Learning & Skills and Virtual Learning offset pressure in English testing and parts of Higher Education. FX volatility and any cooling in assessment volumes remain the clearest operational risks.
The Westermann agreement lines up neatly with Pearson’s push into AI enabled tools and large scale testing infrastructure. It complements newer certification programs such as the Google Cloud and Anthropic initiatives, which already show that Pearson can run large volumes of secure assessments for specialist skills.
For you as an investor, the thread running through these moves is operational. Management is tying more learning journeys directly to its exams and credentials, across both academic English and workforce skills. That deepens integration with institutions but also raises the bar on execution, test reliability and content localisation across multiple markets.
Pearson's current analyst script points to revenues of £4.2b and earnings of £458.4m by 2029, built on a 4.9% yearly revenue growth assumption and an earnings step up of about £139m from £319.0m today.
Uncover why Pearson's fair value is essentially in line with its current price.
Exploring Other Perspectives
The key alternate worry is that Pearson will not fully convert AI tools and big partnerships like Westermann into dependable English testing volumes. The most bearish analysts were already working off roughly £4.2b of revenue and £468.1m of earnings by 2029, with a much lower P/E. That more cautious script could shift again after this news. Consider both narratives carefully before deciding what makes sense for you.
Explore 2 other Pearson fair value estimates, including one that suggests it could be worth just £12.88.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Pearson research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Pearson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pearson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pearson?
After weighing Pearson’s story, it can help to compare it with other opportunities that match your risk tolerance, income needs and quality checklist. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If you prefer stability and resilience in tougher markets, focus on companies screened for stronger profiles through the 4 resilient stocks with low risk scores.
- If you want quality at a reasonable entry point, look across the 16 high quality undervalued stocks that combine fundamentals with pricing that may warrant a closer look.
- If you are looking for sturdier balance sheets to anchor a portfolio, filter for companies on the list of solid balance sheet and fundamentals (9 results) and see which ones match your checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com