


EN
Caught Out By Nel's Fall? Here's What The Bears Saw
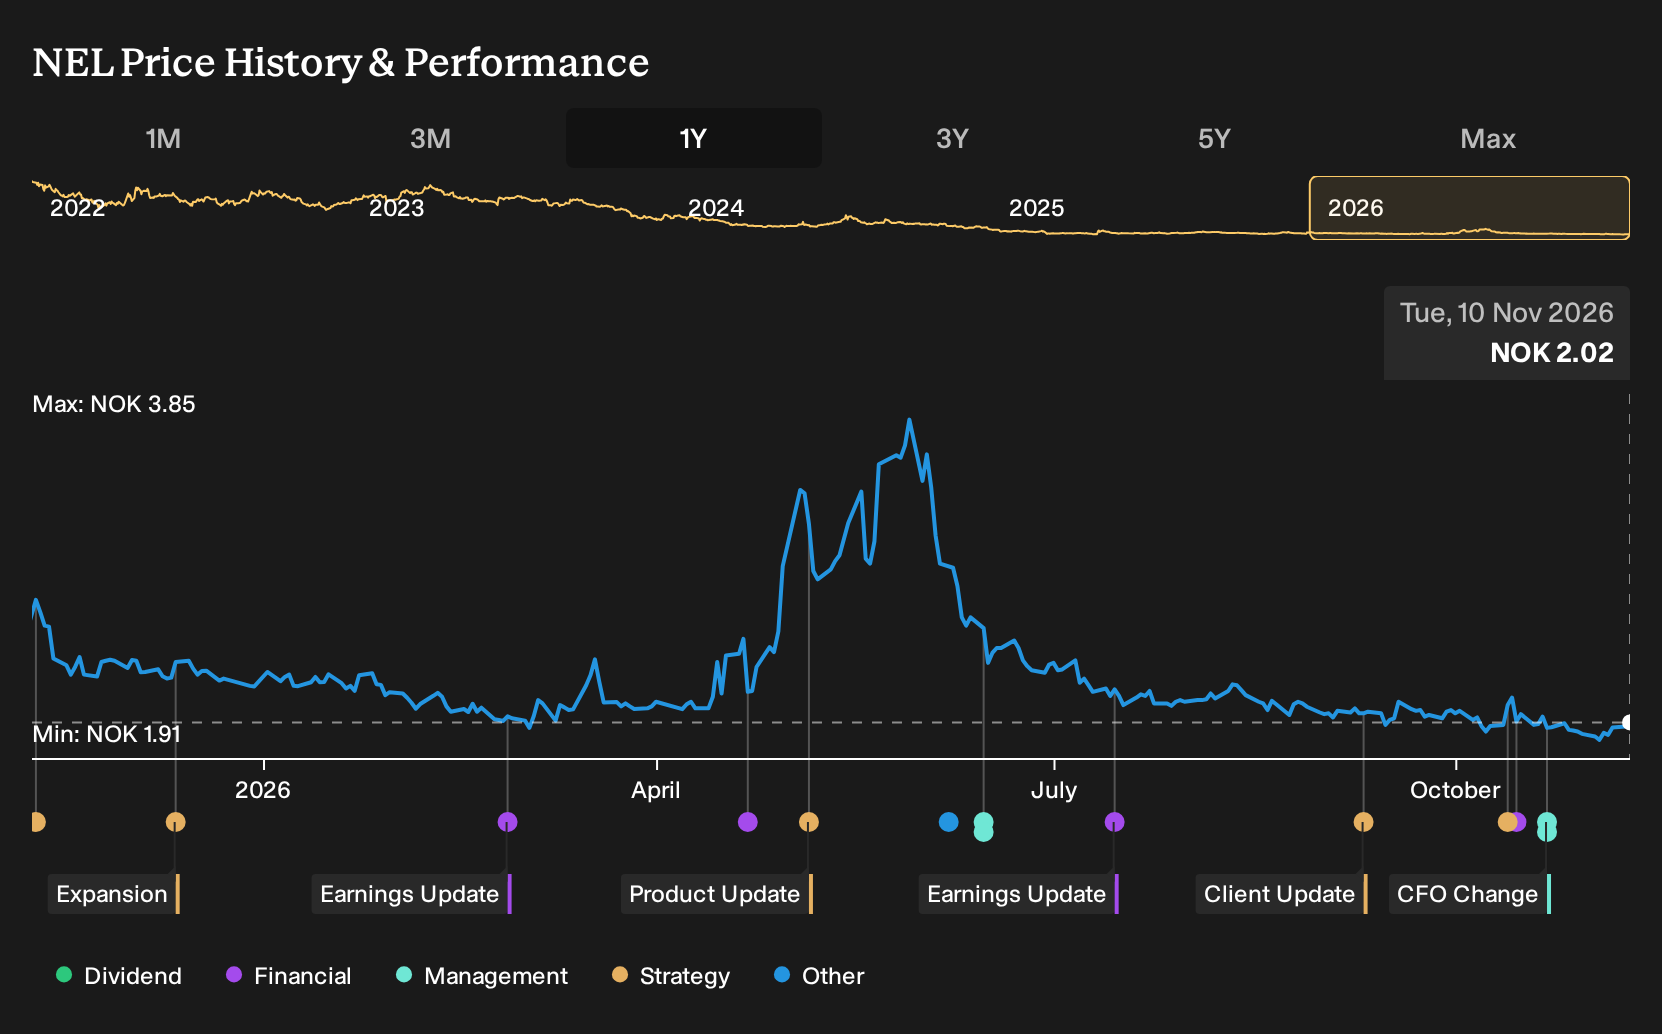
NEL ASA has packed a lot into the past year, from a new Q3 2026 report showing weaker revenue and a deeper loss to the board naming incoming CEO Morten Holum after an interim handover to the CFO. Investors who held Nel over the past year are down 24.9%, including dividends. If you had committed fresh capital on 10 November 2025, how much of that setback ties back to what was already on record about delayed orders and ambitious electrolyzer plans?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Nel has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Argument You Would Have Been Weighing Up On Nel
The shares cost NOK2.76 at the start of the period, and Nel sat between two very different stories about how its electrolyzer push might play out.
On the bullish side, the Fair Value was NOK4.07, built on an assumption of 29.1% annual revenue growth and profit margins eventually reaching 5.2%, which would support a future P/E of 92.4x.
The bearish view put Fair Value at NOK1.2, with slower 10.6% revenue growth and the risk that delayed customer decisions and project cancellations would keep earnings unpredictable even if margins reached 5.2% and a future P/E of 43.4x.
What The Results Changed For The Nel ASA Thesis
The Q3 2026 report did the heavy lifting. Nel ASA’s revenue moved from NOK303.373m in Q3 2025 to NOK111.652m, while the loss widened from NOK84.701m to NOK140.68m and net margin dropped from 27.9% negative to 126.0% negative. That outcome challenged the bullish path to healthier earnings and gave more weight to the cautious case about profitability risk.
The lesson is simple. When a story leans on future margin repair, track the reported net margin and absolute loss each quarter and see whether they are actually moving toward the level implied in the original thesis.
What You Would Be Paying For In Nel Today
Nel now trades at NOK2.02 after a 24.9% loss over the past year, and the bullish analyst Narrative on Simply Wall St sets its Fair Value above that level. The present focus is on whether PEM driven orders and a leaner cost base can offset pressure in the alkaline side.
For the fall to look like an opportunity rather than a warning, a buyer today would need to believe PEM orders, backlog quality and Herøya utilization can translate into sustained, higher margin volumes without cash burn spiralling.
"The sharp rebound in order intake to NOK 85m in Q1 2026, NOK 230m in Q2 and NOK 253m in Q3, with backlog reaching NOK 1.314bn and now largely tied to PEM, points to Nel’s containerized PEM business becoming a volume engine in smaller 1 to 50 MW projects."
One Narrative disagrees with today's price. → See where this Narrative says Nel should trade
Looking Beyond Nel’s Electrolyzers
Nel focuses attention on energy hardware and project timing, but something broader matters.
Big infrastructure efforts often depend on others to build the unseen backbone underneath.
Space operators face a similar challenge, because bold satellite plans require dependable launches.
One specialist tackles this by linking launch hardware with the spacecraft riding on top.
If that approach works, more value could sit in the quiet backbone than in the headline missions investors usually watch.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 66% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com