


EN
How Quarterly Loss Will Impact Ball (BALL) Stock
- Ball Corporation reported third quarter 2026 sales of US$4,188 million, up from US$3,379 million a year earlier, but moved from net income of US$321 million to a net loss of US$94 million, with basic and diluted loss per share of US$0.36 from continuing operations.
- The nine month figures show higher revenue of US$11,788 million compared with US$9,814 million in the prior period, while net income declined to US$332 million and earnings per share from continuing operations fell to US$1.25, indicating pressure on profitability alongside Ball's higher revenue base.
- The next step is to consider how Ball's investment narrative may change in light of higher sales occurring alongside a third quarter net loss.
Ball Investment Narrative Recap
To own Ball, you need to believe the long term shift toward recyclable aluminum packaging and contracted capacity can support a healthier earnings profile than the latest quarter suggests. The analyst consensus Narrative on Simply Wall St leans on productivity gains and tighter cost control. The third quarter loss challenges that in the near term, since profit margins and free cash flow have already been under pressure from input costs and operational inefficiencies.
The key short term catalyst remains execution on the Ball Business System and new capacity ramp up without further margin strain. The biggest risk right now is that cost volatility and start up drag, including Millersburg, keep squeezing earnings longer than expected, especially with customer concentration in South America still a concern.
The recent decision to affirm a US$0.20 per share cash dividend for December matters in this context. Ball is reporting a quarterly loss, lower year to date earnings per share and weaker net profit margins compared with last year, yet still committing cash to shareholders. That points investors back to balance sheet strength and cash generation as core watchpoints.
For readers tracking catalysts, that dividend sits alongside plans to return about US$800 million to investors in 2026 and target net debt to EBITDA of roughly 2.7x in the analyst consensus Narrative on Simply Wall St. The combination keeps attention on whether operating cash flow can comfortably cover both debt and capital returns while input costs, new plant ramp up and customer exposure risks remain in play.
On these analyst assumptions, Ball's narrative projects US$16.1b revenue and US$1.3b earnings by 2029, with revenue rising at 3.9% per year and profit increasing by about US$355m from US$945.0m today.
Uncover why Ball's fair value indicates a 9% potential upside to its current price that may not last much longer.
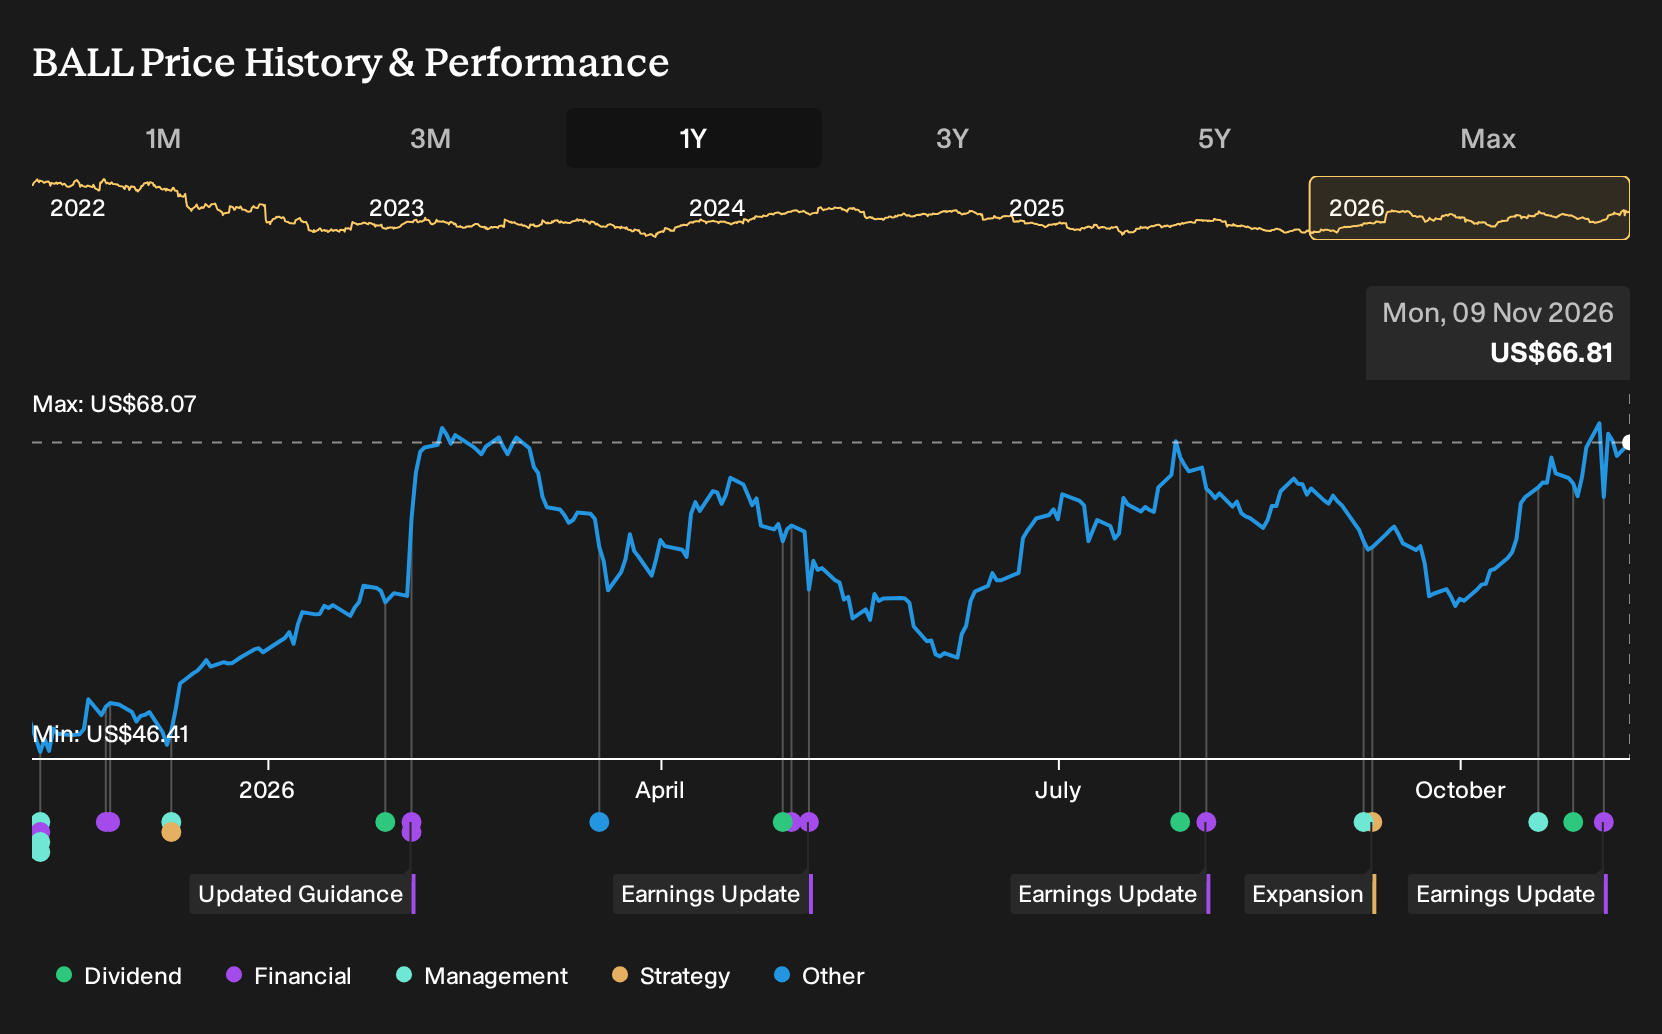
Exploring Other Perspectives
One bullish twist on Ball focuses on the productivity program as a potential upside surprise. The most optimistic analysts were pencilling in roughly 5.9% annual revenue growth and earnings of about US$1.3b by 2029 before this quarterly loss. You can use those stronger assumptions as a reference point and explore how views may shift after these results.
Explore 4 other Ball fair value estimates, including one that suggests as much as 83% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ball research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ball. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ball's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ball?
If Ball's latest update has sharpened your process, use that momentum to scan a broader set of companies and pressure test where risk, quality and price line up more cleanly for your portfolio.
- If you want to focus on stronger balance sheets and steadier finances, run your eye over our list of solid balance sheet and fundamentals (25 results) that filters for companies with robust fundamentals.
- For investors hunting for quality at a reasonable entry point, sort through the 33 high quality undervalued stocks and see which businesses currently trade below their estimated worth.
- If income is your priority, scan the 6 dividend fortresses to find higher yielding stocks that pair payout potential with resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com