


EN
How Half Year Loss Will Impact Vodafone Stock Investors
- Vodafone Group reported half year results for the period to 30 September 2026 with sales of €21,853 million and a net loss of €4,789 million, alongside basic and diluted losses per share from continuing operations of €0.2075.
- The Board lifted the interim dividend to 2.306 € cents per share despite the swing from €829 million net income a year earlier to a multi billion euro loss. This highlights a decision to maintain cash returns while reported earnings move in the opposite direction.
- We will look at how Vodafone Group's investment narrative lines up with this sharp move into loss while slightly raising its dividend.
Scan how Vodafone Group’s sharp swing into loss and slightly higher dividend compares to other large telecoms by weighing it against list of solid balance sheet and fundamentals (9 results).
Vodafone Group Investment Narrative Recap
To own Vodafone Group today, you need to believe that heavy restructuring, network investment and portfolio changes can translate into steadier cash generation over time. The analyst consensus Narrative on Simply Wall St leans on U.K. VodafoneThree integration, German operational repair and growth from Africa and Turkey. This half year loss of €4,789m makes that earnings path look bumpier but does not automatically break it.
The short term swing factor remains execution on integration and cost savings, especially in the U.K. and Germany, while keeping churn in check. The biggest risk is that operational setbacks and high debt, together with losses, squeeze flexibility just as 5G and network projects need sustained capital.
The interim dividend increase to 2.306 € cents per share is the announcement that ties closest to this earnings release. Management is holding the payout line even as reported profit moved from €829m income a year ago to a multi billion euro loss. That signals a preference for continuity of cash returns over aligning dividends strictly with near term earnings volatility.
For you as a shareholder, the key question is whether free cash flow and the balance sheet can comfortably support both restructuring and dividends at this level. Dividend coverage was already flagged as weak, with the payout not well covered by earnings. If operational issues in Germany, integration costs or 5G spending run hotter than planned, the dividend could limit room to address those pressures quickly.
What Analysts Are Building Into The Vodafone Group Story
Vodafone Group's narrative projects €47.3 billion revenue and €3.3 billion earnings by 2029, based on analyst assumptions. According to these projections, this would reflect 5.3% yearly revenue growth and about a €3.6 billion earnings increase from current earnings of a €289.0 million loss.
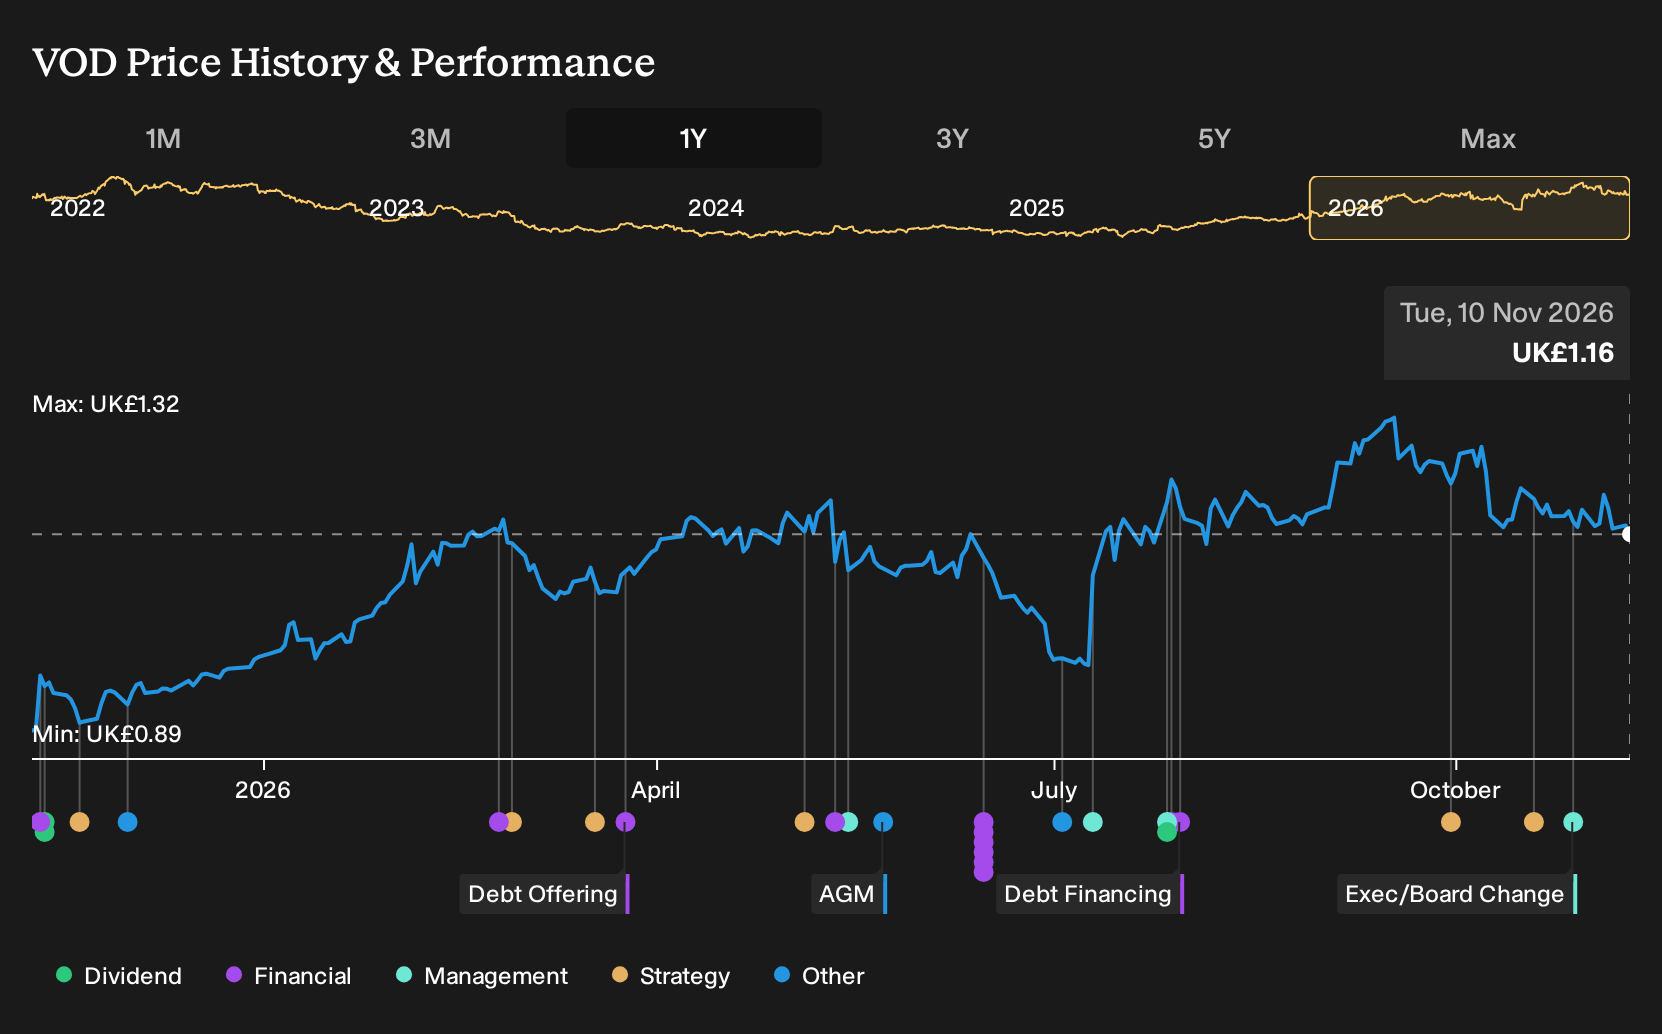
Uncover how Vodafone Group's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Vodafone Group’s German pressure as the key risk. The most cautious analysts were only pencilling in about €47.0b of revenue and €1.6b of earnings by 2029 before this half year loss and dividend lift. Their story is far more pessimistic, so use this earnings shock to compare several narratives side by side.
Explore 4 other Vodafone Group fair value estimates, including one that suggests it could be worth just £1.22.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vodafone Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vodafone Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vodafone Group's overall financial health at a glance.
Looking for more Vodafone Group style investment ideas?
If this Vodafone Group update has sharpened your thinking and you want to pressure test that view against other potential holdings, the Simply Wall St Screener can help you filter the wider market down to a focused shortlist that fits your own risk and income profile.
- If capital preservation sits high on your list, start by scanning a group of companies that score well on financial resilience through the 4 resilient stocks with low risk scores.
- Income focused investors who want yield with a quality filter can review a curated set of stocks described as 6 dividend fortresses.
- For those hunting for future compounders before they are widely followed, the screener highlighting 5 high quality undiscovered gems can surface ideas to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com