


EN
CFO Succession Might Change The Case For Investing In Convatec Group (LSE:CTEC)
- Convatec Group has confirmed a planned finance leadership transition, with Jill McConnell appointed CFO Designate from January 1, 2027, and succeeding current CFO Fiona Ryder on March 1, 2027. Ryder will support the handover through the February 2027 full year results.
- McConnell brings over 25 years of healthcare finance leadership, including helping establish Fortrea as a standalone US listed business. This gives Convatec Group deeper experience in capital allocation, business transformation and large scale finance operations across US and European markets.
- We will now look at how Convatec Group’s investment narrative could be influenced by McConnell’s appointment as incoming Chief Financial Officer.
Convatec Group Investment Narrative Recap
To own Convatec Group, you need to be comfortable with a healthcare manufacturer that is investing heavily in new products, capacity and margin improvement while still working through some operational scars. The analyst consensus narrative on Simply Wall St rests on continued execution in chronic care, Infusion Care expansion and steady improvement in profitability from today’s 5% net margin.
In that context, the incoming CFO news looks more like continuity than a short term swing factor. In the near term, the bigger catalyst is how quickly Infusion Care investments of about US$90m in 2026 translate into usable capacity. The biggest immediate risk remains regulatory remediation and InnovaMatrix staying weak after the large non cash impairment.
The executive change intersects most closely with Convatec Group’s push to improve margins and cash conversion. Jill McConnell will eventually oversee Finance, Corporate Strategy & Development, Convatec Business Services and Investor Relations, all areas linked directly to the margin expansion and capital allocation story that analysts are watching.
A finance leader with experience separating Fortrea from Labcorp and running large US healthcare operations may matter as Convatec Group works through high debt, dividend cover pressure and large one off items in recent results. For investors, the operational question is whether this leadership shift helps the business keep executing on R&D, cost programmes and Infusion Care remediation without losing focus on regulatory and reimbursement risks.
Convatec Group’s current analyst storyline assumes revenues reach US$3.0b and earnings reach US$455.3m by 2029, based on 6.5% yearly revenue growth and an earnings increase of about US$331m from US$124.0m today.
Uncover why Convatec Group's fair value indicates a 21% potential upside to its current price that may not last much longer.
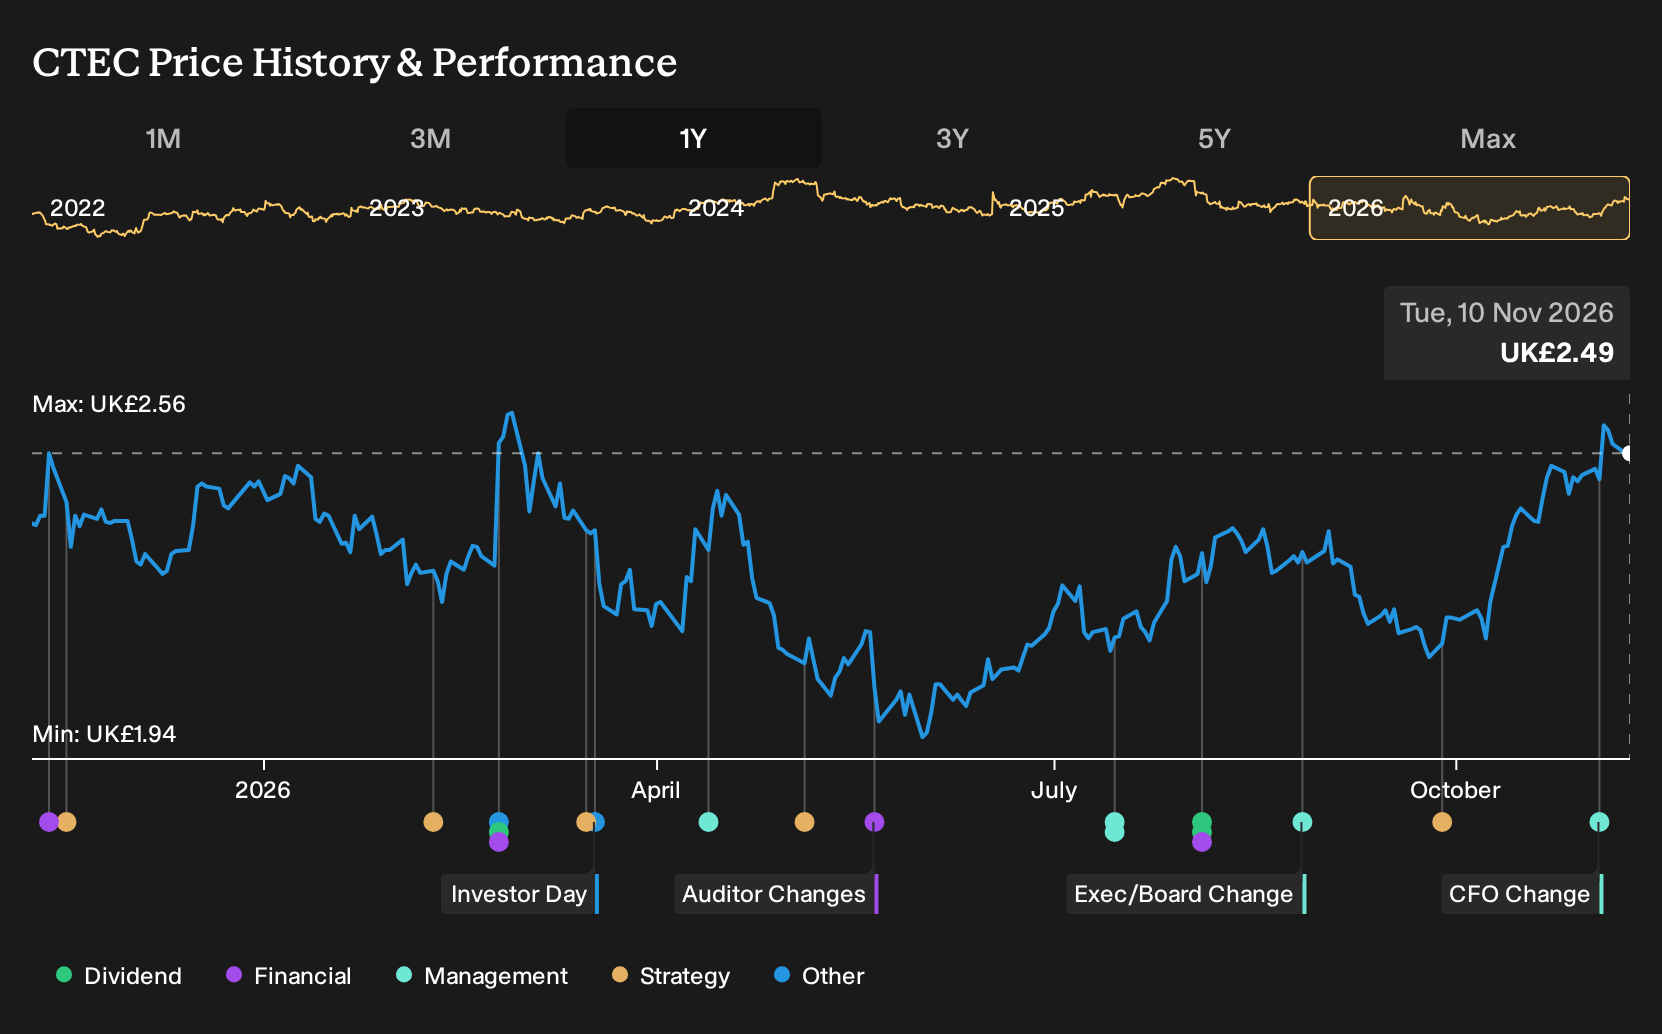
Exploring Other Perspectives
Fair value estimates for Convatec Group from 2 Simply Wall St Community members cluster between about US$3.00 and US$4.26 per share, which already shows how far opinions can stretch. Those views do not yet factor in the incoming CFO or Infusion Care risks, so treat them as a starting point and compare several alternative takes.
Explore another Convatec Group fair value estimate, including one that suggests potential upside of up to 71% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Convatec Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Convatec Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Convatec Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Convatec Group?
Once you have formed a view on Convatec Group, it can help to widen the lens and compare it with other listed businesses that match your risk level, income needs or value focus. The Simply Wall St Screener lets you do exactly that by filtering the market down to a short list that fits the type of portfolio you want to build.
- If capital preservation and smoother returns matter most to you, start with a curated group of companies that our models classify as relatively resilient by checking out the 4 resilient stocks with low risk scores.
- If you are hunting for companies that appear priced below what their fundamentals suggest, review a selection of potential value opportunities through the 16 high quality undervalued stocks.
- If consistent shareholder payouts are a priority, focus on businesses combining higher yields with stability by scanning the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com