


EN
Could Intertek Split Plans Alter The Investment Case For Intertek Group (LSE:ITRK)?
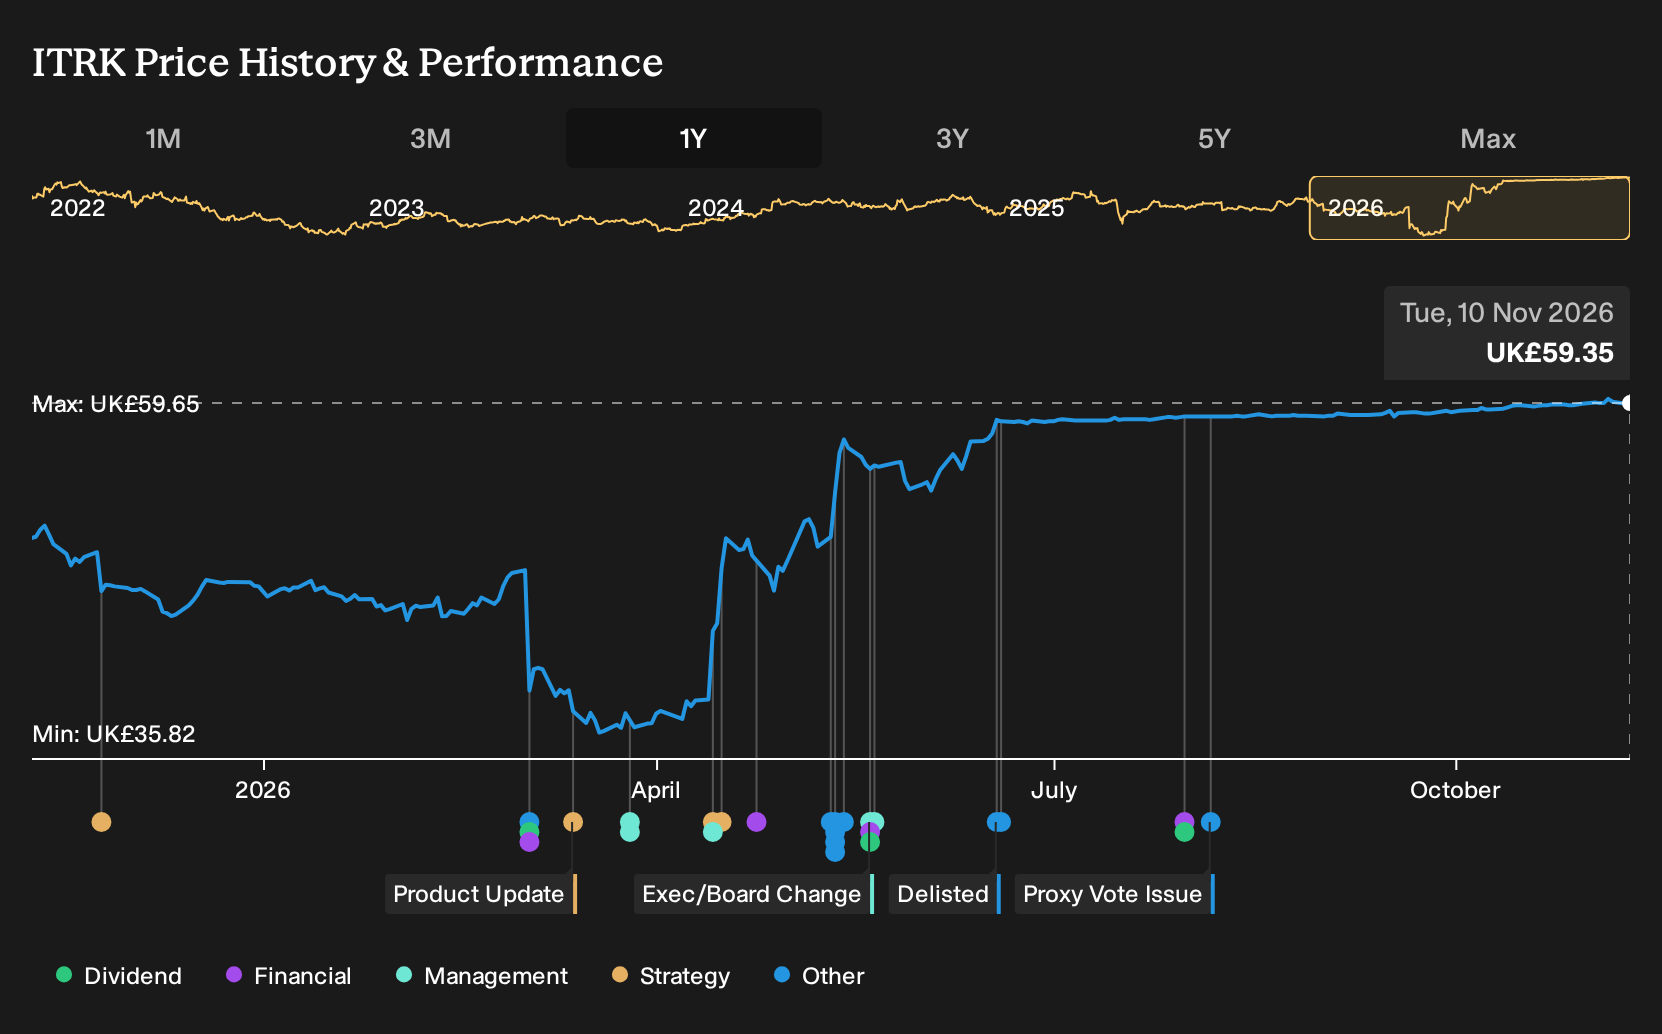
- Intertek Group recently reported 6.4% organic revenue growth for Q3 2026 and kept its free cash flow guidance unchanged, while outlining plans to separate its Testing and Assurance and Energy and Infrastructure activities into two specialist businesses by mid 2027.
- The combination of resilient organic growth, maintained cash flow guidance and a planned split into focused units highlights how execution on Intertek Group’s AAA plan could reshape capital allocation, cost structures and operational accountability across its assurance and energy facing activities.
- We will now look at how Intertek Group’s planned business separation could influence the existing investment narrative around cash generation and strategic focus.
Scan beyond Intertek Group and find other cash generative operators with focused business models using our curated list of 16 high quality undervalued stocks.
Intertek Group Investment Narrative Recap
To own Intertek Group, you need to be comfortable with a quality assurance business that relies on steady client demand, disciplined cost control and consistent cash generation. The recent 6.4% organic growth and unchanged free cash flow guidance support that cash story and do not appear to materially change the near term thesis around stable operations.
The biggest short term swing factor is how cleanly Intertek Group executes on its AAA plan while preparing for the Testing and Assurance and Energy and Infrastructure split. Separation complexity, overhead reallocation and continued weakness in Transportation Technology remain key risks that could pressure margins if they prove tougher than management currently outlines.
The analyst consensus narrative on Simply Wall St highlights the planned separation of Testing and Assurance and Energy and Infrastructure into two ATIC businesses by mid 2027 as a major operational catalyst. That decision sits alongside the recent growth update and aims to give each activity clearer decision making, capital discipline and accountability for cash generation.
For you as a shareholder, the practical question is whether Intertek Group can manage the extra central costs, any duplicated functions and carve out work without eroding profitability. Execution on this split, together with continued integration of recent bolt on deals, will likely shape how much of the forecast earnings growth and free cash flow actually shows up.
Intertek Group's current analyst narrative points to revenues of £4.1b and earnings of £464.4m by 2029, based on 5.0% yearly revenue growth and an earnings increase of about £144.3m from £320.1m today.
Uncover why Intertek Group's fair value indicates that Intertek Group is broadly in line with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly £59 to £73 per share, which already gives you a wide bracket for Intertek Group. Set that against fresh interest from several disclosed institutional holders, including positions above 5%, and you can see how opinions diverge. Use these contrasting views to pressure test your own thesis.
Explore another Intertek Group fair value estimate, including one that suggests as much as 23% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Intertek Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Intertek Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intertek Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Intertek Group?
Once you have a view on Intertek Group, it can help to cross check that thinking against other opportunities using the Simply Wall St Screener.
- If you care most about resilient balance sheets and steady fundamentals, scan our curated list of solid balance sheet and fundamentals (9 results) and compare how those businesses stack up on financial strength.
- For investors who want a margin of safety built into the share price, test your criteria against 16 high quality undervalued stocks and see which companies fit your preferred combination of quality and price.
- If you are hunting for under the radar operators with room to grow, take a look through 5 high quality undiscovered gems and see which lesser known stocks deserve a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com