


EN
Cheniere Energy Partners (CQP) Lifts 2026 Distribution Guidance, Is It Still A Bargain?
Cheniere Energy Partners (CQP) has drawn fresh attention after reporting higher third quarter and nine month revenue and net income year over year, together with tighter and higher full year 2026 distribution guidance.
The earnings beat and tighter 2026 distribution guidance arrived after a choppy few months for Cheniere Energy Partners, with the 90 day share price return down 11.84% and the 30 day move lower by 7.62%, even though the year to date share price return is up 8.70% and the 1 year total shareholder return sits at 19.85% on the back of sizeable distributions. With the unit price at about $58.70 after a 1 day share price gain of 2.34% and a 7 day share price decline of 9.01%, recent selling pressure appears to be fading. The 3 year and 5 year total shareholder returns of 22.15% and 93.96% underscore the longer term story for income focused holders.
Scan income-focused opportunities beyond Cheniere Energy Partners with a curated 6 dividend fortresses that echoes this mix of hefty payouts and market volatility.
After that mix of stronger reported earnings, firmer 2026 distribution guidance and a pullback from recent highs, does Cheniere Energy Partners still offer a risk reward skew that leans toward new buyers, or favor existing holders taking chips off the table?
Preferred P/E of 10.3x for Cheniere Energy Partners: Is it justified?
On valuation, Cheniere Energy Partners trades on a P/E of 10.3x, which screens as inexpensive relative to both peers and the wider US Oil and Gas industry given the last close at $58.70.
The P/E ratio compares the current unit price to earnings per unit and provides a quick indication of how much investors are paying for each dollar of profit. For a business focused on LNG infrastructure with long term contracts and sizeable distributions, earnings power often matters more to holders than rapid top line expansion.
Cheniere Energy Partners is assessed as good value on several fronts. The P/E of 10.3x sits below the US Oil and Gas industry average of 10.5x and well below the peer average of 17.2x. This suggests the market is assigning a lower earnings multiple than it does to comparable businesses. Relative to an estimated fair P/E of 14.5x, the current level is also materially cheaper and indicates potential for the valuation to move closer to that fair ratio if sentiment and fundamentals stay aligned.
Explore the SWS fair ratio for Cheniere Energy Partners.
Result: Price-to-earnings of 10.3x (UNDERVALUED)
Still, concentration in a single LNG terminal and a recent annual net income contraction of 5.0% could pressure Cheniere Energy Partners if contract or volume assumptions are tested.
Find out about the key risks to this Cheniere Energy Partners narrative.
Another View on Cheniere Energy Partners Using Our DCF Model
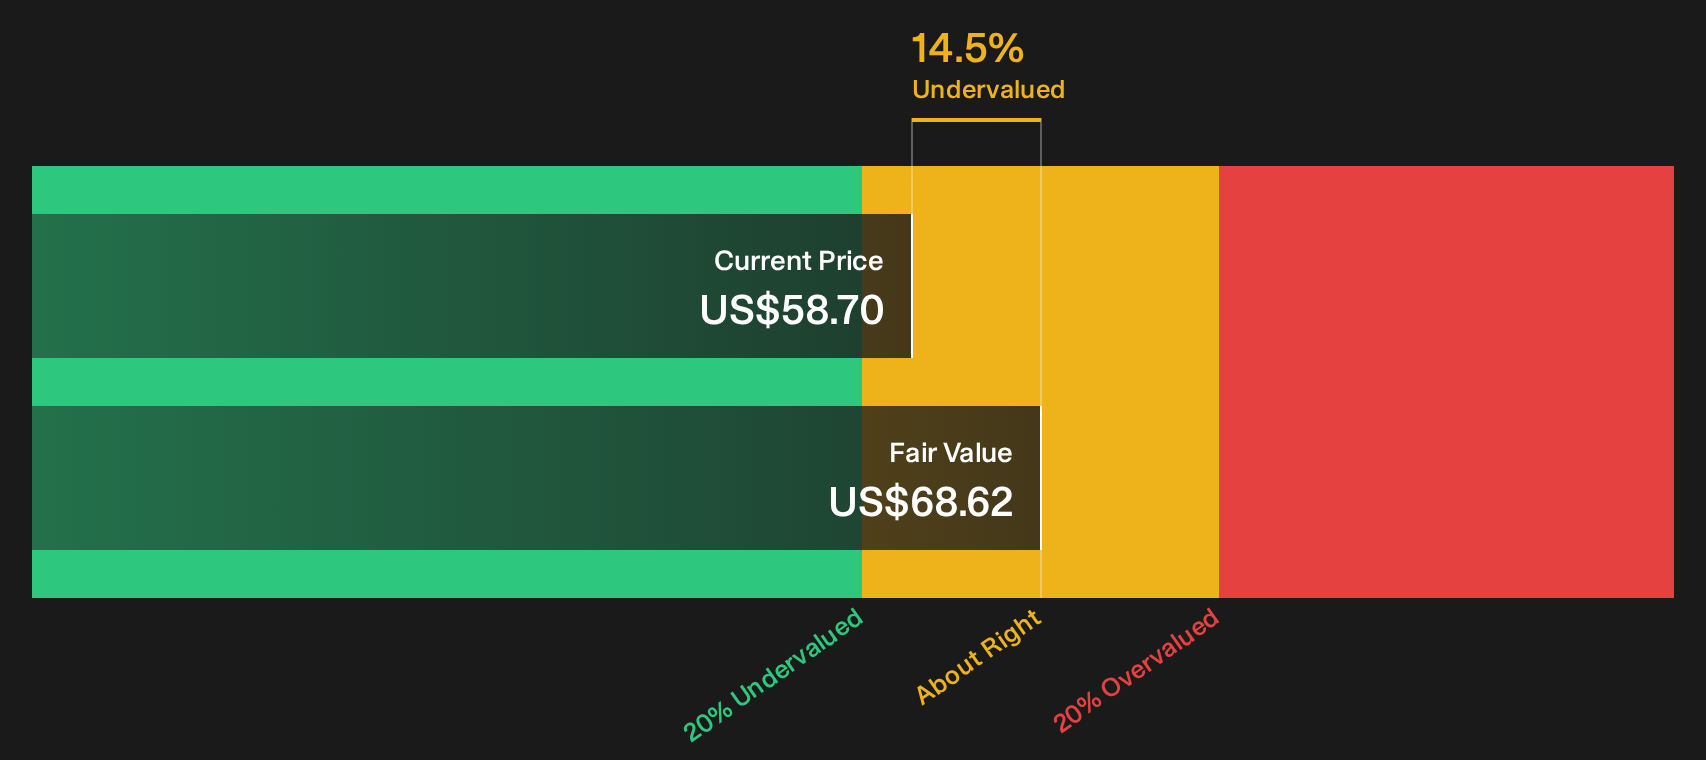
The P/E points to value, and the SWS DCF model presents a similar but distinct perspective. At $58.70, Cheniere Energy Partners trades about 14.5% below an estimated future cash flow value of $68.62. This raises a practical question: Is this discount enough compensation for slower forecast revenue growth and expected earnings decline?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cheniere Energy Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Cheniere Energy Partners mixed between attractive valuation signals and flagged issues, do not just take this snapshot at face value. Review the underlying metrics, pressure test the assumptions, and then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cheniere Energy Partners?
Do not stop with Cheniere Energy Partners. Use the broader data set to look for potential setups where valuation, balance sheet strength, and future potential line up on your terms.
- Target quality at a discount by scanning a curated pool of 33 high quality undervalued stocks that combine supportive fundamentals with appealing price tags.
- Consider reducing portfolio stress by focusing on 30 resilient stocks with low risk scores that aim to keep volatility and financial red flags in check.
- Stay early to the story by shortlisting 19 high quality undiscovered gems that pair solid metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com