


EN
Ivanhoe Mines (TSX:IVN) Cuts Copper Guidance, Is It Still A Bargain?
Guidance change and earnings put Ivanhoe Mines in focus
Ivanhoe Mines (TSX:IVN) stepped into the spotlight after updating its Kamoa-Kakula copper production outlook and reporting third quarter 2026 results that showed higher sales and net income compared with a year earlier.
For investors watching Ivanhoe Mines, the story in the share price has been far rougher than the headline earnings would suggest. The stock is down 26.03% over the past month and 27.53% over 90 days, contributing to a 46.51% year to date share price decline and a 35.00% drop in total shareholder return over the past year. This hints that the updated Kamoa-Kakula production guidance and other recent project updates are being weighed more heavily than the latest quarter’s stronger sales and profit figures.
Spot fresh angles on copper and materials exposure by comparing Ivanhoe Mines with our curated 16 top copper producer stocks.Ivanhoe Mines looks like a serious copper producer in the making, yet the share price slide tells a very different story. Is this still a quality asset mix at a fair tag today, or not?
Most Popular Narrative: 39% Undervalued
Ivanhoe Mines last closed at CA$8.58, while the analyst consensus Narrative on Simply Wall St anchors fair value at CA$14.06 based on discounted future cash flows using an 8.23% discount rate. That gap frames a bullish long term story that leans heavily on copper growth, new projects and cost improvements.
Completion and ramp-up of the Kamoa-Kakula smelter (targeted for September) and the associated drop in logistics costs are expected to meaningfully reduce unit costs, directly boosting future operating margins and cash flow.
Construction progress at the Platreef project, with commercial PGM production expected to begin in Q4 and further scale-up with Shaft #3 and Phase 2, will diversify revenue streams and improve earnings resilience at industry-leading unit costs.
See why 32 investors see Ivanhoe Mines as 39% undervalued.
Result: Fair Value of CA$14.06 (UNDERVALUED)
Still, the narrative around Ivanhoe Mines could change quickly if further operational setbacks at Kamoa-Kakula or higher than expected capex strain cash flows and delay project delivery.
Find out about the key risks to this Ivanhoe Mines narrative.
Another view on Ivanhoe Mines valuation
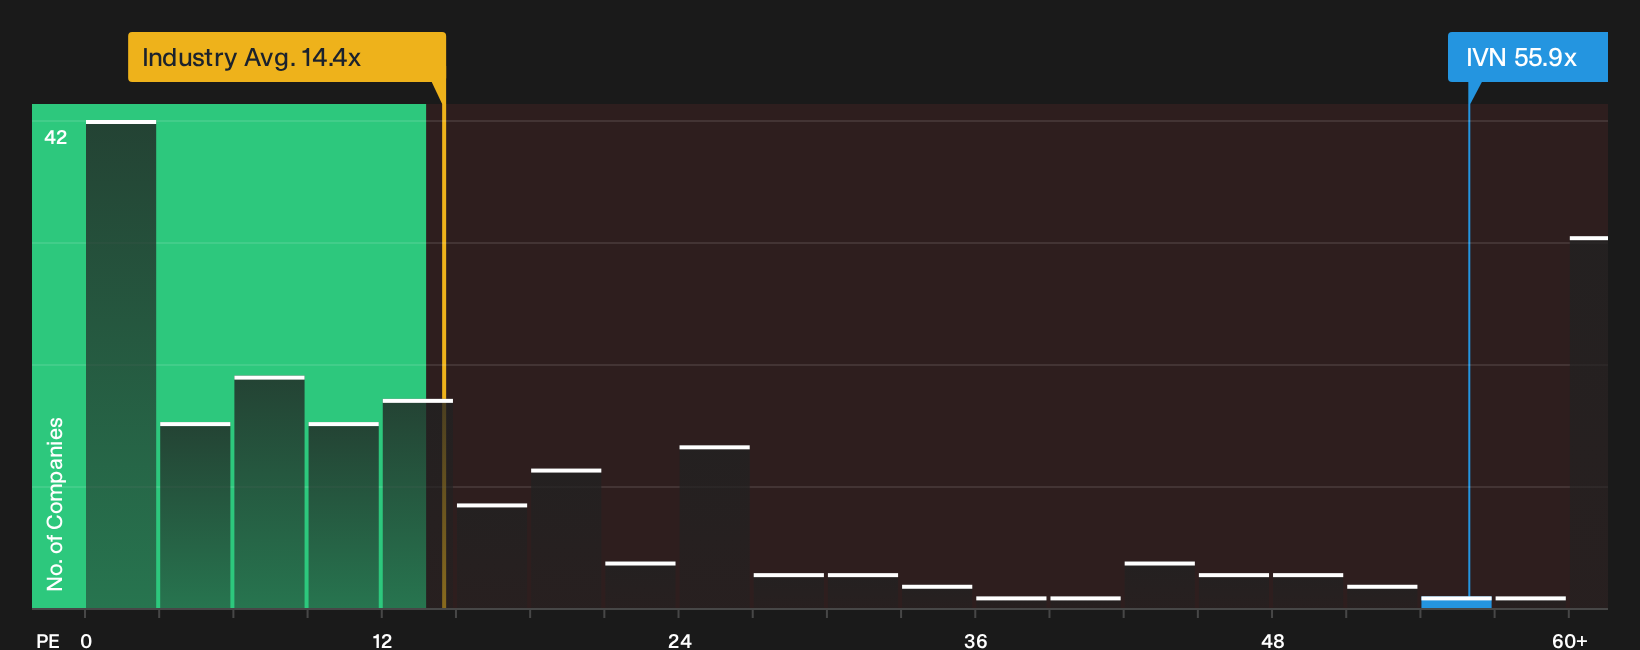
The fair value narrative for Ivanhoe Mines points to undervaluation based on discounted cash flows, yet the current P/E ratio near 55.9x tells a very different story. That multiple is roughly 4x the Canadian Metals and Mining industry at 14.4x and well above a fair ratio of 24.7x, which signals meaningful valuation risk if sentiment cools or forecasts shift.
See what the numbers say about this price in more detail. Start with our valuation breakdown, then weigh up whether the current premium still feels comfortable for your own risk tolerance See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of data points in this Ivanhoe Mines story pull in opposite directions, so move quickly from headline takes to your own judgment by weighing both the upside and the red flags in the 2 key rewards and 1 important warning sign.
Want more ideas beyond Ivanhoe Mines?
If Ivanhoe Mines has your attention, broaden the watchlist now and line up a few backup options before the market moves and the best ideas thin out.
Use these focused screens on Simply Wall St to pressure test your next moves and spot opportunities you might otherwise skip past:
- Hunt for pricing disconnects by reviewing our quantified list of high quality companies that still look overlooked in the numbers through the 7 high quality undiscovered gems.
- Protect your downside first and chase upside second by filtering for financially resilient businesses using the 9 resilient stocks with low risk scores.
- Anchor your research in financial strength and reduce balance sheet surprises by starting with the list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com