


EN
Is Macquarie Group (ASX:MQG) Expensive As Earnings And Dividend Growth Lift Interest?
Macquarie Group (ASX:MQG) is back in the spotlight after reporting higher net income, net interest income, and earnings per share for the half year to 30 September 2026, alongside announcing a larger ordinary dividend.
The recent earnings announcement and dividend increase arrived after a strong run, with Macquarie Group’s share price up 23.47% year to date and the stock delivering a 26.76% total shareholder return over the past year, which signals solid momentum rather than a late surge.
Scan the banking and financials space for other dividend and earnings stories that resemble Macquarie Group’s current momentum by reviewing the hand picked 5 dividend fortresses.
After that surge and a modest 4.4% gap to analyst targets, Macquarie Group screens expensive on some models and cheap on others. Is the market being cautious for good reason, or mispricing the rebound?
Most Popular Narrative: 14.7% Overvalued
Against the last close of A$251.54, the most followed narrative on Macquarie Group pegs fair value at A$219.39. This frames the current price as richer than that assessment and sets up a clear tension between market optimism and valuation discipline.
Importantly, this assessment is based primarily on Macquarie’s existing businesses and FY26 earnings. It does not assign significant value to stronger future investment markets, additional asset sales, further growth in private credit, increased assets under management or expansion of the banking business. These may provide additional upside over time, but remain subject to financial-market conditions, commodity volatility, investment performance, credit losses, regulation and the timing of asset sales.
See why 14 investors see Macquarie Group as 15% overvalued.
Result: Fair Value of A$219.39 (OVERVALUED)
Still, any stumble in key areas, such as commodities trading or credit quality, could quickly challenge this Macquarie Group valuation story and reset sentiment.
Find out about the key risks to this Macquarie Group narrative.
Another View On Macquarie Group’s Valuation
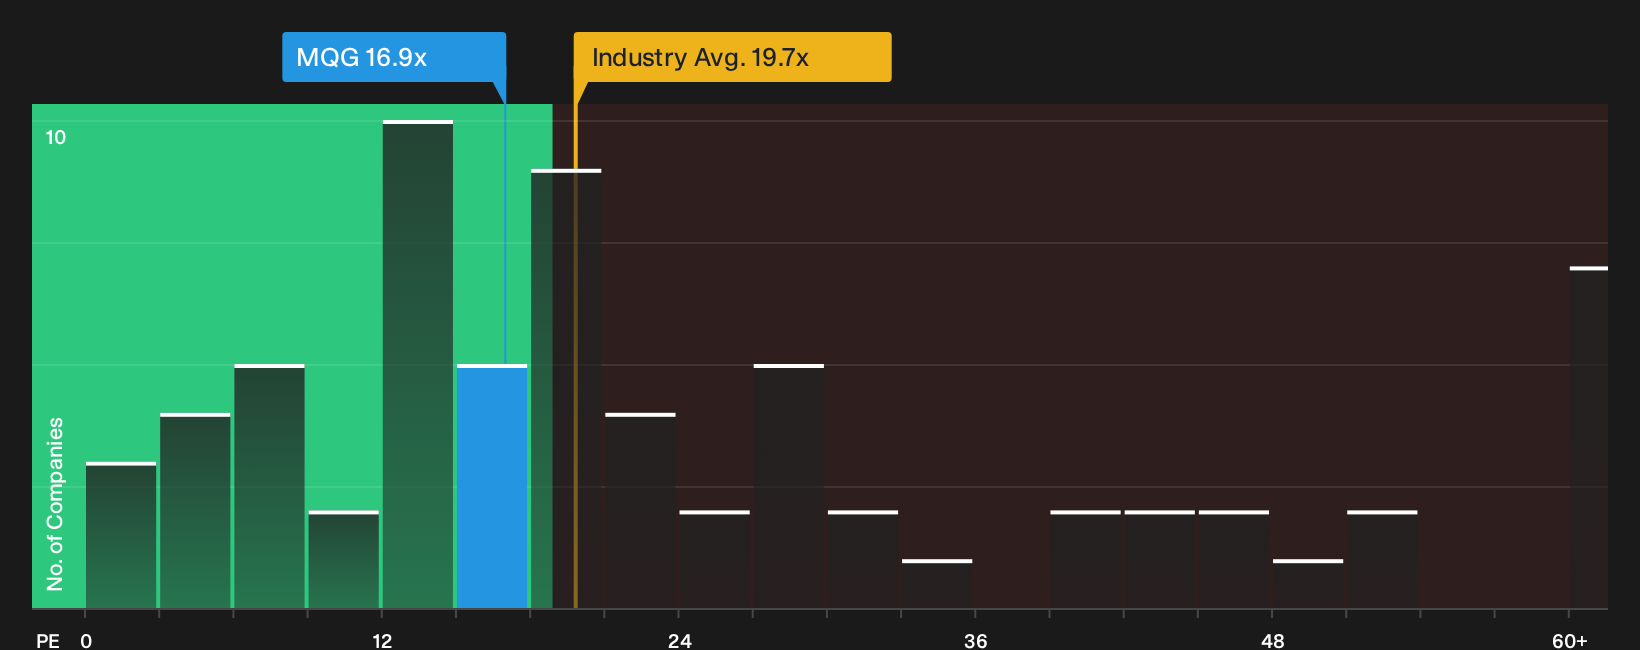
Macquarie Group looks very different when you focus on its current P/E of 16.9x. That ratio sits below the Australian Capital Markets industry on 19.7x and also below the peer average of 23.3x, while the fair ratio is estimated at 22.4x. If the market moved closer to that fair ratio, today’s pricing would look less stretched than the A$219.39 narrative suggests. This raises the question of which signal should serve as the anchor.
For investors who rely on earnings multiples rather than cash flow models, the next step is to see what the numbers imply for risk and room for error in more detail See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty of numbers and opinions are already in the mix, so now is the time to pressure test Macquarie Group against your own checklist and move fast while sentiment is still forming. To weigh the upside against the concerns in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Macquarie Group sized investment ideas?
If you stop with Macquarie Group, you risk missing out on other opportunities that match your goals, risk comfort and income needs.
- Target reliable income streams by scanning the hand picked 5 dividend fortresses that highlight companies combining yield with staying power.
- Hunt for quality priced below its potential through the 2 high quality undervalued stocks that surface financially sound stocks trading at a discount.
- Prioritise resilience in tougher conditions by using the 6 resilient stocks with low risk scores to focus on businesses with steadier balance sheets and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com