


EN
What Just Happened With Fluor (FLR) Shares?
Fluor (FLR) just posted third quarter results that swung from a large loss to a profit, paired with record new project awards and fresh contract wins across nuclear energy, mining and data center construction.
Fluor’s shares jumped 8.28% on the day of the earnings release and are now at $50.33, with a 7 day share price return of 8.52% that contrasts with a 90 day decline of 4.95%. The 5 year total shareholder return of 112.99% points to momentum built over a longer horizon.
Scan how Fluor’s contract momentum compares with other engineering and infrastructure plays by checking the hand picked 42 power grid technology and infrastructure stocks in this space.
After an 8% single day jump and a five year total return above 100%, the real tension is simple. Is Fluor’s recent surge just catching up to its contract pipeline, or has the rerating already run ahead of the fundamentals on offer at today’s price?
Most Popular Narrative: 1% Overvalued
Fluor closed at $50.33 against a narrative fair value of $50, which leaves almost no valuation gap once the bearish analyst Narrative on Simply Wall St is used as the anchor and its assumptions are applied.
The shift to an asset light model and sizeable share repurchases funded by over US$2.4 billion of NuScale monetization proceeds risks prioritizing capital returns over investment in project controls and risk management. Any further project missteps could leave earnings and cash flow short of what a leaner balance sheet and reduced legacy exposure might suggest.
See why 2 investors see Fluor as 1% overvalued.
Result: Fair Value of $50 (ABOUT RIGHT)
Still, if Fluor converts more of its nearly US$30b mining pipeline on reimbursable terms and executes nuclear contracts smoothly, bearish assumptions could soon appear conservative.
Find out about the key risks to this Fluor narrative.
Another View: Fluor’s P/S Signal
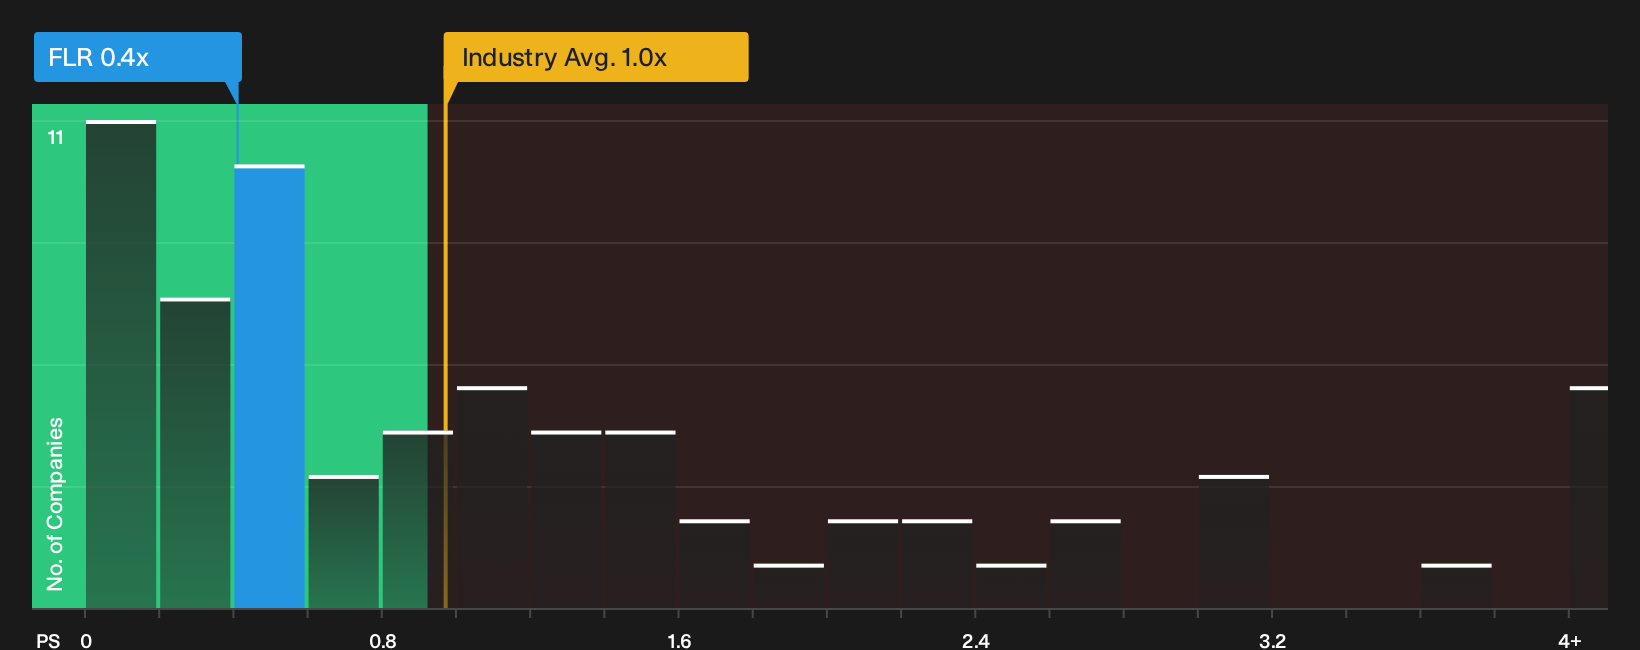
On simple earnings expectations, Fluor looks roughly aligned with the bearish fair value of $50. Yet the P/S ratio tells a different story. The stock trades at 0.4x sales versus 0.9x for the US Construction industry and 1.1x for peers, while the fair ratio sits at 0.8x. That gap suggests investors are still pricing in execution risk. It may also hint at upside if sentiment shifts toward the fair ratio.
See what the numbers say about this price in more detail in the valuation breakdown, then decide where you think Fluor should trade relative to that fair ratio narrative See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So if the mood around Fluor feels finely balanced, do not sit on the sidelines and outsource your judgement. Look through the underlying metrics, weigh the optimism around its potential rewards, and then pressure test your own thesis with the 3 key rewards.
Looking for more Fluor sized investment ideas?
If Fluor has sharpened your focus, keep that momentum going by lining up a few more high conviction ideas before the next opportunity races past.
- Target resilience first and stress test your downside by scanning companies that score well on stability and financial strength with the 30 resilient stocks with low risk scores.
- Hunt for pricing power and quality at a reasonable tag by checking the 33 high quality undervalued stocks that blend dependable cash flows with solid balance sheets.
- Spot tomorrow’s potential leaders before the crowd by working through a 19 high quality undiscovered gems hiding strong fundamentals behind quieter tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com