


EN
Learn Why The Bull Case For Oracle Stock Could Change Following Lost Cloud Contracts
- Oracle has raised roughly US$20b through a completed US$10b follow on equity sale and multiple bond issues, while also seeing major AI cloud contracts with Microsoft and a planned US$7b chip lease with Tencent fall away, all against a backdrop of heavy data center spending and negative free cash flow.
- These moves leave Oracle funding an aggressive AI infrastructure build with more leverage and dilution, while demand visibility hinges increasingly on a concentrated backlog, especially long term contracts with OpenAI and other large AI clients.
- We will now look at how Oracle's heavier funding needs and the lost Microsoft capacity deal could reshape the longer term investment narrative.
Scan how other AI infrastructure plays are handling heavy capex, big backlogs, and funding trade offs by reviewing the 53 AI infrastructure stocks.
Oracle Investment Narrative Recap
To own Oracle, you need to believe the heavy AI data center build eventually converts its large contract backlog into cash, despite today’s negative free cash flow and high leverage. The immediate swing factor is whether OpenAI and other large AI tenants ramp usage fast enough to absorb this capacity as Microsoft and Tencent fall away.
The biggest near term risk is that funding needs stay high while demand timing slips, leaving Oracle with expensive debt, recent equity dilution, and long data center commitments. According to andre_santos, an investor in the Simply Wall St Community, the balance between capital intensity and returns is the real tension to watch.
Among the recent updates, the expanded Oracle collaboration with OpenAI looks most tied to that core AI thesis. It connects OpenAI’s models with Oracle AI Workspace, Oracle AI Database, OCI, and Fusion applications so customers can run more of their daily operations through ChatGPT and Oracle tooling, which directly leans on Oracle’s cloud stack.
This matters for catalysts because it anchors Oracle’s AI infrastructure story in concrete usage scenarios across security, low code app building, and SMB bundles, rather than just abstract GPU capacity. It also concentrates execution risk around how efficiently Oracle turns this OpenAI centric demand, and similar alliances, into sustained workloads that support its recent US$20b capital raise.
On andre_santos’s numbers, Oracle reaches a fair value of US$192.59 through a weighted blend of a US$208.27 DCF output, EPS growth projections using a 28 P/E, and mean reversion on historical P/S, EV/EBITDA, and P/E multiples, all discounted using a 12.00% cost of capital.
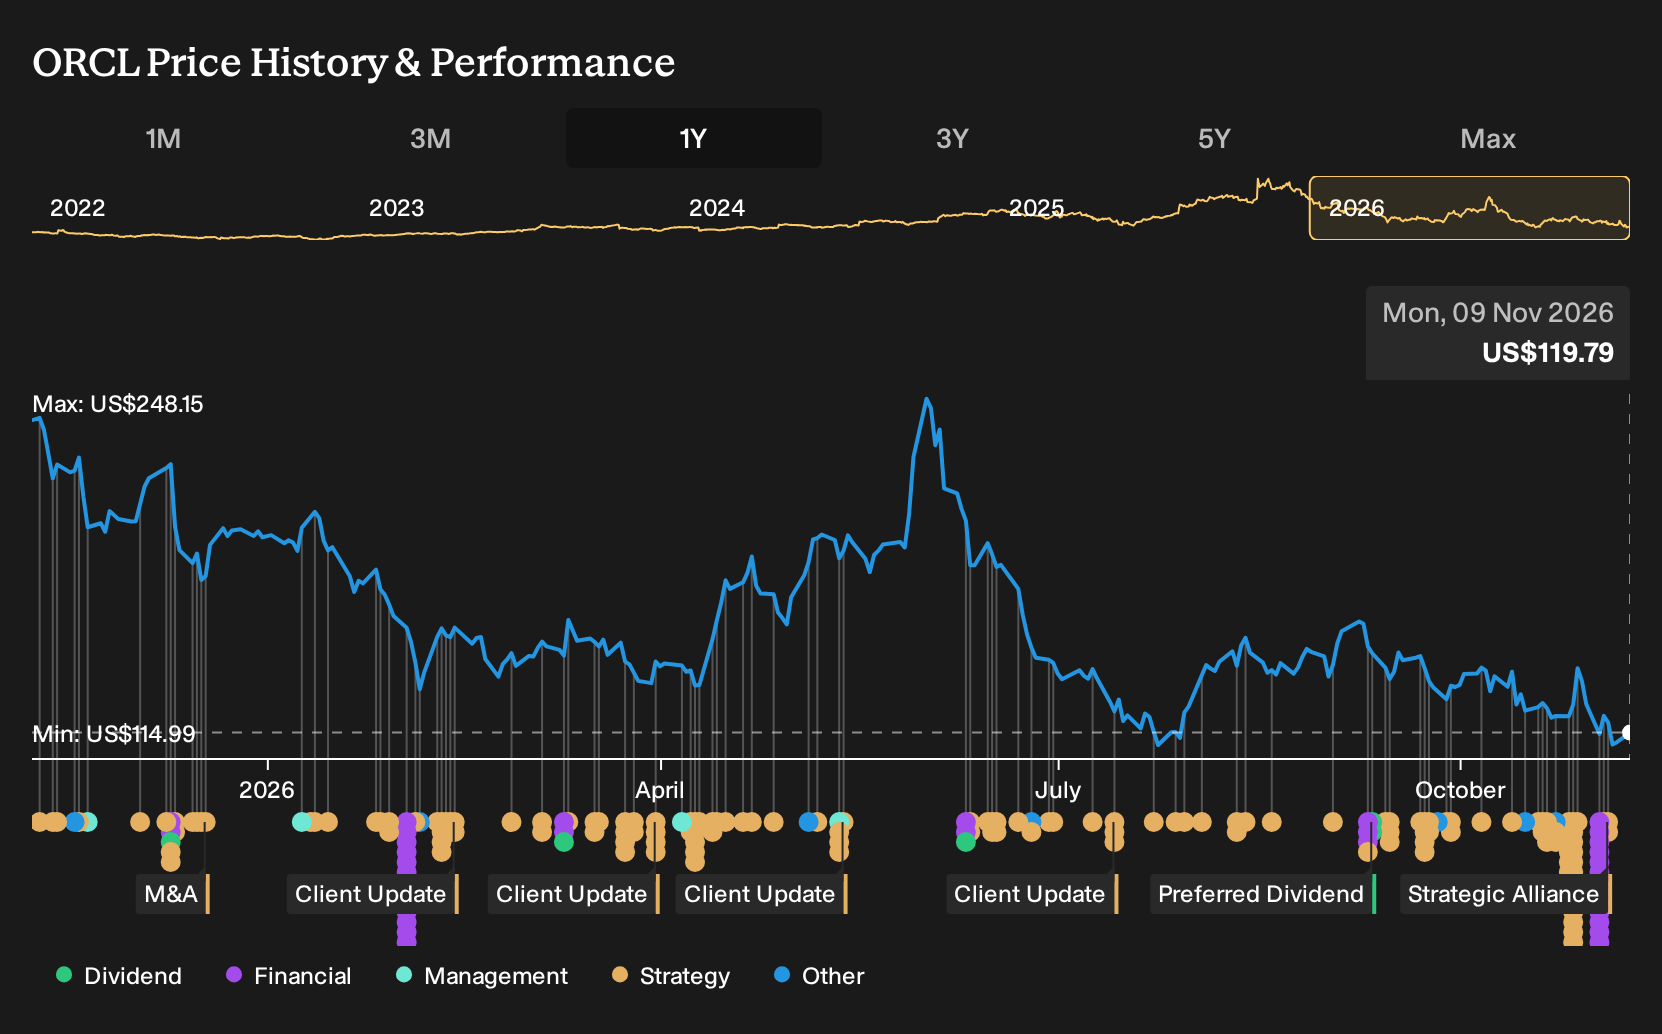
Uncover why Oracle's fair value indicates a 61% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Oracle analysts frame the new OCP optics telemetry work as a catalyst, not a side project. They were already modeling about US$216.9b of revenue and US$52.5b of earnings by 2029, on a 32.3x P/E. That is a far more upbeat story than the baseline, and it may shift again as this news beds in.
Explore 17 other Oracle fair value estimates, including one that suggests as much as 225% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Oracle research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Oracle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oracle's overall financial health at a glance.
Looking for more investment ideas beyond Oracle?
If the Oracle story has sharpened your thinking about risk, balance sheets, and long term cash generation, you can use that same lens to scan a wider universe of opportunities with the Simply Wall St Screener.
- For investors who want income that looks better supported, you could start with companies aiming to be payout workhorses through the 6 dividend fortresses.
- If capital preservation sits higher on your priority list, you can sort for steadier operators using the 30 resilient stocks with low risk scores.
- When you want to look for less crowded opportunities with strong fundamentals, you can cast a wider net across the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com