


EN
Why VNET Group Fell 66% Even As Sales Rose
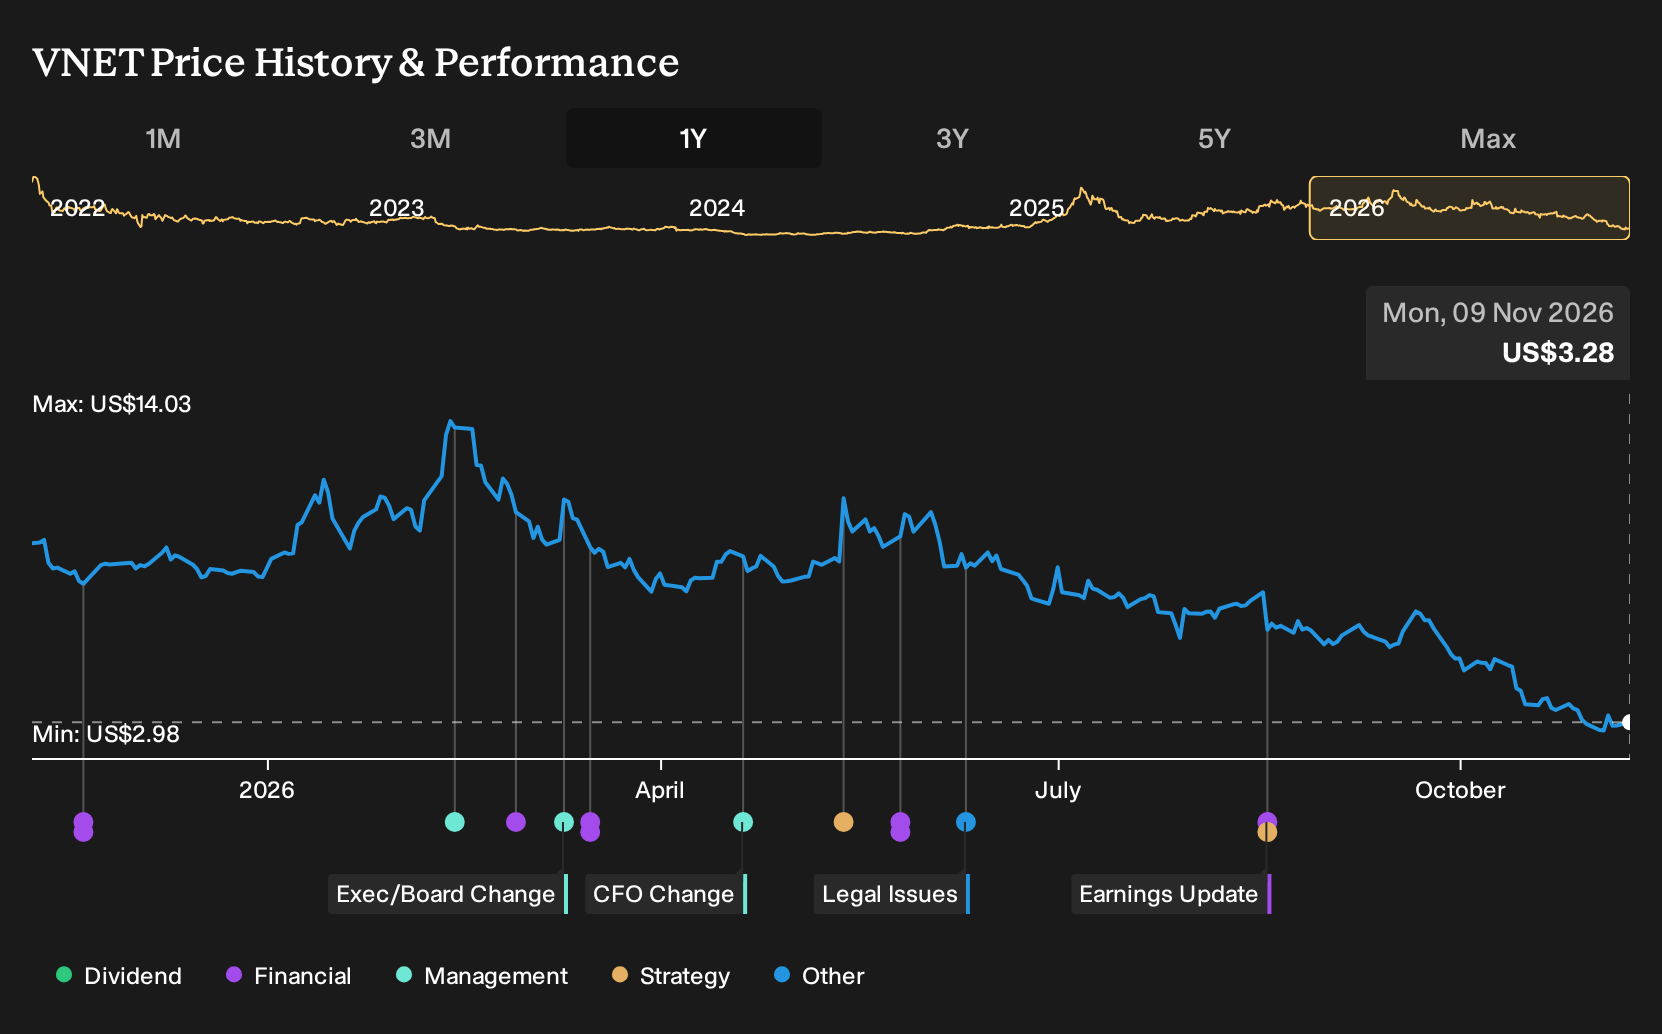
VNET Group kept reporting record wholesale data center capacity and double digit revenue gains, yet long term holders still saw a brutal outcome. For VNET Group shareholders, the loss over the past year was 66.2%, including dividends. If you had been weighing a position back in November 2025, with bullish analysts on one side and warnings about heavy debt and aggressive expansion on the other, which signals would have seemed most convincing before that decline unfolded?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
VNET Group is not the only name tied to this theme. Zero in on 53 AI infrastructure stocks and compare how each one is priced.
The Two Stories VNET Group Investors Had To Weigh
The shares cost US$9.65 at the start of the period, and VNET Group sat between two sharply different stories about what came next.
On the optimistic side, the bull narrative pointed to a Fair Value of US$14.09, based on assumptions of 17.4% revenue growth and profit margins reaching 2.8% within three years.
The bear case argued for a Fair Value of US$5.74, with slower 14.8% revenue growth, 1.2% margins, and concern that heavy debt and big 2025 capex could strain refinancing.
What The VNET Group Evidence Put To The Test
The big reveal for VNET Group was Q2 2026. Net revenue reached RMB 2,778.7 million, above Q2 2025, which supported the growth part of the bullish story. Net income excluding extra items moved from a loss of RMB 11.9 million to a much larger loss of RMB 144.7 million, and net margin fell to 5.2%. The evidence cut both ways.
For future ideas, focus on whether a growth pitch also assumes improving profitability. Then track net margin and absolute profit in each report to see if that upgrade is actually arriving.
What Today’s VNET Group Price Is Asking You To Believe
VNET Group trades at US$3.27 after a 66.2% loss over the past year. The bearish analyst Narrative on Simply Wall St still places its Fair Value above that level, framed around how reliably wholesale AI data center demand can turn into cash that services debt and funds heavy 2026 spending.
The key question is whether a buyer today believes VNET Group can fill and monetize its secured capacity quickly enough, on terms rich enough, to cover large planned capex and refinancing needs without prolonged pressure on earnings and the balance sheet.
"The main thing that has to go right is that VNET Group turns its large pipeline of long-term wholesale IDC orders and CATL-backed compute energy projects into sustained cash generation that comfortably services debt and funds 2026 capex of RMB 10 to 12 billion."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 30% below our estimate - targets borrowers rejected by mainstream lenders using an automated bank-integrated lending platform.
- Company 2 - 42% below our estimate - sells full-stack AI factory hardware and software into large-scale cloud infrastructure buildouts.
- Company 3 - 31% below our estimate - prices mobile ad campaigns on app installs and captures the spread between cost and outcome.
Those are three of them. See all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com