


EN
Ondas (ONDS) Expands Its Drone Plans, Is The Stock Still Cheap?
Ondas (ONDS) is back in focus after a fresh purchase order under its Digital Bat program and plans to buy ARAN Defense to build a dedicated production line for tactical attack drones.
The share price reaction has been volatile. Ondas is up 11.9% on a 1 day share price return to US$5.97 and slightly ahead over the past week, yet the 30 day share price return is down 11.3% and the 90 day move is down 38.7%. A very large 3 year total shareholder return reflects how earlier investors have already seen major swings. Recent spikes in trading ahead of Q3 earnings, the Stemme deal for ULTRA aircraft production and now the Digital Bat and ARAN Defense updates point to shifting views on both the growth potential in autonomous systems and the risks around execution and capital needs.
Capitalize on the momentum around Ondas and defense-focused autonomy by scanning a curated set of 92 robotics and automation stocks that are also tied to real-world security and automation demand.Ondas now trades well below its recent highs, yet sits on ambitious drone and ISR build-out plans. Does that mix of execution risk and expansion potential still skew the risk reward toward buyers at this level?
Most Popular Narrative: 24% Undervalued
Ondas closed at $5.97, while the most followed narrative on Simply Wall St pegs fair value at $7.89, implying upside based on that framework according to DownUnder, an investor in the Simply Wall St Community who built a detailed growth and risk case around the business.
If I consider a 3y growth of 80% (I don't think they can keep the 13 fold growth), which should be possible with a 20% profit margin (currently 49.25%), I think a FV of 7.89 is achievable and makes it 13.2% undervalued with a risk level of 10%. If you were to adjust the risk to 15% because of the nature of acquisition-based growth, then FV would sit on 6.9, which is fairly valued to the current price today (9th October 2026).
See why 16 investors see Ondas as 24% undervalued.
That view uses a 10% discount rate and assumes Ondas can convert its recent revenue ramp and acquisitions into profitable growth while managing integration, customer concentration and funding risks that are all spelled out in the same write up.
Result: Fair Value of $7.89 (UNDERVALUED)
Still, the Ondas story could flip quickly if integration of its many acquisitions stumbles, or if further equity raises dilute shareholders more than expected.
Find out about the key risks to this Ondas narrative.
Another View On Ondas Valuation
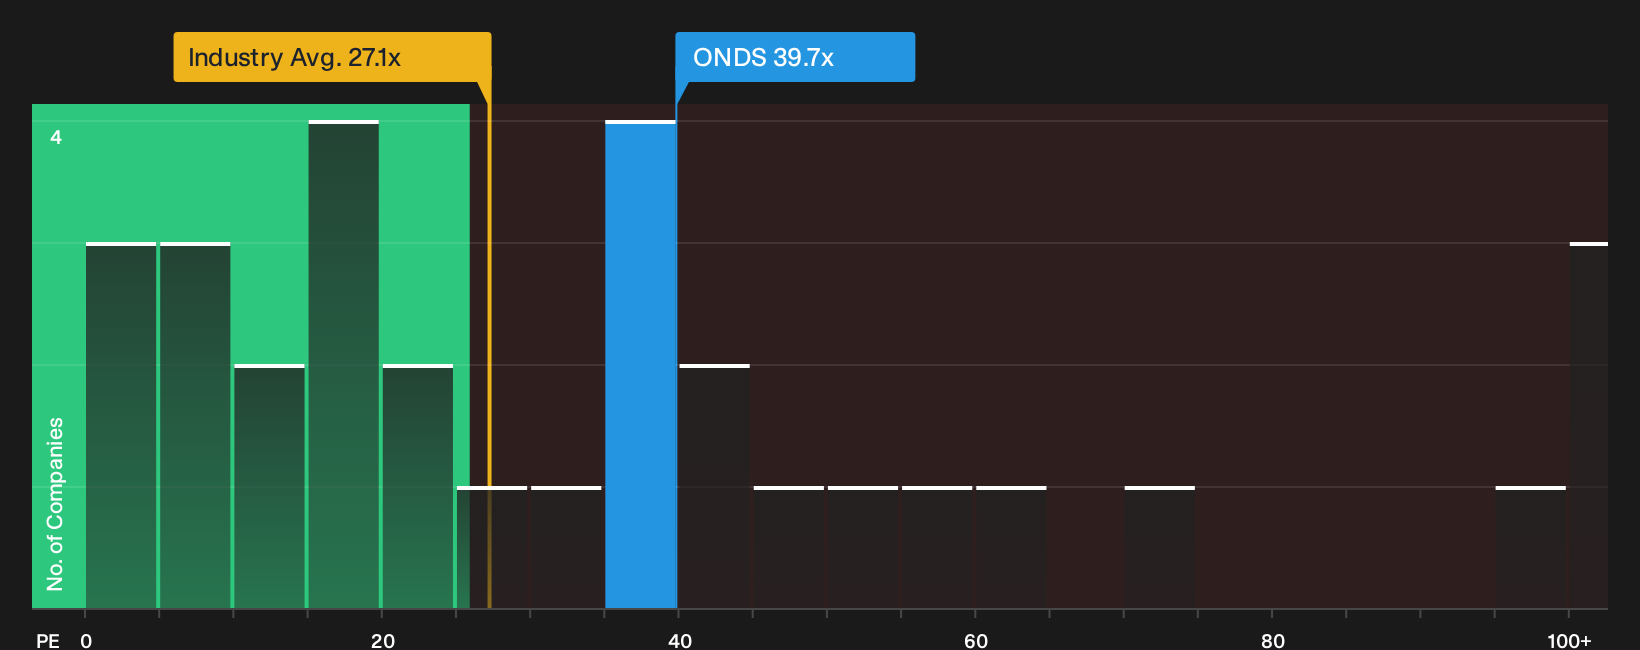
The community fair value work around Ondas leans on growth and margins. A second lens looks at what investors are currently paying for each dollar of earnings. At a P/E of 39.7x, the stock trades richer than the US Communications sector on 27.1x and above a fair ratio of 20.3x that our model suggests the market could move toward over time.
That gap means the share price already bakes in a lot of optimism and leaves less room for disappointment if forecasts prove too optimistic. It also raises a clear question for anyone following Ondas: Is this premium multiple a sign of long term opportunity, or is it a source of valuation risk if sentiment cools off?
To see how this earnings multiple stacks up in more detail, including against close peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mixed tone around Ondas, with both execution risks and upside scenarios on the table, means the next move rests with you, not the market commentators. If you want to weigh the red flags against the potential payoffs yourself, start with the 3 key rewards and 4 important warning signs
Looking for More Ondas Investment Ideas?
Do not stop your research with Ondas alone. Broaden your watchlist now and give yourself more options before the next set of catalysts hits.
- Target potential bargains by scanning a curated 33 high quality undervalued stocks that match strong fundamentals with more reasonable prices.
- Strengthen capital preservation by focusing on a 30 resilient stocks with low risk scores that screens for resilient balance sheets and lower volatility profiles.
- Unearth fresh opportunities by checking a 19 high quality undiscovered gems that have quality metrics without heavy mainstream attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com