


EN
Do Strong Quarterly Earnings Change The Bull Case For HNI (HNI)?
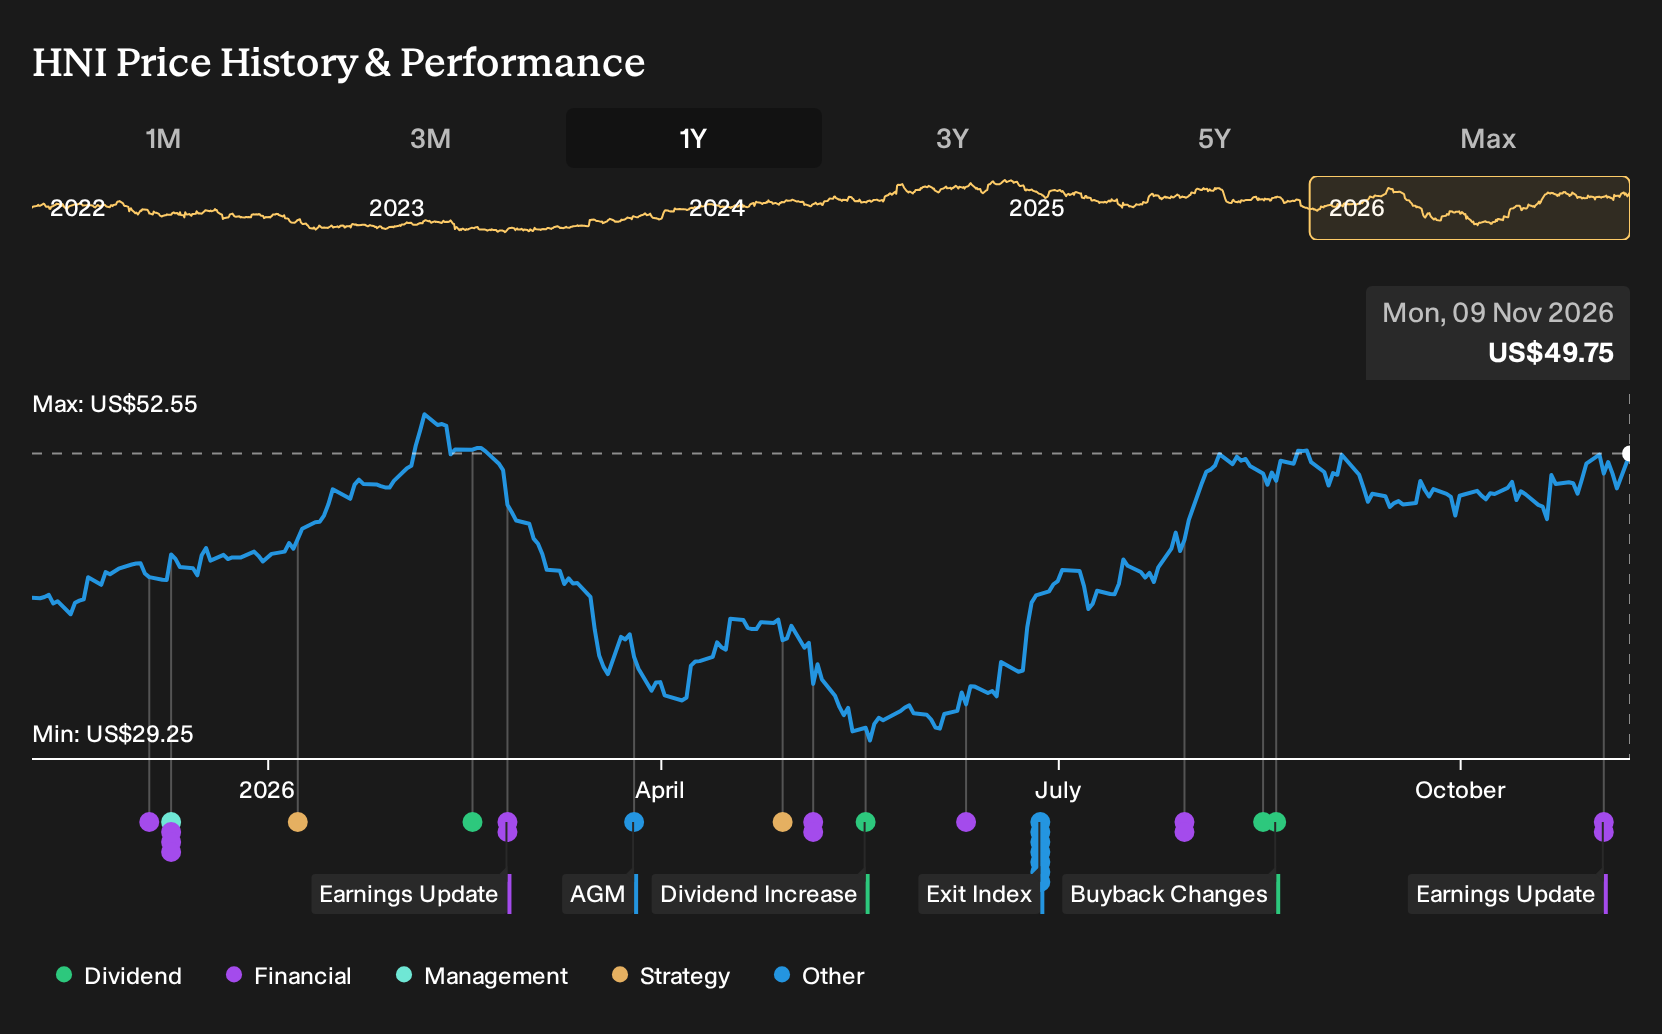
- HNI Corporation reported third quarter 2026 sales of US$1,592.9 million and net income of US$90 million, with basic and diluted earnings per share from continuing operations at US$1.23.
- An interesting tension emerges as HNI's third quarter performance shows much higher sales and earnings than a year earlier, while net income for the first nine months remained close to flat despite materially higher sales.
- This article examines how HNI's investment narrative is shaped by strong third quarter earnings alongside guidance that calls for nearly doubling Workplace Furnishings sales.
What Is HNI's Investment Narrative?
To own HNI, you have to buy into a fairly simple idea. This is a furniture and building products manufacturer that lives or dies on execution, pricing discipline and how efficiently it turns capital into cash. The third quarter print fits that story. Sales and earnings for the quarter were much higher than a year earlier, yet the first nine months show net income broadly flat, which flags that one strong quarter does not resolve the grind of integrating acquisitions, digesting one off items and rebuilding margins.
The new outlook matters because it leans heavily on Workplace Furnishings. Management is signaling that with Steelcase included, that line is expected to nearly double in the fourth quarter, while legacy Workplace Furnishings is only guided to low single digit growth and Residential Building Products is guided roughly flat. That mix puts most near term weight on execution around office demand, integration synergies and working capital, at a time when margins are thin, the dividend is not well covered by earnings and debt coverage by operating cash flow is described as weak.
Yet one issue sits uncomfortably alongside the upbeat earnings and guidance narrative.
There's only one way to know the right time to buy, sell or hold HNI. Head to Simply Wall St's company report for the latest analysis of HNI's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$73.88 to almost US$198.99, which signals that views on HNI are all over the map. Those opinions pre date the latest earnings and guidance. Treat that spread as a prompt to compare your own assessment of HNI’s execution risks and opportunities.
Explore 2 other HNI fair value estimates, including one that suggests it could be worth just $73.88!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HNI research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for HNI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HNI's overall financial health at a glance.
Looking For More Ideas Beyond HNI?
If HNI has raised fresh questions about where to put capital to work next, broaden the search with a few focused stock lists built around different risk and income profiles.
- For investors who want potential upside without taking on extreme balance sheet stress, review a 30 resilient stocks with low risk scores that filters for companies with more resilient financial profiles.
- If reliable income is a priority, consider a 6 dividend fortresses that highlights businesses offering yields above 5% while aiming for stability.
- For those hunting for under the radar potential, scan a 19 high quality undiscovered gems that surfaces companies with strong fundamentals that are not widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com