


EN
What Repligen Holders Got Right
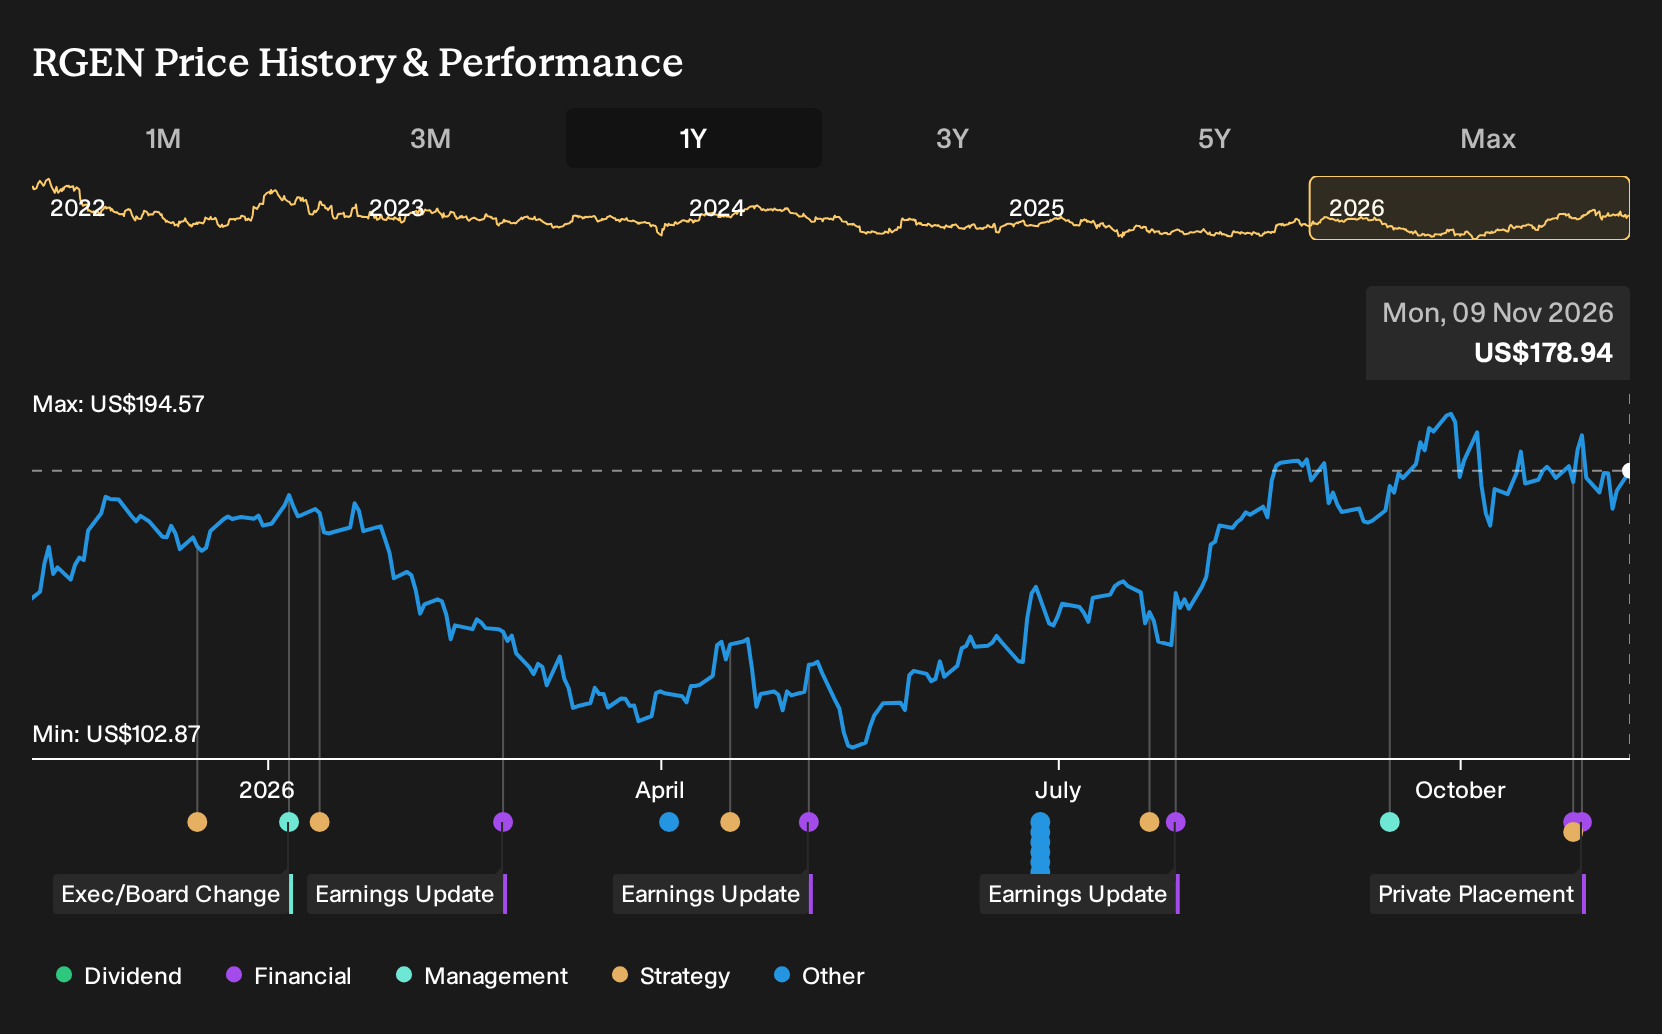
Repligen’s headline move this year was a US$1.5b agreement to buy BioLife Solutions, bringing a high recurring revenue cell therapy franchise into its bioprocessing toolkit. Investors who held Repligen over the past year are up 22.8%, including dividends. If you were weighing a purchase back on 9 November 2025, you had to decide what to trust more: bullish calls for renewed demand or warnings about funding and concentration risk.
The move put Repligen in the middle of this trade. Scan 36 healthcare AI stocks for other companies exposed to it.
The Two Stories Repligen Investors Were Arguing Over
The shares cost US$143 at the start of the period, and anyone looking at Repligen then had to pick between two very different stories about what might come next.
The bullish script pointed to a Fair Value of US$180, an implied upside price based on expectations that dual manufacturing in the U.S. and Europe, along with greater APAC presence, would support more resilient global sales and reduce revenue concentration risk.
The more cautious view anchored on a Fair Value of US$131. This implied downside scenario put more weight on inflation, higher interest rates, and cautious biotech R&D budgets potentially tempering future revenue growth, even with strong order trends.
What The Results Changed For Repligen’s Story
The BioLife acquisition was the clearest new fact for Repligen, backing the optimistic view that recurring cell therapy consumables could deepen its toolkit. The accounts pulled in the other direction. Revenue in Q3 2026 was US$209.3 million versus US$188.8 million a year earlier, yet net income swung to a loss and net margin moved from 7.9% to a loss of 18.4%. The evidence cut both ways.
The useful takeaway is where you focus your checks. When a thesis leans on higher quality revenue and better mix, track two paired metrics at each update. First, watch whether recurring sales and acquisitions grow the top line. Second, track whether net margin and net income move in the same direction.
What Repligen’s Current Price Already Assumes
Repligen shares trade at US$179, with this price reflecting a 22.8% gain over the past year. The bullish analyst Narrative on Simply Wall St places its Fair Value above that level, based on a belief that recent operational shifts point to a stronger earnings profile.
That Narrative leans on digital bioprocessing, newer modalities, and efficiency programs as the real needle movers. Anyone paying today’s price has to judge whether sustained execution in PAT, cell therapy, and APAC can really keep supporting that earnings and margin story.
"The Repligen thesis has been reviewed and reaffirmed, with the focus shifting from broad above-industry growth expectations toward a more specific view on digital bioprocessing, newer modalities, and margin structure as the key drivers and watchpoints for the story from here."
The price and this Narrative do not agree. → Uncover what this Narrative says Repligen is actually worth
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 31% below our estimate - sells coconut based drinks through retail, e commerce and foodservice channels.
- Company 2 - 30% below our estimate - supplies custom chips and connectivity hardware underpinning large cloud customers' scaling needs.
- Company 3 - 35% below our estimate - expands subscription software and database services tied to large AI infrastructure contracts.
Three companies from the same screener. Open all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com