


EN
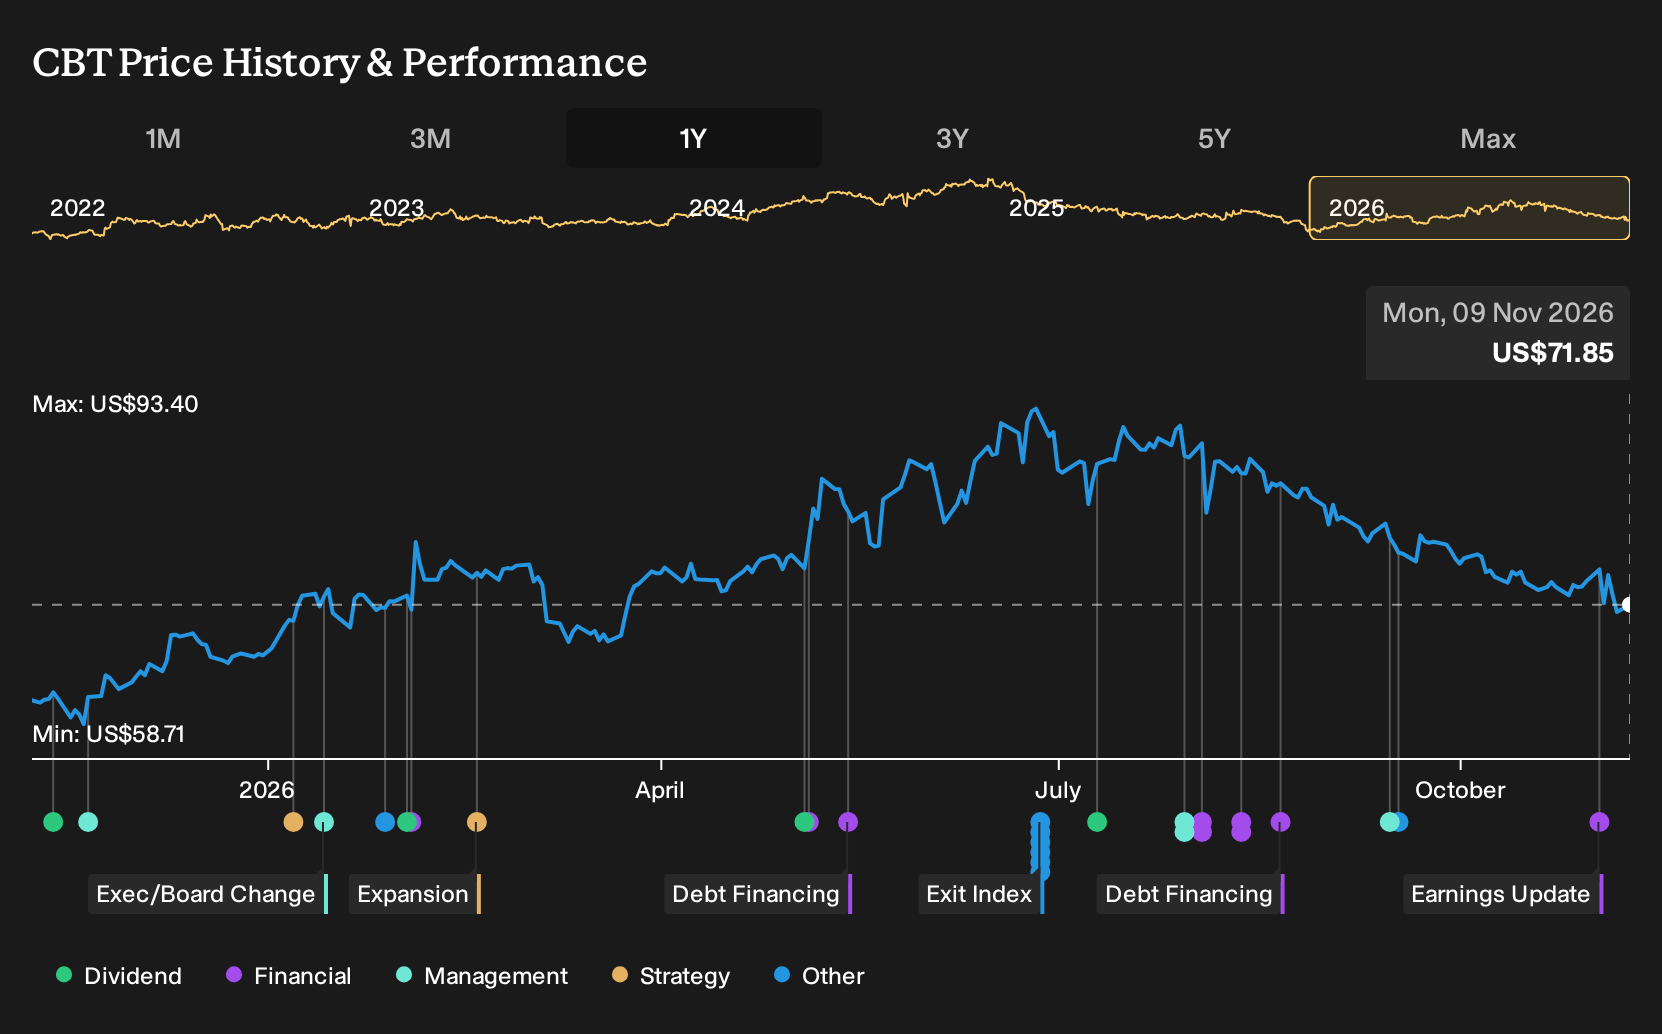
Did Earnings Update Just Shift Cabot (CBT) Investment Narrative?
- Cabot reported fourth quarter 2026 sales of US$1,009 million and net income of US$66 million, with basic EPS from continuing operations of US$1.26.
- For the full year, sales were US$3,744 million and net income was US$213 million. This indicates that the quarterly profit was stronger, while the annual earnings base was weaker.
- We will now look at how Cabot's wider investment narrative is influenced by this combination of stronger quarterly and softer full year earnings.
Scan how Cabot's latest earnings profile compares with peers by reviewing a curated set of 19 high quality undiscovered gems that may be flying under most investors' radar.
Cabot Investment Narrative Recap
To own Cabot, you need to be comfortable with a specialty materials business that leans on tires and broader industrial demand, while also trying to scale higher value products such as battery materials. The latest quarter showed a stronger profit base than the full year, suggesting execution on the cost side is working. However, the softer annual earnings keep near term profit recovery as the key catalyst.
The biggest risk right now is that lower full year net income of US$213 million and reduced EPS leave less room for error if demand or pricing weakens. If cost savings or mix improvement in areas such as Battery Materials slow, or if one off items recur, the earnings trajectory described in the analyst consensus Narrative on Simply Wall St becomes harder to achieve.
The fresh data point that matters most is the fourth quarter 2026 earnings report itself. Cabot posted quarterly sales of US$1,009 million and net income of US$66 million, compared with full year sales of US$3,744 million and net income of US$213 million. That mix points to a comparatively stronger finish to the year, which matters for any near term earnings inflection story.
At the same time, full year profit came in lower than the prior year despite slightly higher revenue, so margin pressure and the impact of large one off items remain central to the risk set. For investors tracking the cost reduction and network optimization efforts highlighted in the analyst consensus Narrative on Simply Wall St, this result turns execution on those programs and the resilience of Battery Materials into practical catalysts to watch rather than just modeled assumptions.
Cabot's narrative projects US$4.0 billion revenue and US$479.7 million earnings by 2029. This represents 3.5% yearly revenue growth and an earnings increase of about US$198.7 million from US$281.0 million today.
Uncover how Cabot's fair value indicates a 23% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts put Cabot’s Battery Materials expansion at the center of their story, with forecasts that earnings could reach about US$527.6 million on revenue of roughly US$4.2 billion by 2029. Those projections were set before this latest earnings release, so you may see those bullish views shift as the new numbers are absorbed.
Explore 2 other Cabot fair value estimates, including one that suggests potential upside of up to 23% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cabot research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cabot. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cabot's overall financial health at a glance.
Looking for more investment ideas beyond Cabot?
Once the Cabot story is on your radar, it can help to compare it with other opportunities that share similar qualities or offer a different mix of risk and reward. The Simply Wall St Screener lets you do that quickly by filtering the market down to a short list that actually matches what you are looking for.
- If capital preservation sits high on your list, start with a group of companies that score well on resilience and financial robustness through the 30 resilient stocks with low risk scores.
- Income focused investors who want yield with a quality filter can review a curated set of higher paying payers through the 6 dividend fortresses.
- For those who like the idea of backing under-followed stories with solid fundamentals, cast a wider net using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com