


EN
Q3 Earnings Hold Guidance Could Be A Game Changer For Cascades (TSX:CAS)
- Cascades Inc. reported third quarter 2026 sales of C$1,267 million, net income of C$30 million and basic EPS from continuing operations of C$0.30, alongside reaffirmed guidance for adjusted EBITDA targets despite tariff and cost pressures.
- The sharper increase in nine month net income to C$90 million and EPS of C$0.89 versus the prior year highlights how cost actions and operational gains are feeding through to earnings, even with only modest movement in reported sales.
- We will now look at how Cascades' steady EPS and reaffirmed EBITDA targets could reshape the investment narrative around its efficiency plans.
Cascades Investment Narrative Recap
For Cascades, the core belief is that efficiency gains and disciplined capital use can steadily lift profitability in a fairly mature packaging and tissue market. The analyst consensus Narrative on Simply Wall St already leans on cost actions, mill ramp ups and portfolio pruning as the main earnings engine. The latest quarter fits that story, with earnings tracking higher on relatively stable sales. In the short term, the key catalyst is execution on these efficiency programs.
The biggest current operational risk is that higher input costs, weaker volumes or slower progress at mills like Bear Island dilute those margin gains. Management reaffirmed adjusted EBITDA targets despite tariff and cost pressure, so this update does not radically change the risk profile. It instead raises the bar on consistent delivery over the next few quarters.
The most relevant recent announcement is Cascades reaffirming its adjusted EBITDA ambition above C$600 million for the second half of 2026 and above C$650 million in 2027, alongside Q3 earnings. That guidance links directly to the cost out and optimization efforts highlighted in the analyst consensus Narrative on Simply Wall St, where a C$100 million profitability uplift by 2026 is central.
For you, that guidance turns into a clear execution test. Earnings for the first nine months of 2026 came in at C$90 million, with C$3,611 million in sales. As a result, the bridge from today’s run rate to those EBITDA targets will likely depend on reaching planned efficiencies at Bear Island and other mills, keeping recovered fiber costs in check and avoiding further one off restructuring hits that could dilute reported net income.
Cascades' narrative projects forecast revenues of C$5.6b and earnings of C$322.8 million by 2029, which assumes 5.4% yearly revenue growth and an earnings increase of about C$196.8 million from current earnings of C$126.0 million.
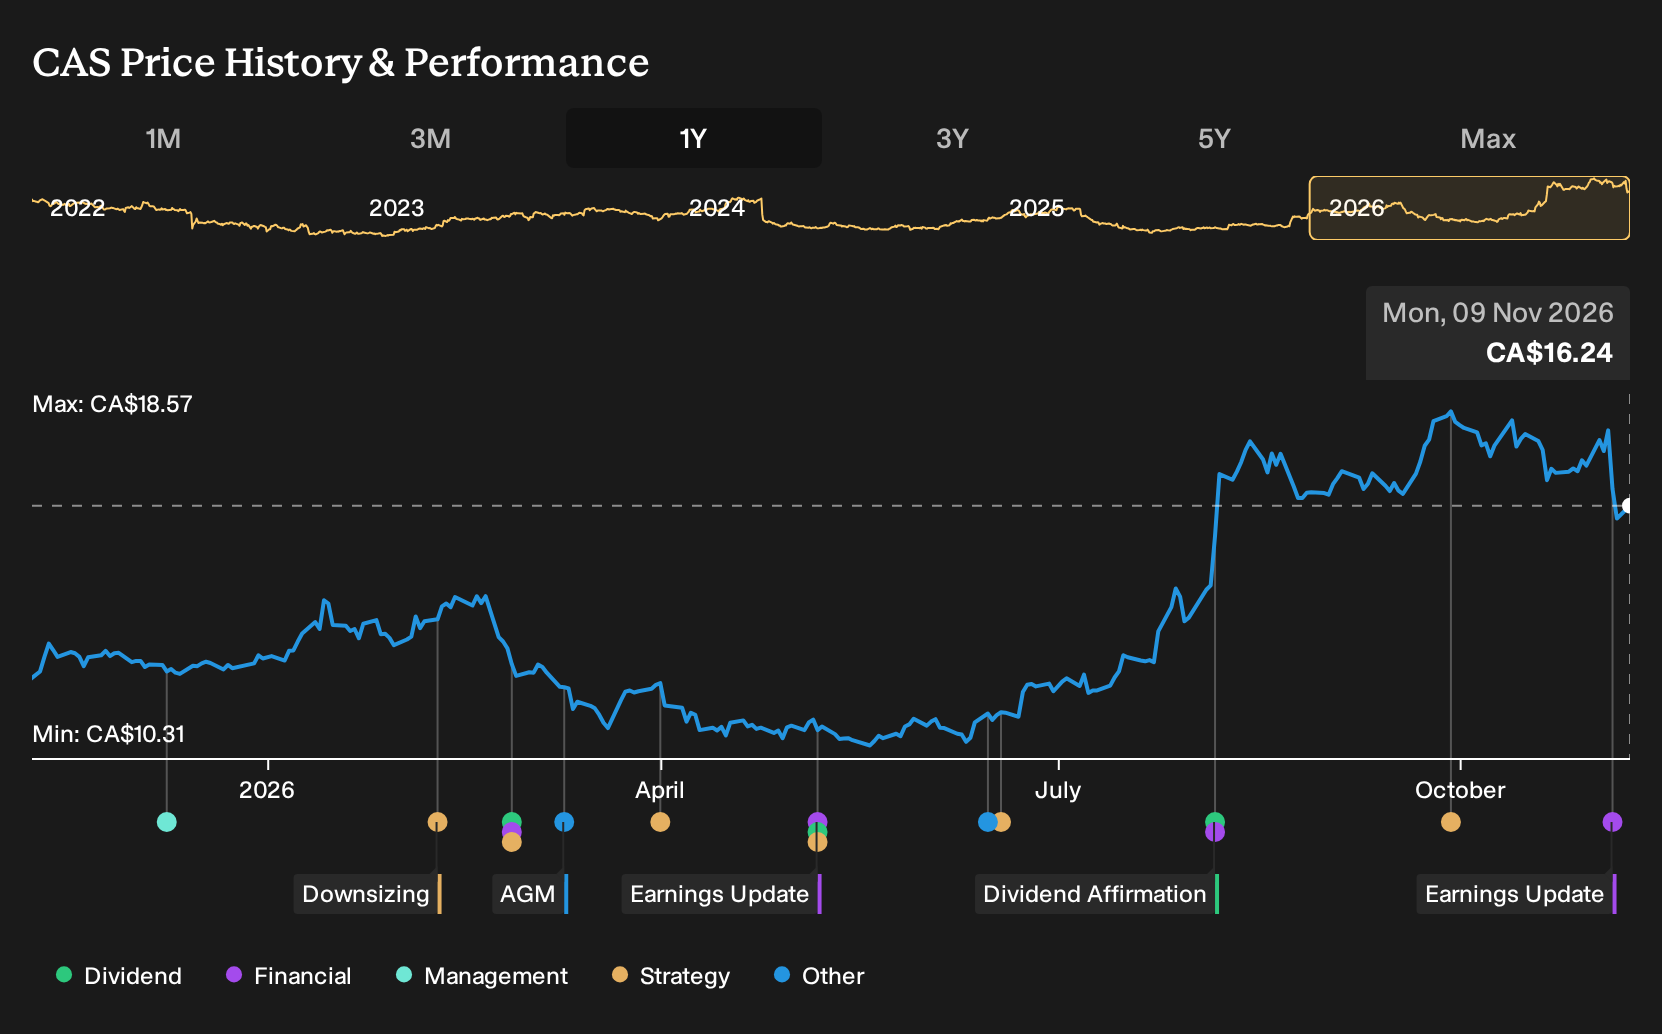
Uncover why Cascades' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Cascades’ input cost risk rather than its efficiency targets. Before this earnings report, the most cautious analysts were still modeling C$5.6b of revenue and about C$385.8 million of earnings by 2029, but on a much lower C$19.5 fair value. This serves as a reminder that reasonable people can read the same numbers very differently.
Explore 2 other Cascades fair value estimates, including one that suggests it could be worth just CA$20.08!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Cascades research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cascades. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cascades' overall financial health at a glance.
Looking for more investment ideas beyond Cascades?
If Cascades has sharpened your focus on efficiency, cash generation and balance sheet strength, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want income plus resilience, scan a curated group of potential yield opportunities through 3 dividend fortresses.
- If capital protection matters most to you, filter for businesses with steadier risk profiles by starting with a 9 resilient stocks with low risk scores.
- When you want a mix of quality and financial strength, use the list of solid balance sheet and fundamentals (5 results) to narrow in on companies with sturdier fundamentals and cleaner balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com