


EN
Marvell Stock’s Selloff Is Overdone as Solid Upside and Valuation Reset Revives Investment Appeal
Marvell Technology’s (MRVL) stock has corrected sharply, falling about 44% over the past month and trading about 54% below its 52-week high. The sharp decline reflects multiple concerns surrounding the company’s proposed acquisition of Lumentum Holdings (LITE), broader weakness across AI-related equities, and growing investor scrutiny of the economics of large-scale AI infrastructure investments.
In early November 2026, Marvell announced an agreement to acquire Lumentum, a manufacturer of optical components and lasers, through an all-stock transaction valued at approximately $115 billion. Under the proposed terms, Marvell will issue 4.5 new shares for each Lumentum share. This would significantly increase Marvell’s outstanding share count, with existing Marvell shareholders retaining about 67% ownership of the combined entity.
The transaction's substantial equity component has emerged as a key source of investor concern. The anticipated dilution has raised questions about the acquisition's impact on per-share earnings, shareholder returns, and overall capital efficiency.
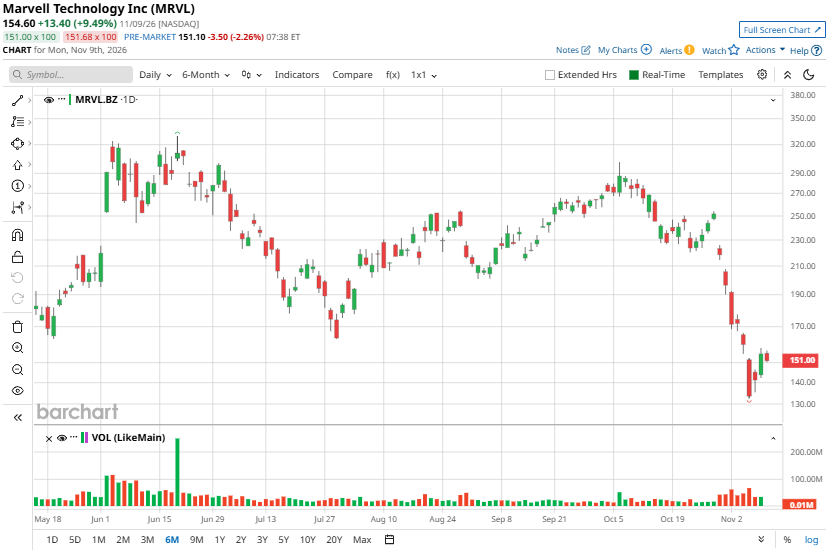
Moreover, Marvell's decline has also occurred against a broader deterioration in sentiment toward artificial intelligence (AI) and semiconductor stocks. Investors are questioning the long-term return on investment from the enormous capital commitments technology companies are making toward AI data centers. Concerns about the sustainability of infrastructure spending, the monetization of AI services, and potential regulatory or policy restrictions on data center development have added to near-term market uncertainty.
Nevertheless, the notable decline in Marvell's stock has made its risk-reward profile more compelling. While acquisition-related dilution and integration risks warrant caution, the selloff has also lowered MRVL’s valuation. This presents an attractive entry point, as Marvell is well-positioned to capitalize on demand for AI infrastructure and optical connectivity solutions.
In addition, analysts see substantial upside in MRVL stock, strengthening its investment case.
Marvell’s Growth Prospects Remain Solid
Marvell appears well-positioned to deliver strong growth through the end of the decade, supported by solid AI-driven demand and its expanding addressable market following the proposed acquisition.
The semiconductor company earlier raised its growth guidance and said that its revenue would hit $20 billion in fiscal 2028. The outlook represented a $2 billion increase from its previous target and approximately 67% year-over-year (YoY) growth. Looking further ahead, Marvell projected its revenue will expand at a CAGR of 55% to 60% through fiscal 2031.
Rising demand for AI accelerators, high-speed connectivity, networking solutions, and custom silicon is creating multiple opportunities for Marvell to expand its market presence. Management expects data center revenue to grow at a CAGR of approximately 65% between fiscal 2026 and fiscal 2031.
In addition, the proposed all-stock acquisition of Lumentum could further strengthen Marvell’s long-term growth prospects despite concerns around shareholder dilution and integration risk. The deal is expected to expand the company’s addressable market to $550 billion by calendar year 2030. By combining their technology platforms, Marvell and Lumentum could address a broader range of AI infrastructure needs, particularly in optical connectivity. This would give the combined company more opportunities to compete for a larger share of the growing market. Management also expects the acquisition to be accretive from the first year, with initial synergies and the potential for additional cost savings over time.
Strong revenue growth will translate into solid earnings. Marvell’s growing custom silicon business and improved operating efficiency are expected to support higher profitability over time. Management believes EPS could exceed $30 by fiscal 2031, suggesting considerable long-term earnings growth potential.
In the near term, analysts expect fiscal 2028 EPS to reach $6.08, up 99.3%, supporting its investment case.
Valuation Reset Makes MRVL Stock More Compelling
While shareholder dilution, integration challenges, and uncertainty surrounding AI infrastructure spending remain key risks, much of the near-term pessimism appears reflected in MRVL stock. Further, Marvell’s sharp correction appears overdone relative to its long-term growth potential, creating a more attractive valuation.
Strong AI-driven demand, expanding opportunities in custom silicon and optical connectivity, and the potential strategic benefits of the Lumentum acquisition support the company’s long-term growth outlook.
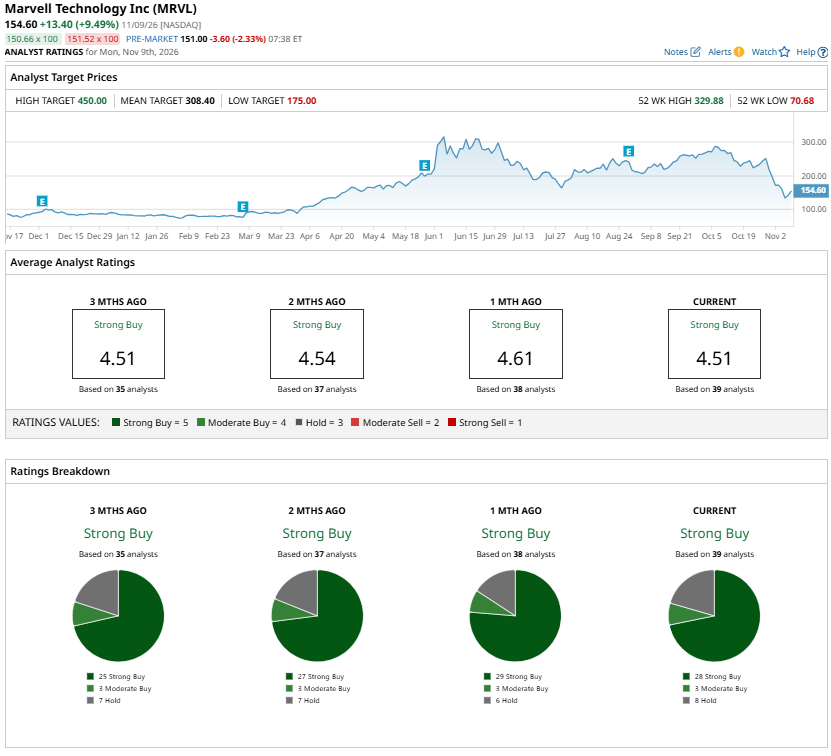
Moreover, analysts are bullish and maintain a “Strong Buy” consensus rating. At 43.9 times forward earnings, Marvell’s valuation appears reasonable relative to its growth potential. Furthermore, the average analyst price target of $308.40 suggests about 99% upside over the next 12 months from its Nov. 9 closing price of $154.60.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.