


EN
Qantas Shares In Focus As Non Stop Sydney London Flights Launch In 2027
- Qantas Airways has confirmed plans to operate non stop Sydney to London flights from October 2027 using A350-1000ULR aircraft capable of around 20 hour sectors with enlarged fuel tanks.
- The move pushes Qantas Airways deeper into ultra long haul flying, where fuel exposure, premium cabin demand and operational reliability directly shape earnings quality.
- We will now look at how Qantas Airways' ultra long haul Sydney to London plan fits into the existing investment narrative.
Compare Qantas Airways' ultra long haul bet with other carriers exposed to fuel risk and balance sheet strength by scanning our hand picked list of solid balance sheet and fundamentals (12 results).
Qantas Airways Investment Narrative Recap
To own Qantas Airways today, you need to believe the airline can translate its fleet renewal, dual brand model and loyalty program into steadier margins despite fuel volatility and high debt. The analyst consensus Narrative on Simply Wall St leans on improving efficiency and premium mix, with Qantas Loyalty adding more stable profit alongside the core flying business.
In the near term, fuel spend of about A$3.6b for 1H27 and entry into service costs for new aircraft remain the swing factors. The Sydney to London ultra long haul move looks important for positioning and product, but it does not obviously change the most immediate risks around fuel recovery, on time operations and keeping net debt within the existing A$5.5b to A$6.9b target band.
The Project Sunrise decision to run non stop Sydney to London using A350 1000ULR aircraft directly links to the catalyst list. Management already plans for next generation wide bodies such as the A350 to represent a large share of Qantas International capacity by FY31. The plan includes a higher share of premium seats and a focus on lowering unit costs.
This announcement sits alongside a heavier delivery phase of 29 aircraft in FY26 and ambitions to lift international EBIT margins from 4% by FY31. For you as a shareholder, the key question is whether Qantas Airways can execute Sunrise while handling higher training and entry into service costs, protecting reliability after past disruption issues and still converting the loyalty and ancillary revenue plans into cash that supports the balance sheet.
Qantas Airways' outlook projects A$29.1b revenue and A$2.1b earnings by 2029. This is based on an assumed 4.4% yearly revenue growth rate and an earnings increase of about A$800m from A$1.3b today.
Uncover why Qantas Airways' fair value indicates a 13% potential upside to its current price, which could narrow quickly.
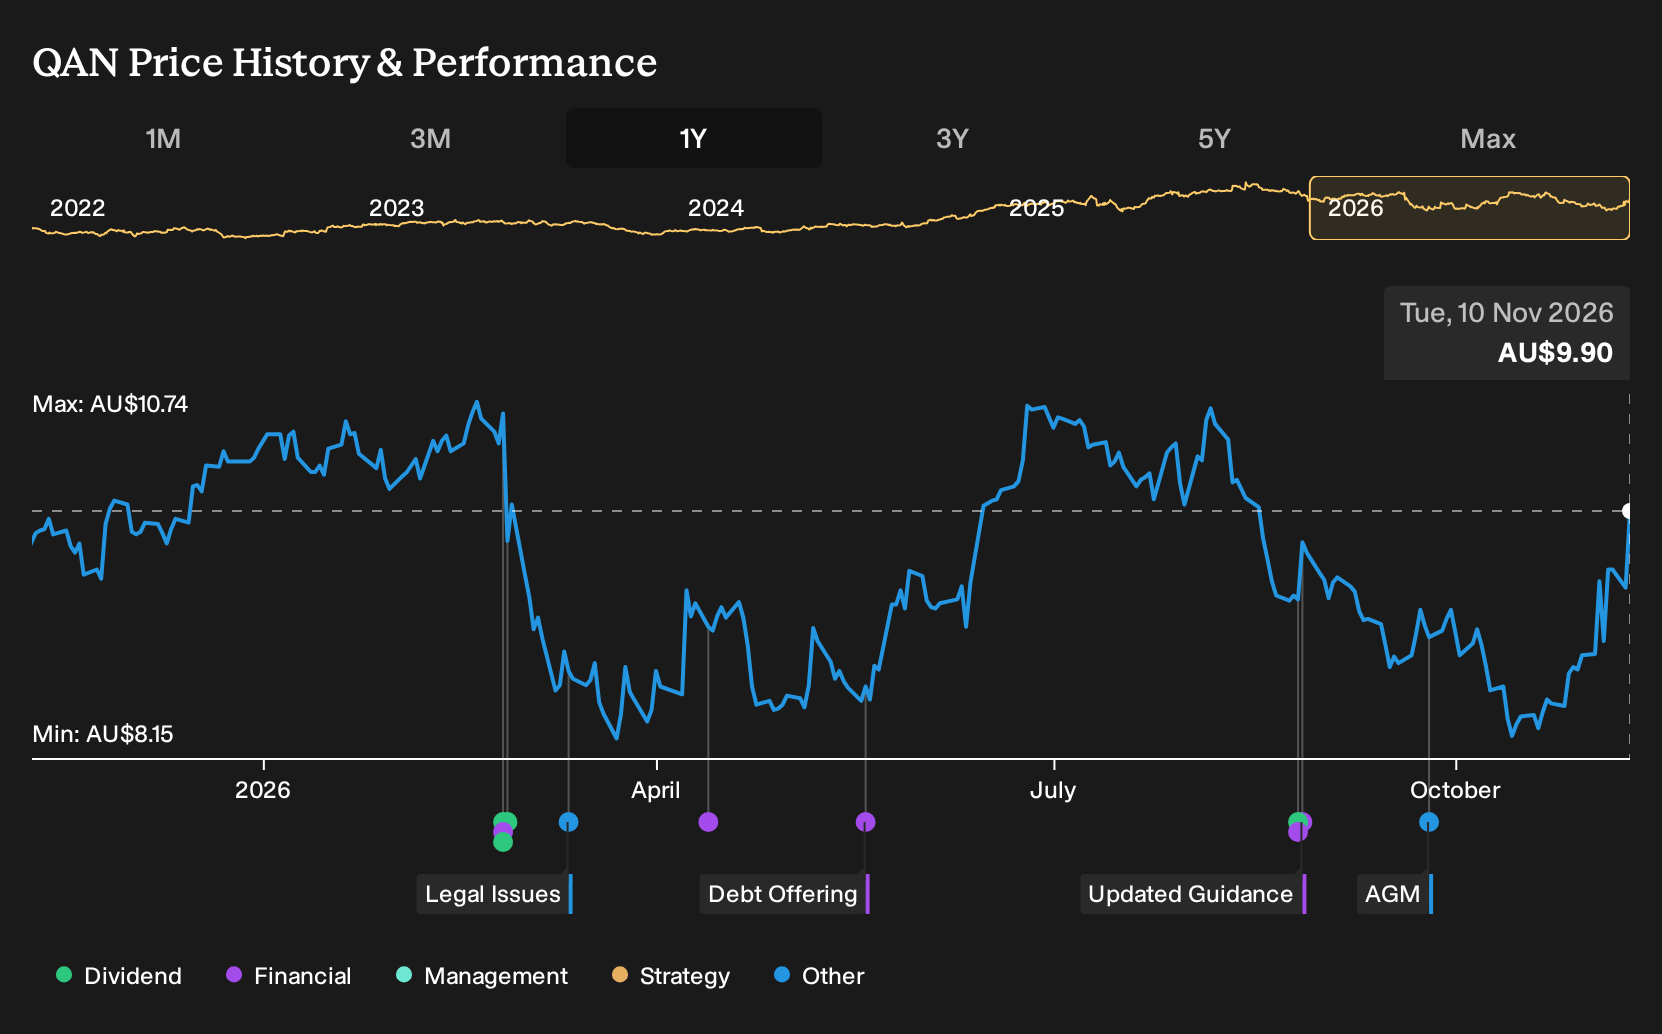
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly A$2.44 to A$11.16 per share, so retail views on Qantas Airways sit far apart. When this is set against rising fuel spend, ongoing fleet delivery commitments and Project Sunrise ambitions, there is a wide spread of potential outcomes. You should weigh these contrasting opinions and explore several alternative viewpoints before committing capital.
Explore 4 other Qantas Airways fair value estimates, including one that suggests potential upside of as much as 13% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Qantas Airways research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Qantas Airways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qantas Airways' overall financial health at a glance.
Looking For More Investment Ideas Beyond Qantas Airways?
If you want to cross check Qantas Airways against other listed businesses, the Simply Wall St Screener can help you quickly sort through hundreds of alternatives by balance sheet strength, income potential and quality indicators.
- For investors who want financial resilience front and center, start with companies screened for stronger fundamentals and conservative leverage via the list of solid balance sheet and fundamentals (12 results).
- If your focus is on quality at a reasonable price, compare Qantas Airways with a wider set of potentially underpriced opportunities by reviewing the 2 high quality undervalued stocks.
- Income focused investors can look beyond Qantas Airways and zero in on higher yielding payout opportunities by scanning the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com