


EN
Humana (HUM) Stock May Be Below Fair Value On Raised Outlooks
Humana has delivered a sharp 79.8% share price gain over the past year, which puts a spotlight squarely on whether that move is backed up by its earnings power today. With the stock around US$423.22, investors are asking if the recent news flow and expectations baked into the business are fully reflected in the income the insurer currently generates.
- The 79.8% return over the last 12 months raises the question of how much earnings strength the market is already pricing into Humana.
- Humana has raised its longer term adjusted earnings ambitions and is leaning into Medicare Advantage and CenterWell growth, which can shape how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Humana worth weighing. See what analysts think Humana's shares could be worth.
The issue now is whether Humana's current share price is justified by the earnings the company produces and what buyers today are paying on that basis.
If you want to stress test this same earnings question beyond Humana, run the numbers across solid balance sheet and fundamentals stocks screener (25 results).
Is Humana Still Cheap on Earnings?
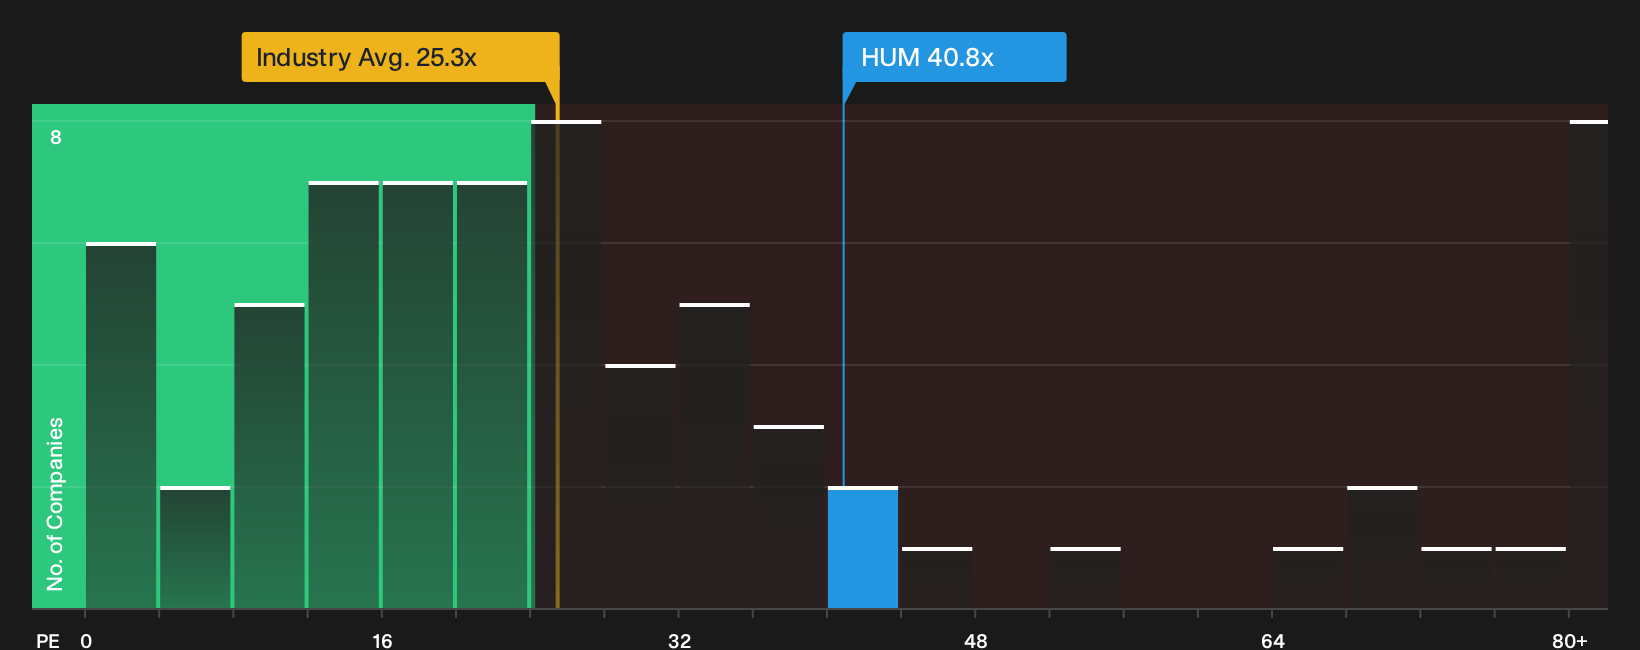
The P/E ratio fits Humana because earnings remain the key yardstick investors use for large, mature insurers. On this measure, the stock trades around 40.8x earnings, which is materially higher than both the wider Healthcare sector on 25.3x and the peer group near 24.7x. That kind of gap indicates the market is willing to pay a premium price for each dollar of profit that Humana currently reports.
A more tailored benchmark that blends Humana's growth profile, margins, size and risk points to a lower P/E as a reasonable anchor, so the current 40.8x level screens as overvalued on this framework. Because management has lifted its 2026 adjusted EPS guidance, the rich multiple already reflects a significant degree of optimism around execution and Medicare Advantage positioning. Investors evaluating the stock at this point are effectively being asked to pay a higher price for that story. Explore the numbers behind Humana's P/E valuation.
The Humana Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this P/E puzzle for Humana leaves off by spelling out which future paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each narrative ties its number to a clear view of how Humana's revenue mix, margin profile and risk picture might shift over time, so you can return to those assumptions as fresh information comes through on the Community page.
Bulls and bears on Humana are looking at the same Medicare Advantage engine and drawing very different conclusions about the risk and reward on offer.
Bull case: 29% undervalued
According to the bullish analyst Narrative on Simply Wall St, Humana’s margin repair story is central to the upside argument.
"The current valuation implies investors are not fully crediting Humana for its margin restoration targets, cost reductions, and capital structure actions…"
Discover why this Narrative puts Humana at 29% undervalued.
Bear case: 99% overvalued
According to yiannisz, an investor in the Simply Wall St Community, tighter Medicare oversight could weigh heavily on Humana.
"Across the industry, regulators are sharpening their focus on how health plans document risk adjustment data and apply prior authorization standards…"
Explore why this Narrative puts Humana at 99% overvalued.
One more Humana angle worth checking before you move on
Before closing the file on Humana, it is worth asking who is steering the insurer, how their rewards line up with your interests, and what that mix really looks like in practice. See who runs Humana and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com