


EN
Kodiak Gas Services (KGS) Stock May Be Overvalued On Dividend Raise News
Kodiak Gas Services has been a strong performer over the past few years, which naturally raises a question for anyone looking at the stock today. Is the current share price still grounded in the company’s earnings power, or has the recent run taken it beyond what its profits can comfortably support?
- Over the past 3 years the stock has returned 186.7%, which puts a lot of weight on whether Kodiak Gas Services' current earnings truly justify that kind of move.
- A higher regular dividend and an extended share buyback plan signal that management sees room to return more cash to shareholders, which can matter for how investors value its earnings stream.
- The analysts covering Kodiak Gas Services have run their own numbers. See what analysts think Kodiak Gas Services's shares could be worth.
The issue now is whether Kodiak Gas Services' current market price fairly reflects what its earnings suggest the stock should be worth.
If you are weighing Kodiak Gas Services against other income ideas, it can help to see how a wider group of dividend payers stack up using our 6 dividend fortresses
Does Kodiak Gas Services Look Pricey on Earnings?
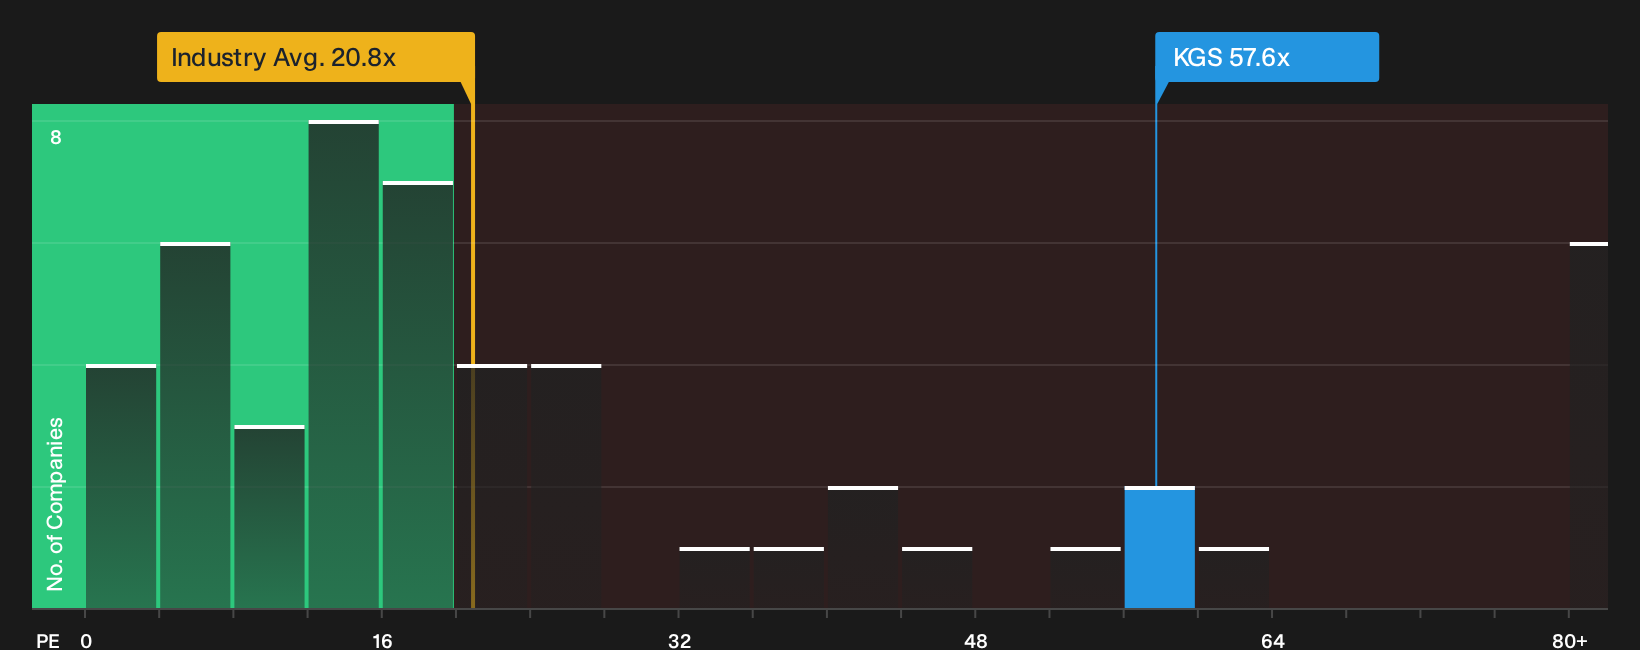
The P/E ratio works well for Kodiak Gas Services because earnings are a key anchor for how investors value its cash generation. On this measure, the stock trades on about 57.6x, compared with an Energy Services sector average of roughly 20.8x and a peer group closer to 23.4x. That is a steep premium to both the broader industry and more direct comparables.
The fair-value model suggests a lower P/E would better match Kodiak Gas Services' profit profile, so the current multiple screens as overvalued against what its growth, margins and risk mix might usually justify. Because management has raised the dividend and extended the buyback program off the back of strong reported results, the valuation already incorporates a lot of confidence that this performance is both solid and durable. For a new investor, the question is whether that optimism is fully reflected in the 57.6x tag or still leaves room for upside on this metric. Explore the numbers behind Kodiak Gas Services's P/E valuation.
The Kodiak Gas Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Kodiak Gas Services' rich P/E debate leaves off by spelling out which earnings, margin and growth paths would need to play out for the current share price to look either conservative or stretched. Each scenario ties its implied value to a clear view on how Kodiak Gas Services' growth, profitability and risk profile could evolve next, giving you something concrete to compare against as fresh results and new data emerge on the Community page.
One of the top narratives on Kodiak Gas Services: 44% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation is described as implying that the share price does not fully reflect Kodiak’s plan to grow its compression fleet toward at least 5.2 million horsepower and build a roughly 2 GW power fleet..."
Discover why this Narrative puts Kodiak Gas Services at 44% undervalued.
One more Kodiak Gas Services check that belongs next to the P/E debate
Price tags and profit multiples only tell part of the story, because the people directing Kodiak Gas Services and the way their rewards are structured can heavily influence how that story unfolds. See who runs Kodiak Gas Services and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com