


EN
Zscaler (ZS) Draws AI Security Attention, Is A 20% Undervaluation Case Convincing?
Zscaler (ZS) is back in focus after comments from former Facebook security chief Alex Stamos, who warned that AI is driving cyberattack costs toward zero while keeping digital defense expensive.
Against that backdrop, Zscaler’s recent trading tells a more cautious story. The share price is US$199.04, with the 7 day share price return down 11.1% and the 30 day share price return down 14.8%, even though the 90 day share price return is up 11.5%.
Spot opportunities across AI security by scanning the hand picked 42 profitable AI stocks that aren't just burning cash that pair real earnings with exposure to the same cyber themes driving attention to Zscaler.Bulls point to Zscaler’s role in AI era security and recent earnings strength, while bears focus on the share price slide and ongoing losses. Which story lines up better with what investors are paying for today?
Most Popular Narrative: 20% Undervalued
The narrative fair value for Zscaler sits at $249.97 compared with the last close at $199.04, which frames a sizeable gap that investors are trying to explain. According to Andrei_Niculescu, an investor in the Simply Wall St Community who wrote the narrative, the real debate is about what Zscaler becomes in the AI era rather than what it is today.
The market still largely values Zscaler as a Zero Trust security company. I believe the more important question is whether it becomes a foundational platform for securing enterprise AI.
Fiscal 2026 results showed accelerating ARR growth, record large-customer activity, growing adoption of non-seat-based products, and early evidence that Security for AI is resonating with customers. Security for AI bookings grew more than 50% quarter-over-quarter, while 70% of those wins included Data Security products, suggesting meaningful platform expansion opportunities.
See why 39 investors see Zscaler as 20% undervalued.
Result: Fair Value of $249.97 (UNDERVALUED)
Still, if AI security demand settles at the slower end of management guidance, or if larger platforms bundle similar tools aggressively, Zscaler’s premium narrative could lose momentum.
Find out about the key risks to this Zscaler narrative.
Another View: Zscaler Looks Pricey On Sales
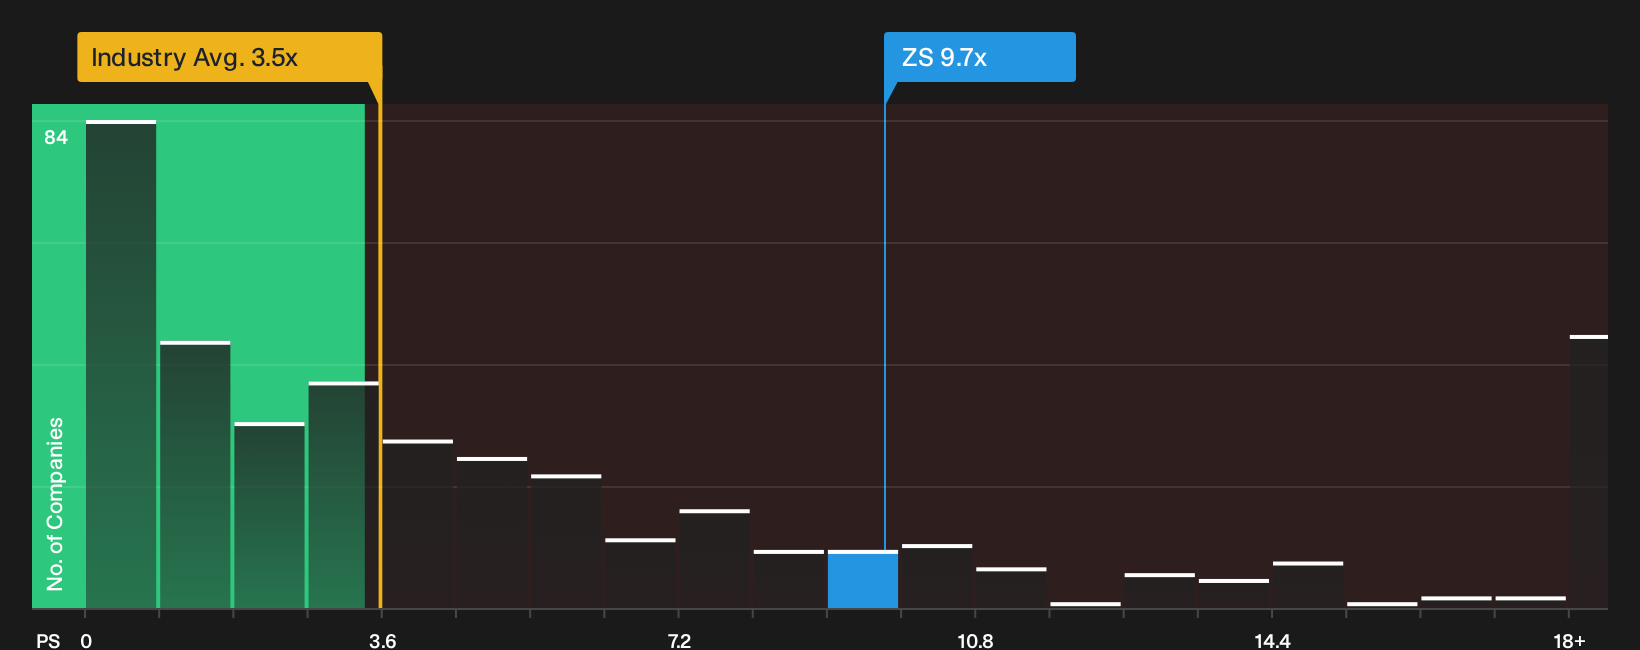
The SWS DCF model paints Zscaler as undervalued, yet the market’s simple yardstick tells a different story. On a P/S basis of 9.7x, Zscaler trades richer than the US Software industry on 3.5x, its peer group on 8.8x, and even the 9.1x fair ratio. Is that premium cushioning risk or adding to it for holders?
See what the numbers say about this price in more detail, then weigh it against your own expectations for AI security demand over the coming years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about whether Zscaler’s current price fits the story you have in mind? Act quickly, review the full picture, and weigh the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Zscaler?
If Zscaler’s story has you thinking harder about where your money works best, now is the moment to widen the lens with other focused shortlists.
- Target resilient performers by checking the 30 resilient stocks with low risk scores, which aims to keep portfolio swings in check while still leaving room for upside.
- Hunt for mispriced opportunities across the market through the 19 high quality undiscovered gems, which pairs strong fundamentals with limited attention from the crowd.
- Build a sturdier income base by reviewing the 6 dividend fortresses, which combines higher yields with an emphasis on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com