


EN
Basilea Pharmaceutica (SWX:BSLN) Could Be 28% Undervalued As Cresemba News Lifts Guidance
Why the Cresemba Milestone and Guidance Shift Matter for Basilea Pharmaceutica
Basilea Pharmaceutica (SWX:BSLN) drew investor attention after a US$37.5 million milestone from Cresemba sales in Europe coincided with raised 2026 revenue and operating profit guidance announced in late October.
Recent trading shows Basilea Pharmaceutica shares give mixed signals in the short term, with the 1 day and 7 day share price returns slightly down, while the 30 day and 90 day gains, plus a 1 year total shareholder return of 54.45%, point to momentum that has been building over time as investors react to the Cresemba milestone and upgraded 2026 guidance.
Look beyond Basilea Pharmaceutica and see how other infection treatment players are moving by reviewing our curated list of 127 healthcare AI stocks positioned at the crossroads of healthcare and advanced data science.
For Basilea Pharmaceutica, the question now is whether the recent jump in expectations simply rewires sentiment or mirrors a sturdier earnings base. The valuation picture will show how much of this is already in the price.
Most Popular Narrative: 28% Undervalued
On the analyst consensus Narrative on Simply Wall St, Basilea Pharmaceutica screens as undervalued, with a fair value of CHF98.63 set against a last close of CHF71.20. That view leans heavily on how Cresemba, Zevtera and the late stage pipeline reshape earnings power once current guidance and funding lines are factored in.
The flexible, partnership-based commercialization model enables Basilea to rapidly scale new assets, capture global stewardship initiatives targeting drug-resistant "superbug" threats, and maintain disciplined cost structure, supporting margin expansion and stronger long-term free cash flow and earnings.
See why 5 investors see Basilea Pharmaceutica as 28% undervalued.
Result: Fair Value of CHF98.63 (UNDERVALUED)
Still, the loss of Cresemba exclusivity after 2027 and heavy dependence on a handful of late stage assets leave the Basilea Pharmaceutica story exposed if execution slips.
Find out about the key risks to this Basilea Pharmaceutica narrative.
Another Take On Basilea Pharmaceutica’s Valuation
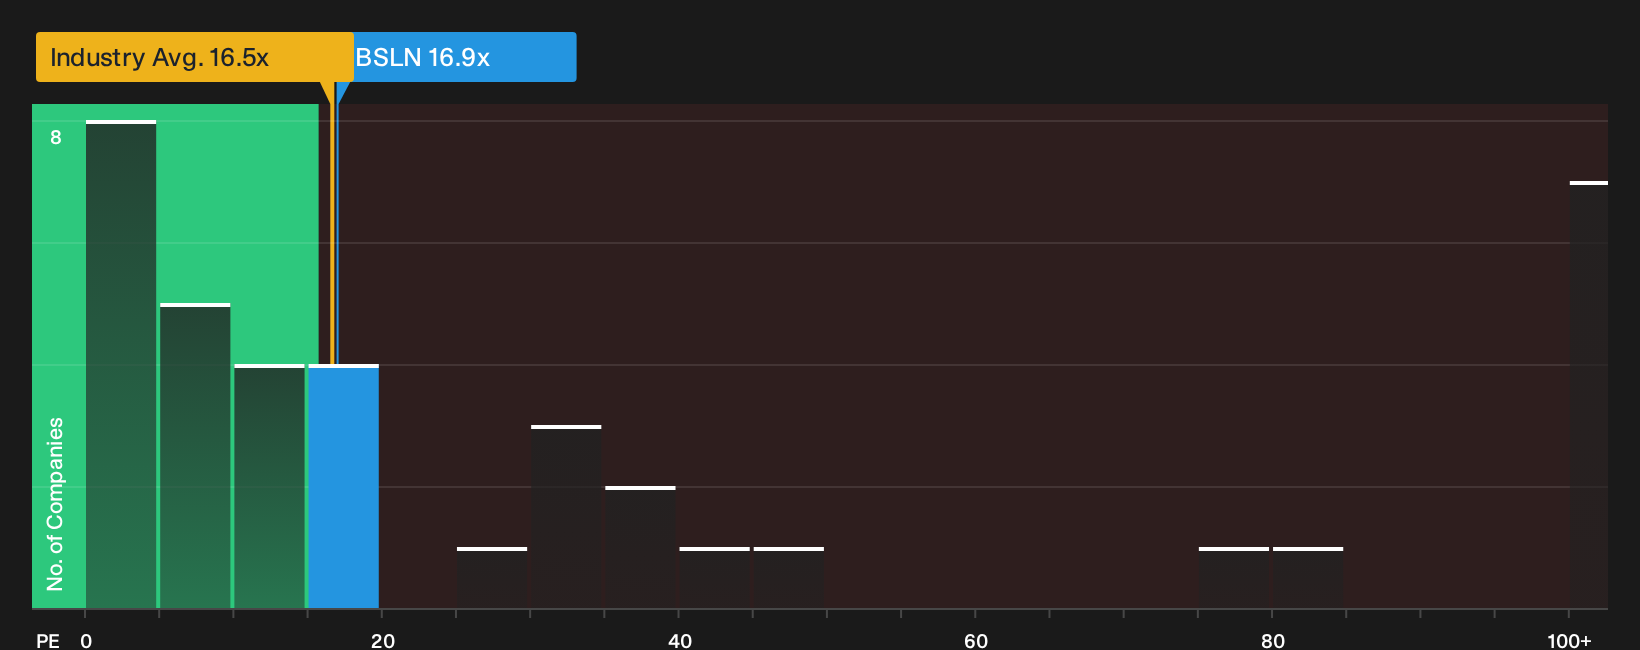
Analysts see Basilea Pharmaceutica as undervalued on their fair value of CHF98.63, yet the current P/E of 16.9x tells a more cautious story. It sits slightly above the European biotechs average of 16.5x, but below a fair ratio of 20.1x, which suggests both potential for a rerating and the risk that expectations are already reflected in the price. How comfortable are you with paying close to the sector average when the investment case relies on a few key drugs?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this, you can probably sense that Basilea Pharmaceutica splits opinion, with real upside angles but also clear pressure points that investors are weighing. If you want to move fast and build your own conviction from the data instead of relying on headlines, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Basilea Pharmaceutica?
If Basilea Pharmaceutica has you thinking more broadly about opportunity and risk, do not stop at a single ticker. Use data driven shortlists to pressure test your next move and avoid leaving potential ideas undiscovered.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (195 results). This can help anchor the more volatile parts of your portfolio.
- Hunt for quality at sensible prices with a focused 198 high quality undervalued stocks that filters for strong businesses where expectations are not already fully priced in.
- Stack potential cash returns on top of capital gains by reviewing a hand picked 217 dividend fortresses, designed for investors who want income working alongside growth.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com