


EN
Did Equity Raise Just Shift CVR Energy (CVI) Stock Investment Narrative?
- CVR Energy recently reported third quarter 2026 sales of US$3,281 million and net income of US$570 million, along with higher refining throughput and production compared with the same period a year earlier.
- The business has reshaped its capital structure with follow-on equity offerings exceeding US$1.2 billion while still declaring a recurring US$0.10 per share cash dividend for the third quarter of 2026.
- We will now examine how CVR Energy's investment narrative is affected by this large equity raise and expanded funding flexibility.
Scan beyond CVR Energy and size up other refiner driven opportunities with the curated list of 33 high quality undervalued stocks, which combines cash flow strength with balance sheet resilience.
CVR Energy Investment Narrative Recap
For an investor to stay with CVR Energy, the crux is simple. You need to be comfortable that high utilization in refining and fertilizer can be maintained while Renewable Fuel Standard costs remain heavy but manageable, as outlined in the analyst consensus Narrative on Simply Wall St. The recent third quarter figures and fourth quarter throughput guidance of 210,000 to 225,000 bpd keep that utilization story front and center.
The most important short term swing factor is refinery uptime and execution on that throughput range. The main near term risk remains unplanned outages or operational issues that would push utilization lower while RIN expenses stay elevated, which could pressure margins even if product demand stays supportive.
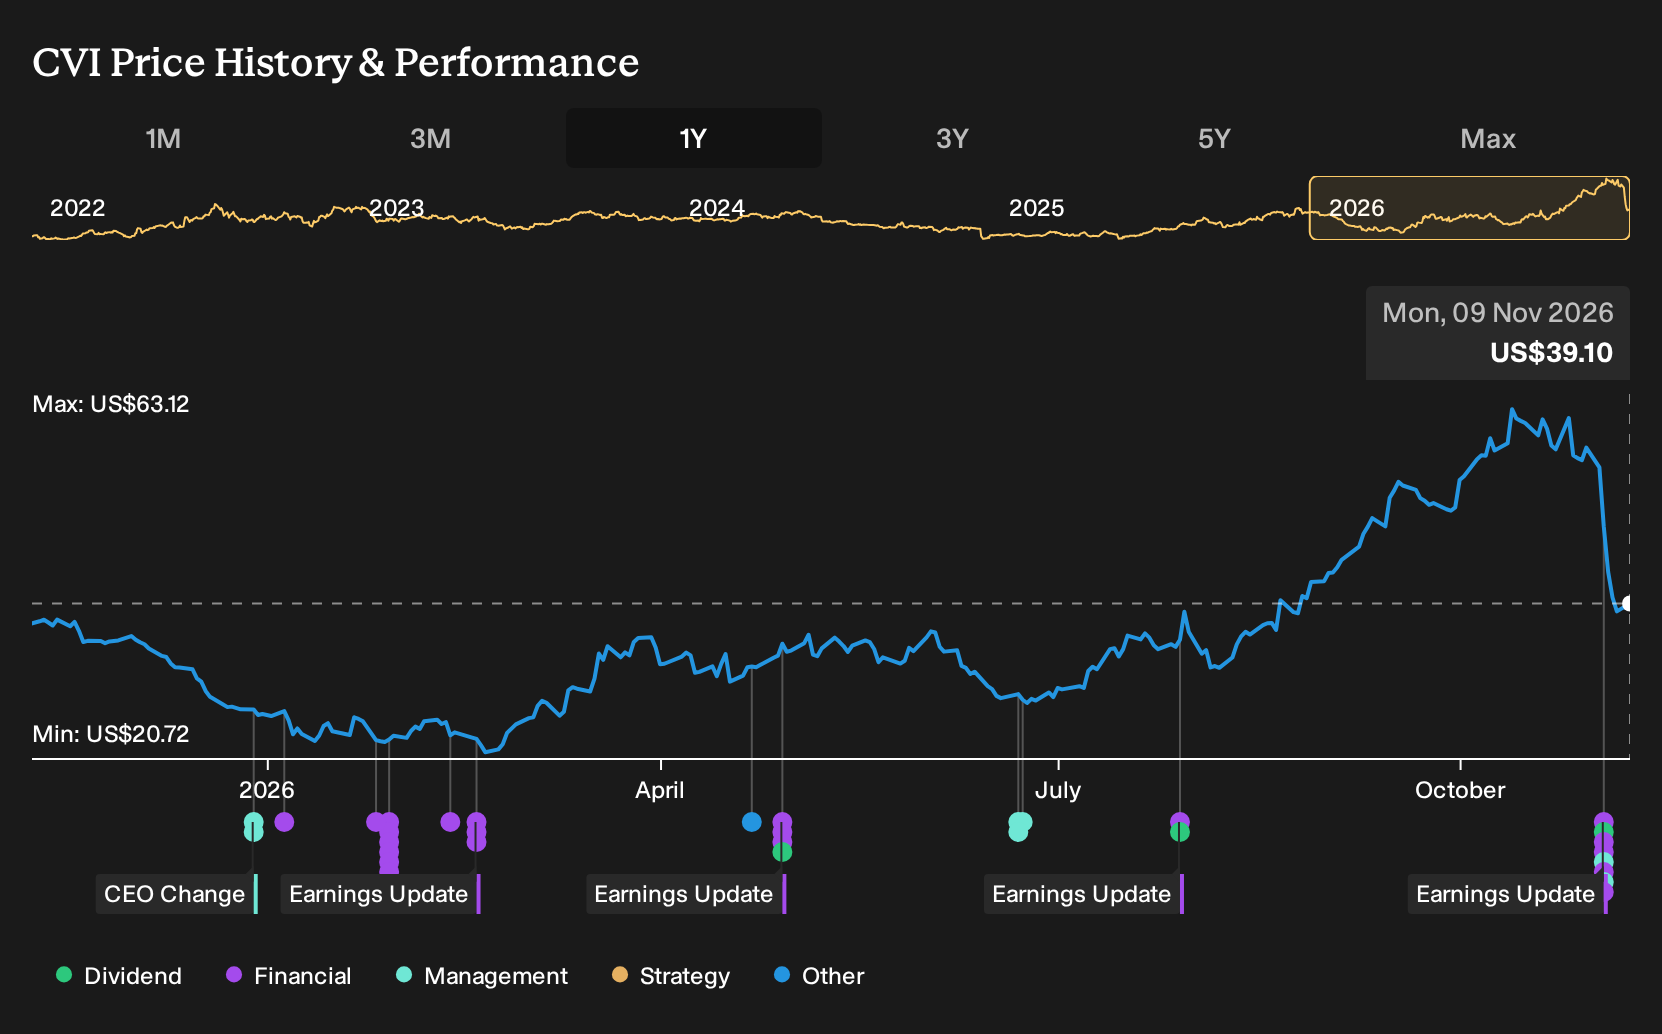
The fresh follow on equity offerings totaling more than US$1.2b look most relevant right now. They change how CVR Energy can fund refinery and fertilizer projects that underpin the utilization narrative. They also give management more room if RFS compliance costs stay high or working capital needs rise with higher runs.
Extra equity capital can help execution on any throughput or capacity plans. Yet it also adds dilution on a per share basis and interacts with a share price that already trades on a 16.0x P/E against lower peer averages. For you, the key question is whether improved funding flexibility offsets that dilution risk given the current mix of catalysts and RFS headwinds.
Analysts currently model CVR Energy reaching about US$7.2b in revenue and US$522.0 million in earnings by 2029, based on a 5.2% yearly decline in revenue and an earnings increase of roughly US$453.0 million from US$69.0 million today.
Uncover how CVR Energy's fair value indicates a 23% potential upside to its current price. This could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view on CVR Energy leans heavily on the more optimistic earnings path. Bullish analysts were penciling in about US$8.0b of revenue and US$446.2 million of earnings by 2029, compared with the baseline US$7.2b and US$522.0 million mix. Your take on this fresh equity raise and throughput guidance could shift which story appears more realistic.
Explore 5 other CVR Energy fair value estimates, including one that suggests as much as 197% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CVR Energy research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for CVR Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CVR Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond CVR Energy?
Once you have formed a view on CVR Energy, it can help to widen the lens and compare that thesis with opportunities across different styles and risk levels using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, scan for high-yield opportunities with the 6 dividend fortresses.
- For a focus on resilience and balance sheet strength, filter for companies that look better equipped for a wide range of scenarios using the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for potential outliers before the crowd catches on, sort through companies with strong fundamentals using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com