


EN
Is Earnings Surge Altering The Investment Case For Grupo Simec Stock (SIM)?
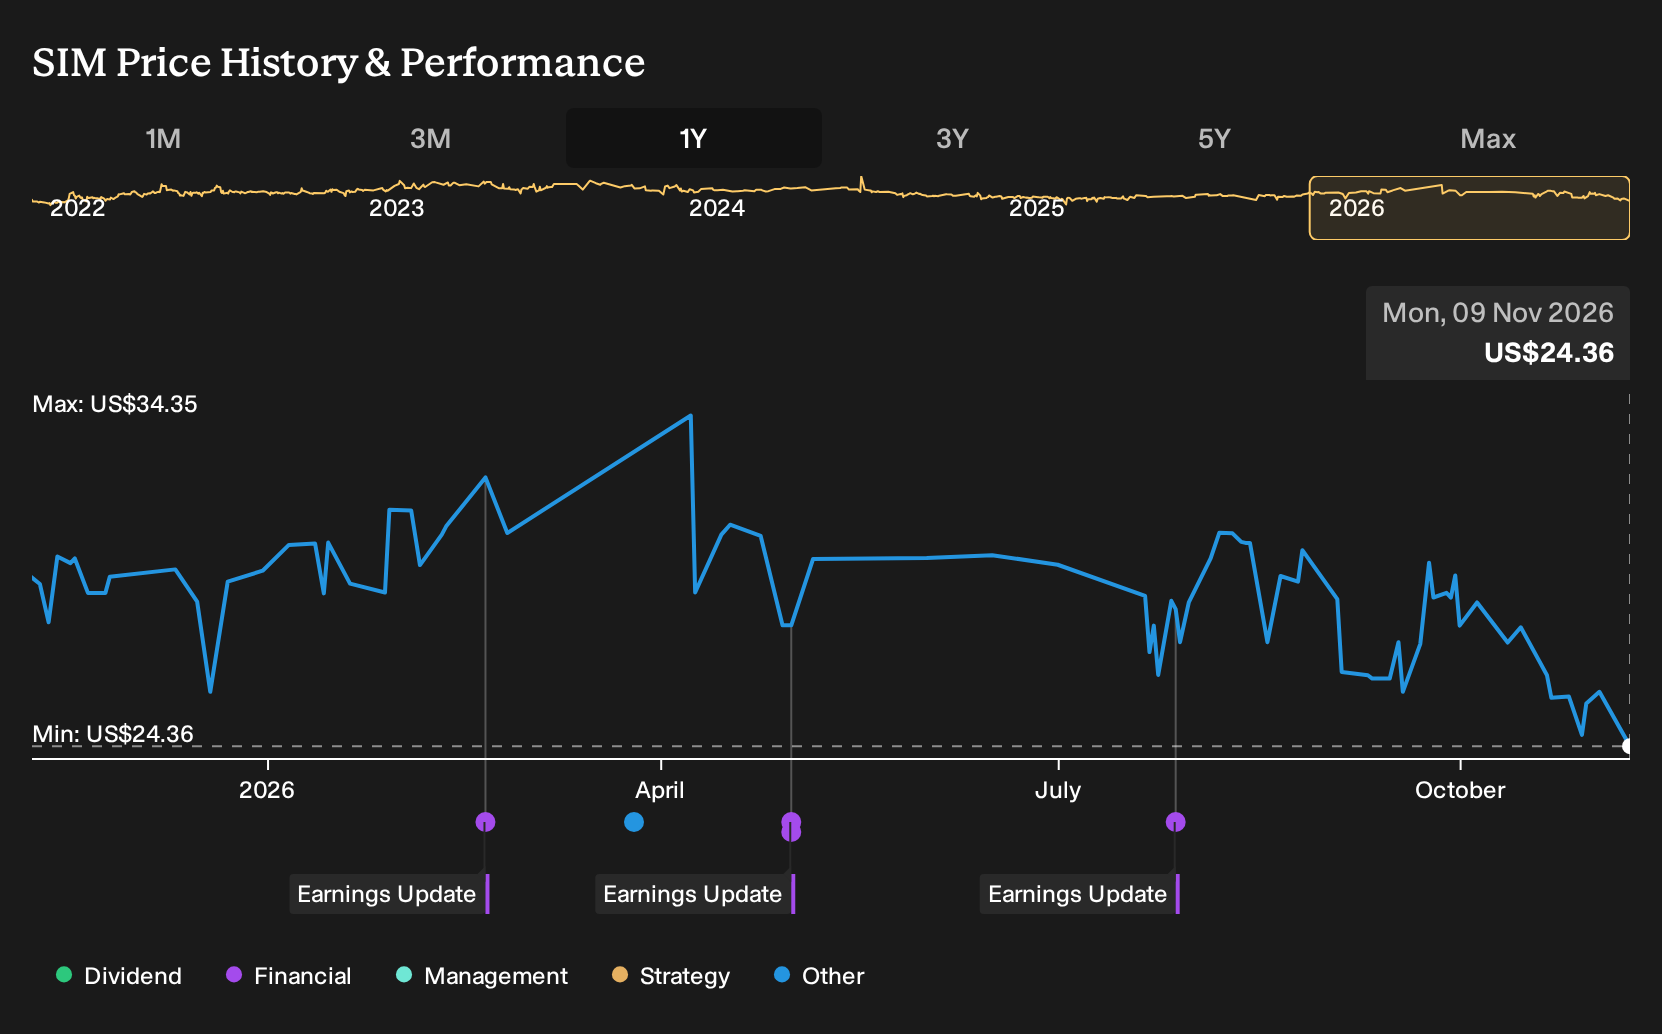
- Grupo Simec reported roughly 10% sales growth and a very large increase in net income for the first nine months of 2026, prompting investors to reassess how current earnings relate to the company’s overall valuation.
- The business now trades on a P/E that is higher than sector peers. This raises questions about how much of this earnings strength is already reflected in the current share price.
- We will look at how Grupo Simec's investment narrative is influenced by the recent 10% sales growth and sharp net income jump.
Compare Grupo Simec's recent earnings swing with peers that also screen for stronger balance sheets and pricing power by scanning our curated list of 33 high quality undervalued stocks.
What Is Grupo Simec. de's Investment Narrative?
To own Grupo Simec. de, you need to be comfortable with a heavy industrial story where pricing, volumes and capital spending all matter more than headlines. The recent 10% sales growth and sharp net income jump for the first nine months of 2026 suggest that current demand and pricing have been supportive, at least over this stretch. Short term, the key question is whether mills can keep running efficiently at these levels without requiring a step up in investment that eats into that earnings strength.
There is also a tension between the latest earnings swing and a longer track record that includes declining profit over the past 5 years and softer margins than a year ago. A higher P/E relative to the US Metals and Mining industry means the market is already paying up for this recovery, so any wobble in orders or input costs could matter more than usual. Execution on plant utilization and cost control probably does more work in this story than new capacity or big expansion plans right now.
Even so, anyone looking at Grupo Simec. de today still has to weigh one stubborn issue that sits in the background of all this.
There's only one way to know the right time to buy, sell or hold Grupo Simec. de. Head to Simply Wall St's company report for the latest analysis of Grupo Simec. de's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Grupo Simec. de research is our analysis highlighting 2 important warning signs that could impact your investment decision.
- See our latest analysis for Grupo Simec. de. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grupo Simec. de's overall financial health at a glance.
Looking For More Investment Ideas Beyond Grupo Simec. de?
If you want to stress test your view on Grupo Simec. de, it can help to compare it with other companies that have very different balance sheets, income profiles and risk levels. The Simply Wall St Screener gives you ready made starting points across a wide range of approaches so you can quickly see what else might deserve a place on your watchlist.
- If you care most about resilient businesses that aim to limit downside, start with 30 resilient stocks with low risk scores which have historically scored well on risk factors.
- For investors who want companies with cleaner finances and less leverage risk, use the list of solid balance sheet and fundamentals (25 results) to compare against your current holdings.
- If you enjoy hunting for ideas before they are widely followed, the 19 high quality undiscovered gems can highlight lesser known stocks with stronger underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com