


EN
3 UK Dividend Stocks For Defensive Income Including GSK, Diageo And Tesco
With the Bank of England hinting that stubborn inflation could be “crystallising” and more rate hikes are firmly on the table, the usual playbook for UK shares looks less reliable. Income hunters and cautious investors are again paying close attention to larger, dividend-paying stocks that may cope better with higher borrowing costs and slower growth. This article reveals three UK large caps from our defensive screener that appear well placed against this backdrop and explains how the latest policy signals might matter for each one.
The three UK large caps highlighted below are only a starter set from this idea, and the full screen surfaced another 25 companies with similarly resilient income stories that are not covered in this article.
If you want to identify, compare and analyze those additional candidates in one place, head straight to the UK Defensive, Dividend-Paying Large Caps screener.
GSK (LSE:GSK)
Overview: GSK is a global healthcare group that develops and sells vaccines and prescription medicines across infectious disease, HIV, oncology and respiratory care.
Market Cap: £76.35b
GSK fits the UK Defensive, Dividend-Paying Large Caps theme as a healthcare heavyweight. Its medicines and vaccines tend to serve ongoing patient needs regardless of the Bank of England’s next move. The analyst consensus Narrative on Simply Wall St explains why its pipeline focus matters for long term cash flows.
"GSK is pushing deeper into long acting HIV injectables, with Cabenuva and Apretude driving a larger share of HIV division growth and backed by data showing Cabenuva superiority to daily oral therapy in high risk and viremic patients. This can support future HIV revenue and earnings durability as more patients transition off oral regimens."
What happens to GSK’s income appeal if one unseen pressure on future treatment mix and pricing breaks differently from current expectations?
That pressure point is exactly where the full narrative for GSK shows how GSK’s HIV franchise, cash flows and risk trade offs could be decoupling from market expectations.

Diageo (LSE:DGE)
Overview: Diageo is a London based global drinks group that produces and sells branded spirits, beer, and ready to drink beverages worldwide.
Operations: Diageo generates most of its $19.6b business revenue from North America at $7.2b, Europe at $5.1b and Asia Pacific at $3.3b.
Market Cap: £41.82b
Diageo fits the UK Defensive, Dividend Paying Large Caps theme as a consumer staples heavyweight. The analyst consensus Narrative on Simply Wall St focuses on how its premium brands, pricing decisions and cost discipline could underpin income resilience even if the Bank of England keeps rates higher for longer.
"Diageo is rolling out a company wide simplification of its operating model, including a $1.2b restructuring, targeted overheads at 10.5% of sales and about $1b of annual savings. This program is designed to support higher operating margins and free cash flow once it is fully embedded."
What happens to Diageo’s dividend appeal if one unresolved cost pressure or consumer shift erodes the cushion that plan is built on?
If that cushion proves thinner than it looks, the full narrative for Diageo lays out where Diageo’s plan could still accelerate, stall or quietly mask deeper risks.

Tesco (LSE:TSCO)
Overview: Tesco is a large UK based grocery and wholesale retailer with supermarkets, convenience stores, online shopping, and related consumer services.
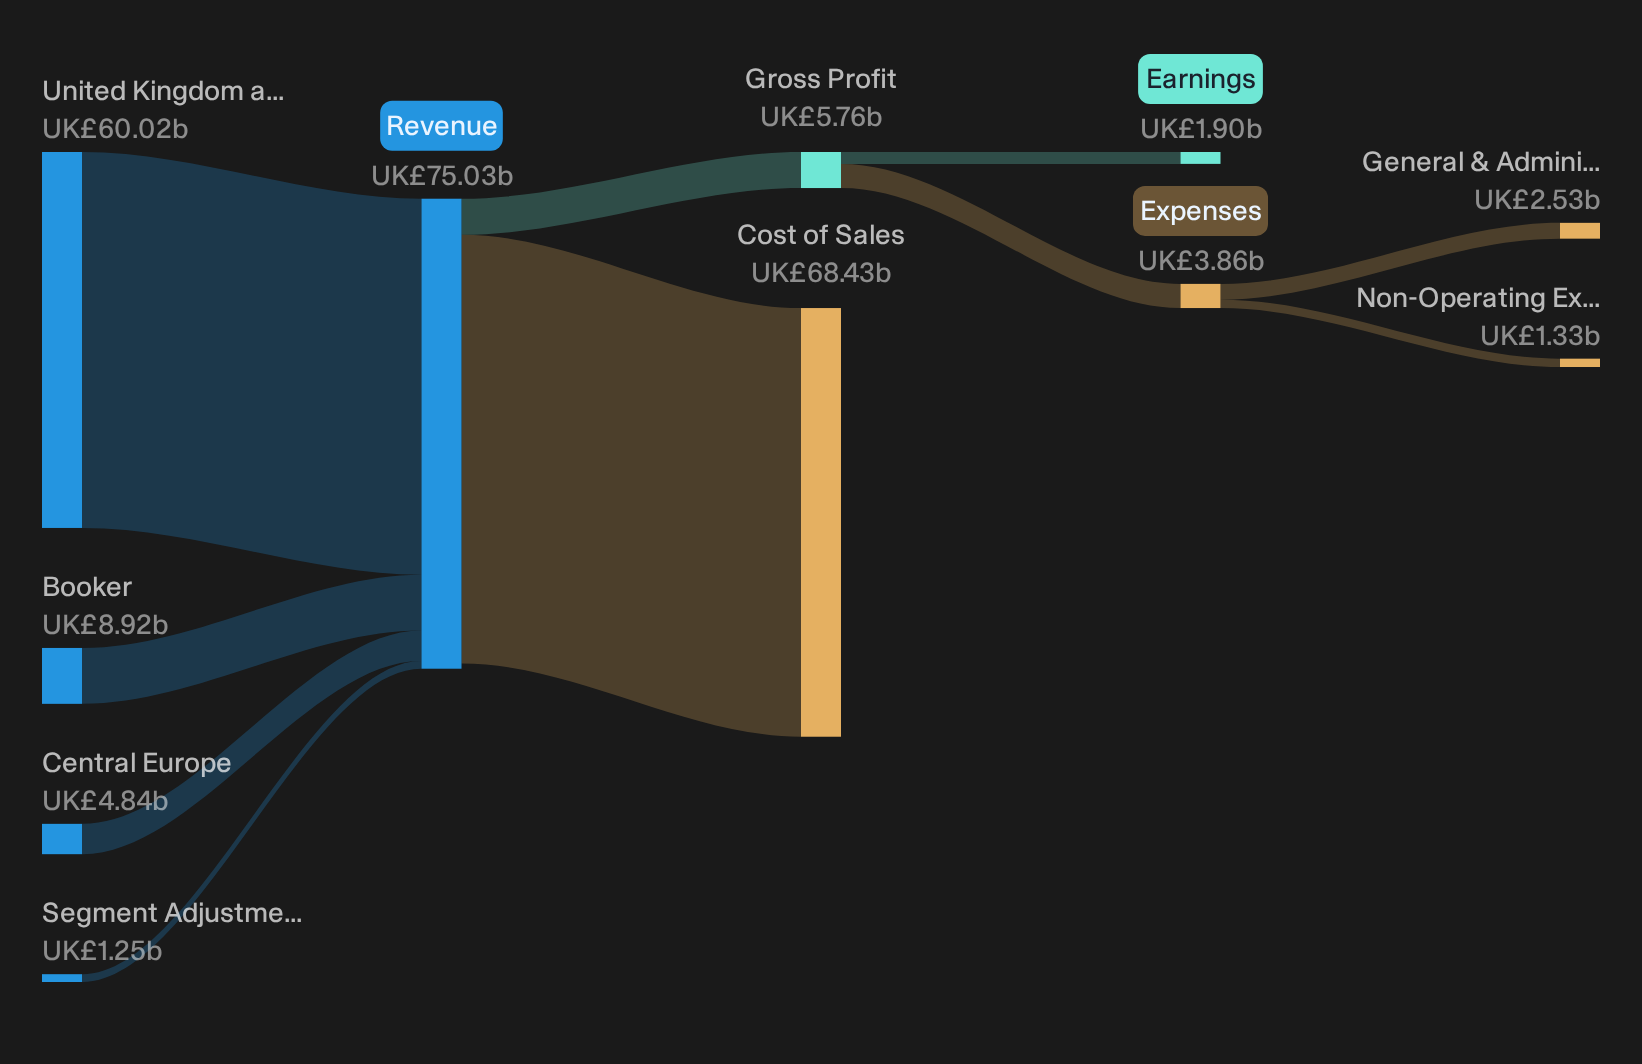
Operations: Tesco generates around £60b of revenue from the UK and Republic of Ireland, with £8.9b from Booker wholesale and £4.8b from Central Europe.
Market Cap: £34.36b
Tesco brings a classic consumer staple angle to this defensive, dividend focused screen. The analyst consensus Narrative on Simply Wall St highlights how its cash generation and cost discipline shape that appeal when UK rates stay higher for longer.
"Sustained efforts in streamlining operations and achieving cost savings under the Save to Invest program, which has delivered more than £2.7b of cumulative savings with a further £500m targeted in 2026/27, are likely to support net margins by offsetting operating cost inflation."
What happens to Tesco’s income story if a single unseen pressure on UK grocery pricing or cost inflation breaks away from those expectations?
That pressure point is exactly where the full narrative for Tesco shows whether Tesco’s cost wins are quietly masking risk or setting up a stronger, more resilient income story ahead.
Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to flying under the radar in weeks. Scan curated ideas before momentum gets fully caught by the crowd and act now.
- Spot potential cash machines early by running the 6 dividend fortresses before yields get compressed and headline hunters crowd into the same payout stories.
- Track early movers in automation by tapping the 92 robotics and automation stocks while these operators are still priced as niche plays, not mainstream winners.
- Position ahead of infrastructure momentum by using the 42 power grid technology and infrastructure stocks while the theme is still treated as specialist and not yet fully priced in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com