


EN
How Investors Are Reacting To Shikoku Electric Power Shares After Guidance Lift
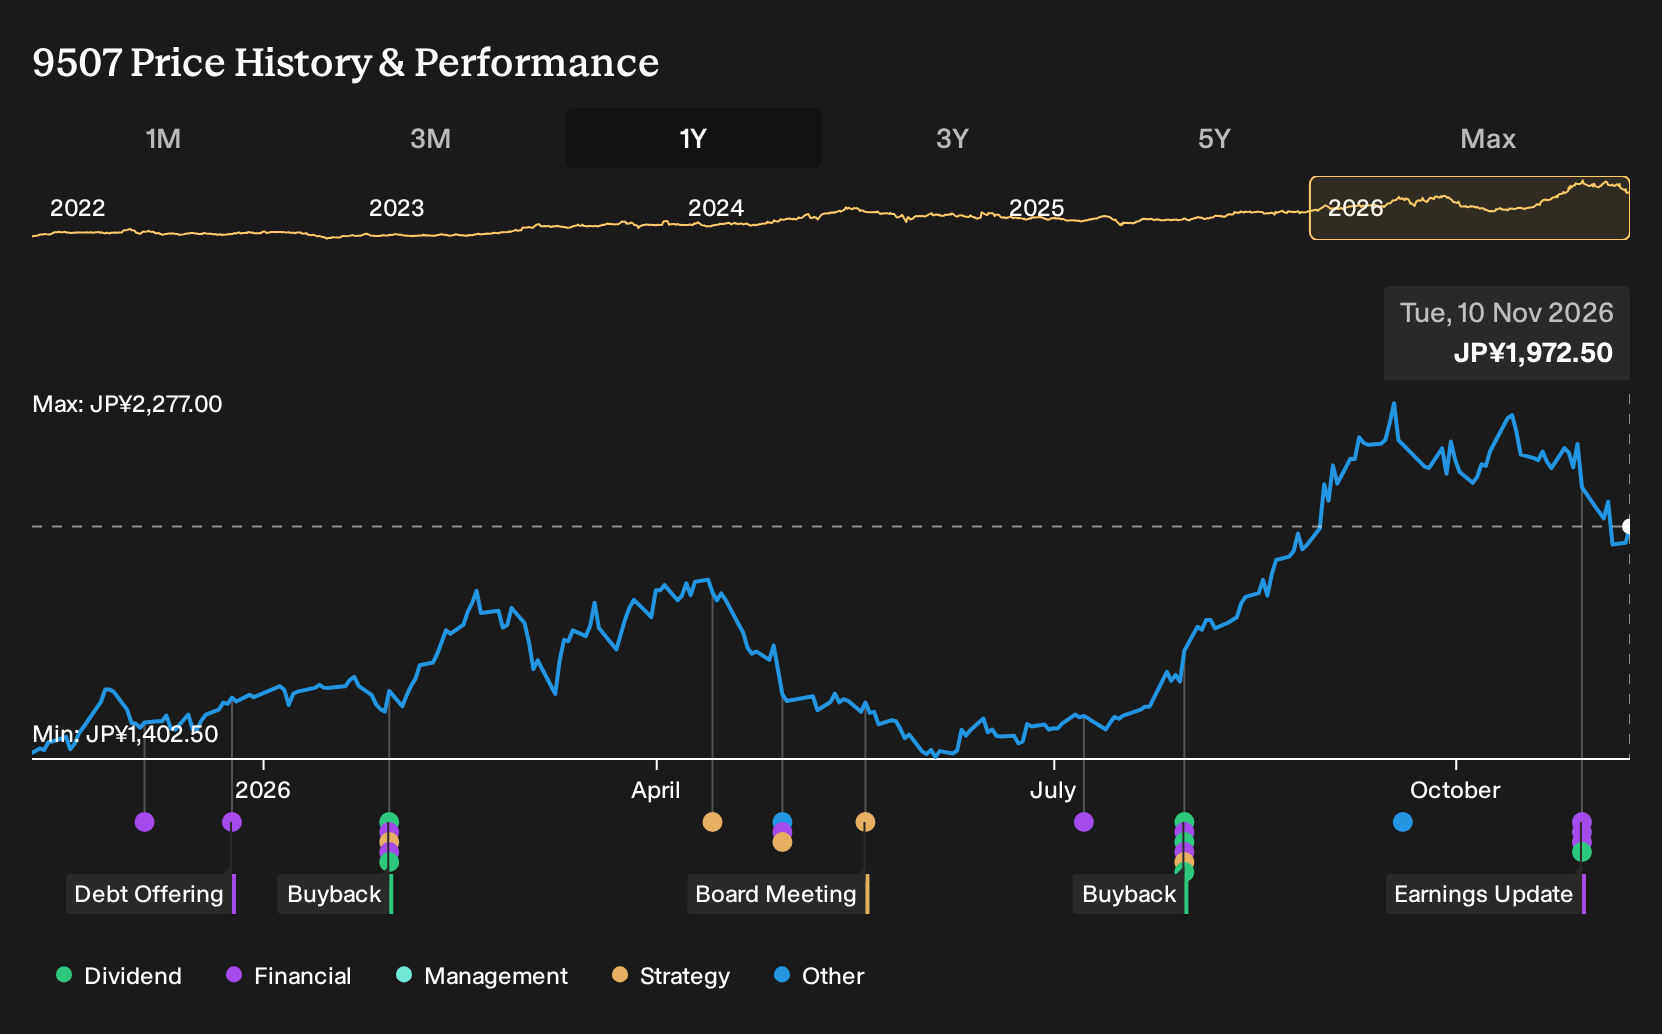
- On October 30, 2026, Shikoku Electric Power Company revised its fiscal 2027 guidance, lowering non consolidated forecasts while raising its consolidated profit outlook, and reported half year revenue of JPY 419,102 million with net income of JPY 40,656 million.
- The utility also increased its second quarter dividend to JPY 27.50 per share and cited higher wheeling charge income linked to prices and interest rates as a key earnings driver.
- We examine how Shikoku Electric Power Company's investment narrative is affected by profit guidance driven by higher wheeling charges.
Scan how Shikoku Electric Power Company's updated guidance compares with other regulated utilities by running the curated 42 power grid technology and infrastructure stocks alongside this latest wheeling charge story.
What Is Shikoku Electric Power Company's Investment Narrative?
Holding Shikoku Electric Power Company means buying into a fairly traditional utility story. Regulated power supply, heavy infrastructure, and a slow growth profile. The raised consolidated profit guidance, helped by higher wheeling charges that reflect prices and interest rates, points to earnings support from the grid business even as non consolidated forecasts are trimmed and half year net income sits below last year’s level. The higher interim dividend to ¥27.50 per share suggests management still wants to present a shareholder friendly stance despite thinner margins and capital intensive assets.
In the short term, the key swing factors are tariff frameworks, fuel and financing costs, and how much of those can be passed through into future wheeling income. Debt coverage by operating cash flow has been flagged as a weak point, which matters when interest rates sit higher and large generation or network projects compete for capital. The mixed guidance revisions pull those balance sheet questions closer to the front of the Shikoku Electric Power Company equity story rather than leaving them as a background worry.
Even so, there is a structural pressure point in this utility’s setup that could still upset this relatively steady picture once you focus on ...
There's only one way to know the right time to buy, sell or hold Shikoku Electric Power Company. Head to Simply Wall St's company report for the latest analysis of Shikoku Electric Power Company's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Shikoku Electric Power Company research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Shikoku Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shikoku Electric Power Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Shikoku Electric Power Company?
If Shikoku Electric Power Company has sharpened your thinking on regulated utilities but you want a broader watchlist, the Simply Wall St screener can surface other stocks that fit the type of risk and return profile you prefer.
- If you care most about paying a fair price for quality, use the 21 high quality undervalued stocks to see companies where fundamentals and valuation screens line up.
- For readers who want income on top of potential capital gains, tap into the 27 dividend fortresses to find payouts that clear a 5% yield hurdle and still aim for resilience.
- If capital preservation is your first filter, start with the 19 resilient stocks with low risk scores to see which businesses score well on balance sheet strength and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com