


EN
How Investors Are Reacting To Western Union Stock Lower Earnings Tie Growth To Intermex Deal
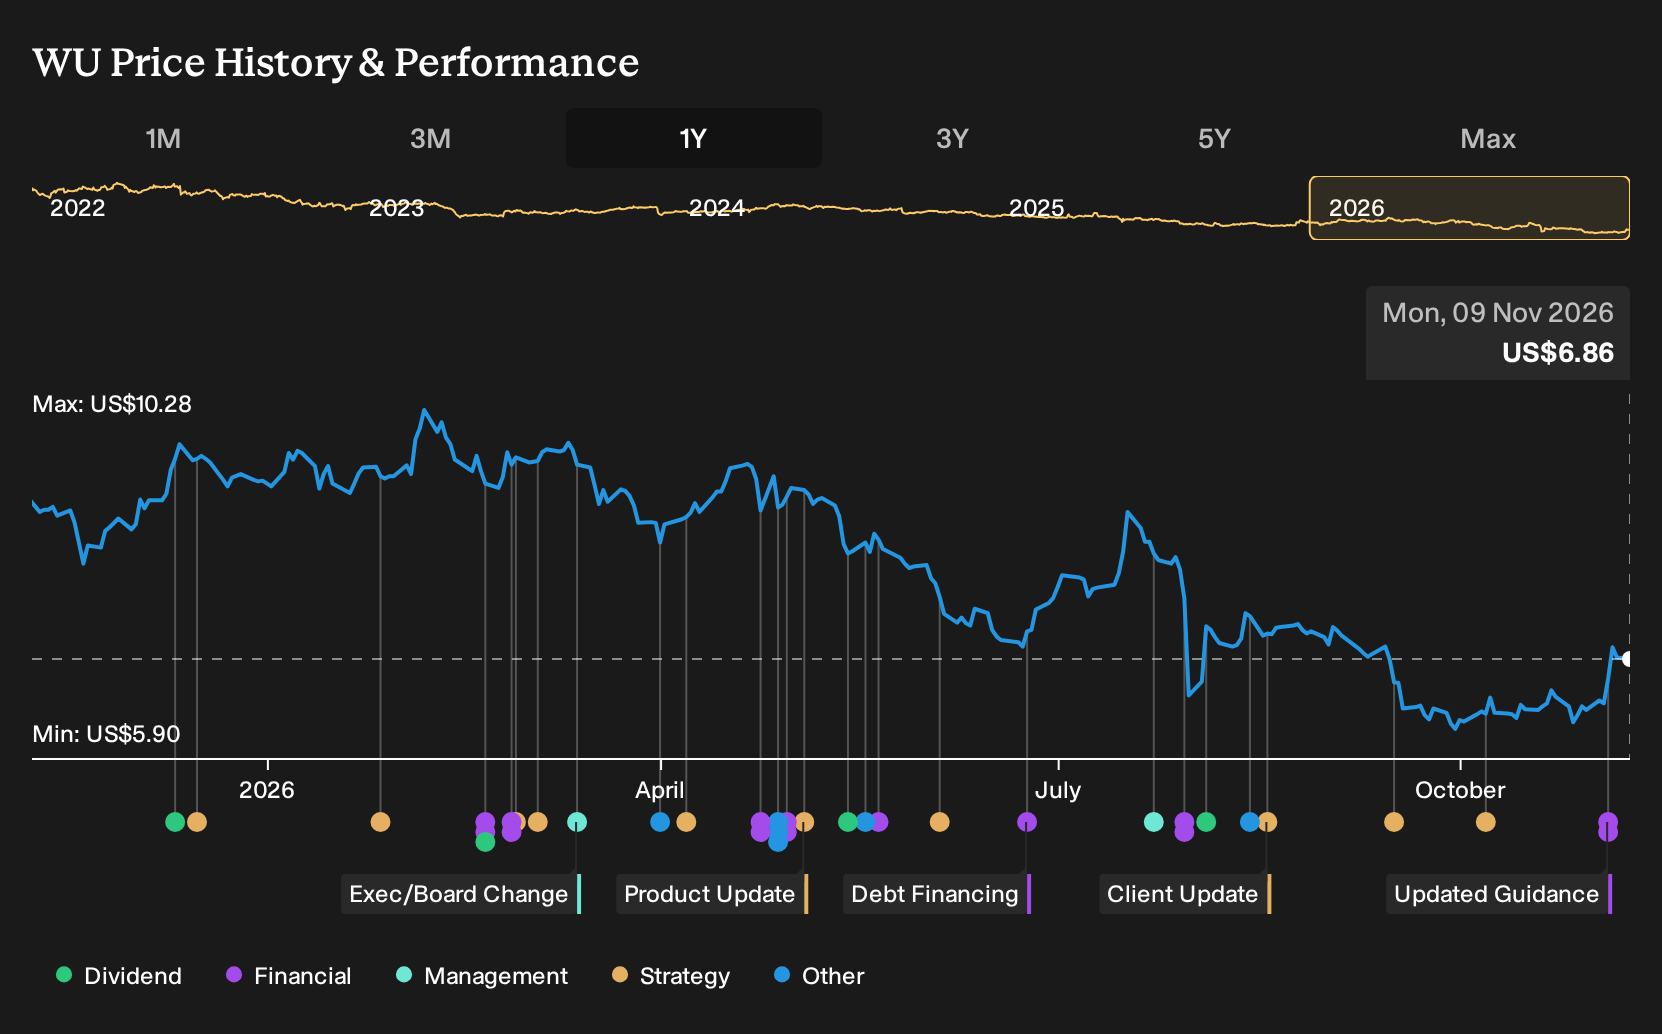
- Western Union reported Q3 2026 revenue of US$1,009.3 million and net income of US$78 million, both lower than the same period a year earlier, and updated full year guidance that ties 2026 revenue outcomes to whether the planned Intermex merger closes.
- The earnings update highlights how much Western Union now leans on the Intermex deal to offset weaker organic performance, even as it pushes digital platforms, stablecoin services and cost savings to reshape its underlying business mix.
- The focus now turns to how Western Union's investment narrative holds up as lower earnings intersect with guidance that depends on closing Intermex.
Western Union Investment Narrative Recap
To stay with Western Union, you need to believe the move toward digital transfers, wallets and consumer services can offset pressure on traditional corridors and lower margin online flows. The latest quarter showed revenue of US$1,009.3 million and net income of US$78 million, both below last year, which keeps that execution test front and center.
The near term catalyst is clear. Western Union needs to prove it can sustain earnings while shifting mix and cutting costs, and then layer Intermex volume on top. The main risk right now is that weaker profitability, regulatory issues and any Intermex disruption combine to keep margins and cash generation under strain.
The updated 2026 guidance tied to the Intermex merger is the announcement that matters most here. Management now frames GAAP revenue for the year as flat to up 1% if the deal closes on 10 November 2026, and down 1% to 2% if it does not. This makes the transaction a clear swing factor.
For you as a shareholder, that makes execution on integration part of the core thesis, not a side bet. It connects directly to the analyst consensus Narrative on Simply Wall St, which focuses on scale, cost savings and digital expansion as key drivers. Any delay, regulatory hurdle or underperformance from Intermex would cut into that story and keep the focus on Western Union's organic pressure instead.
Western Union's narrative projects US$4.6b revenue and US$445.9 million earnings by 2029. This assumes 4.2% yearly revenue growth and around US$50.5 million earnings increase from US$395.4 million today.
Uncover why Western Union's fair value is consistent with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts frame Western Union's cost cutting plans as the real catalyst, not just the Intermex deal. Before this earnings update, the bullish group was pencilling in about US$4.8b of revenue and US$516.9 million of earnings by 2029. That is a much more upbeat story than consensus, and this quarter's reset could push those views closer together or further apart.
Explore 5 other Western Union fair value estimates, including one that suggests as much as 314% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Western Union research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Western Union. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Union's overall financial health at a glance.
Looking for more Western Union style investment ideas?
If the Western Union story has you thinking about risk, balance sheet strength and income potential, the Simply Wall St Screener can help you widen the field and compare opportunities side by side.
- For investors who want potential upside with a valuation cushion, you can review a curated set of businesses screened as 33 high quality undervalued stocks.
- If capital preservation and resilience matter most to you, focus on companies that show up in our 30 resilient stocks with low risk scores.
- For those building an income focused approach, use the screener that highlights 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com