


EN
What Sea (SE)'s $1 Billion Buyback Means For Shareholders
- Sea Limited reported third quarter 2026 revenue of US$8.58b and net income of US$502.46m, with all core segments contributing to higher basic and diluted earnings per share, and the board approved an additional US$1b share repurchase authorization after nearly completing the prior program.
- Although adjusted earnings per share were below analyst forecasts, Sea Limited reported strong revenue performance across Shopee, Monee, and Garena, along with improved profitability metrics and a renewed buyback that reflects management’s stated confidence in the company’s operational footing and capital position.
- We will now look at how Sea Limited's multi segment revenue performance and the new US$1b buyback shape the investment narrative.
Sea Investment Narrative Recap
To own Sea, you need to believe its three engines, Shopee, Monee and Garena, can keep pulling in users and monetisation without letting costs or credit risk run ahead of revenue. The analyst consensus narrative on Simply Wall St leans on that balance. Q3 results showed revenue of US$8.6b and net income of US$502.5m, so the multi segment model is clearly in motion.
The near term swing factor looks tied to execution in Shopee logistics and Monee underwriting, given prior developer cuts and higher yield loan exposure. Missed EPS versus expectations points to pressure on margins as Sea reinvests. The biggest current risk is that any stumble in credit quality or product delivery erodes those early profitability gains.
The fresh US$1b share repurchase authorization sits alongside revenue of US$23.5b and net income of US$1.4b for the nine months to September 30, 2026. That combination indicates that Sea is generating enough earnings to fund operations and still return capital, which can help cushion sentiment while the market digests the EPS miss.
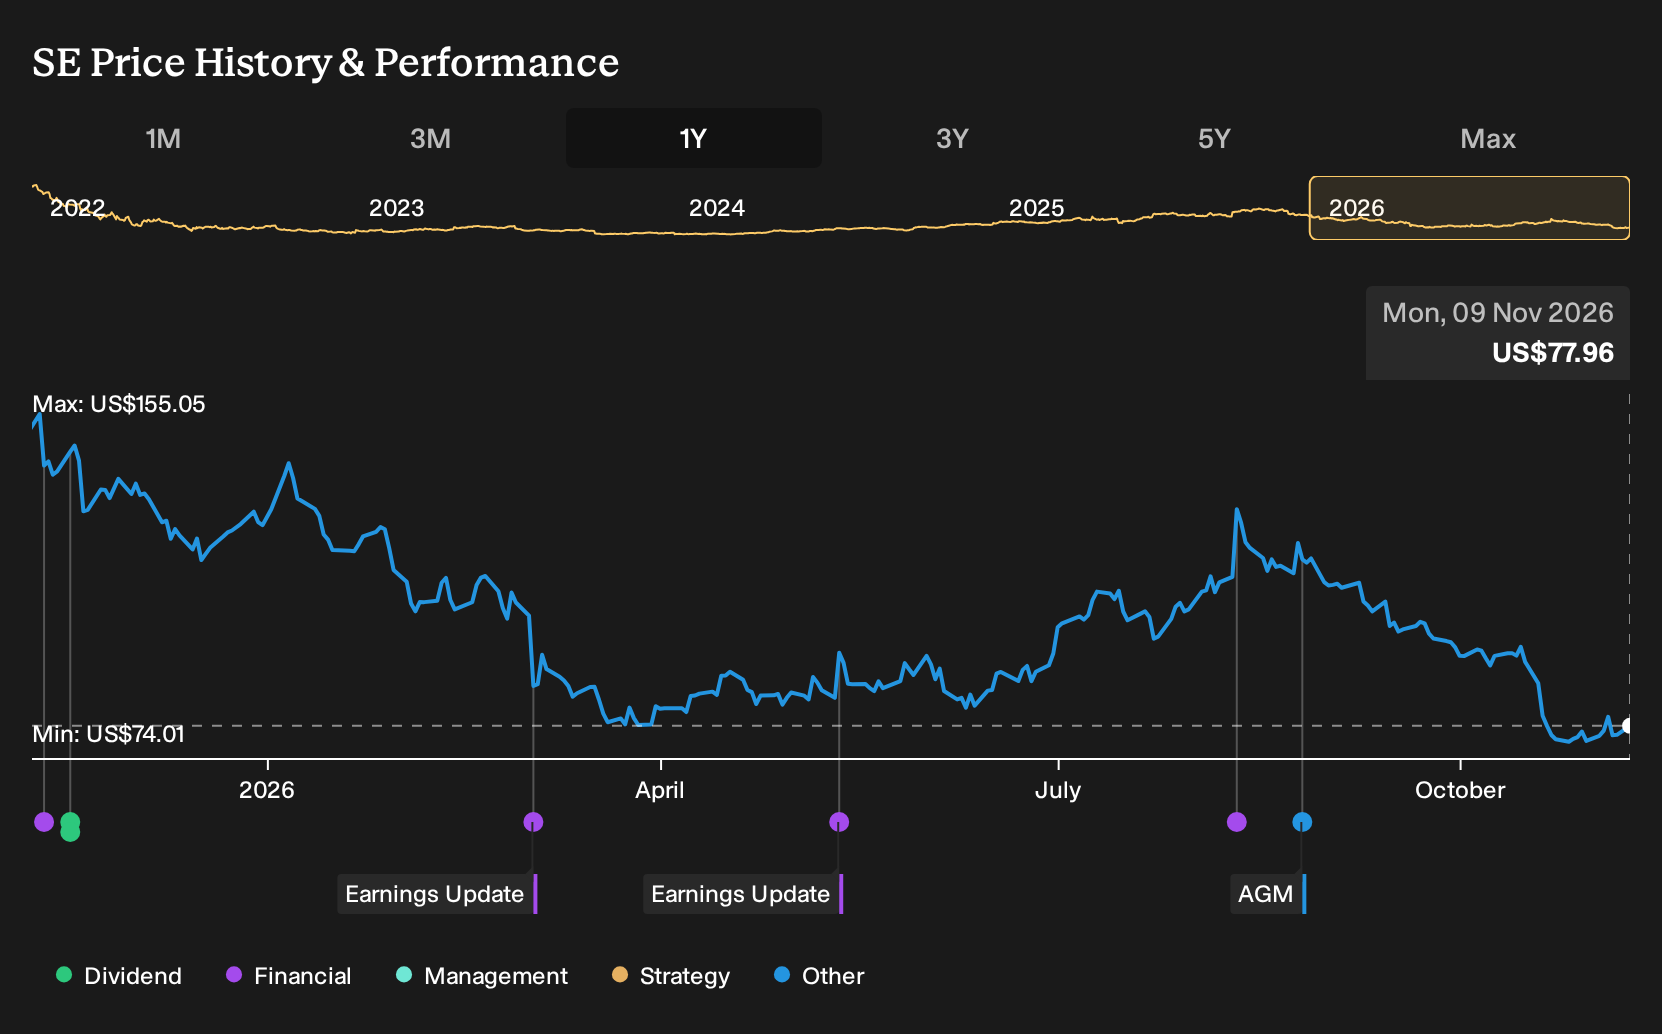
For catalysts, that buyback matters because it interacts directly with the volatility already seen in Sea’s share price and with the analyst consensus narrative on Simply Wall St. If Shopee, Monee and Garena each keep contributing to earnings, ongoing repurchases can tighten the share count and amplify per share metrics, though none of that removes the need for disciplined credit risk and cost control.
Sea's Long Range Assumptions And What Has To Happen
Sea's narrative projects US$47.6b revenue and US$3.8b earnings by 2029. That path relies on analysts' assumption of 19.7% yearly revenue growth and an earnings increase of about US$2.2b from US$1.6b today.
Uncover why Sea's fair value indicates a 90% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view fixates on logistics investment as the key risk. You might see the Q3 beat on Sea Limited’s US$8.6b revenue and fresh US$1b buyback, while the most cautious analysts were only pencilling in roughly US$42.1b revenue and US$3.0b earnings by 2029. That is a far more restrained story. Those forecasts came before today’s results and repurchase news, so opinions may move around. Treat these bearish assumptions as one reference point and explore a range of scenarios before deciding where you sit.
Explore 3 other Sea fair value estimates, including one that suggests it could be worth just $147.72!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sea research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sea. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sea's overall financial health at a glance.
Looking For More Ideas Beyond Sea?
Once you have a view on Sea, it can help to cross check that thesis against other businesses with different risk and return profiles using the Simply Wall St Screener.
- For investors who care about both resilience and upside potential, consider scanning a focused universe of companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If your priority is paying less for quality, you can compare Sea against other opportunities screened for valuation support and financial strength by reviewing the 33 high quality undervalued stocks.
- When you want ideas where the emphasis is on durability and smaller drawdowns, filter for stocks with more conservative risk scores using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com