


EN
James Hardie Industries (ASX:JHX) Returned To Profit And Held Guidance, Is It Fully Priced?
Q2 earnings and guidance reset the conversation
James Hardie Industries (ASX:JHX) has just paired a return to profitability with fresh guidance. The business posted stronger Q2 and first half numbers, then backed that up by confirming its outlook for fiscal 2027.
The latest guidance and earnings have arrived alongside a sharp shift in sentiment, with James Hardie Industries’ share price delivering a 1-month return of 18.56% and a year-to-date share price return of 38.97%. The 1-year total shareholder return of 63.32% contrasts with weaker 3 and 5 year total shareholder returns, suggesting momentum has recently improved after a tougher longer stretch.
Spot potential follow through by James Hardie Industries, and compare it with 2 high quality undervalued stocks, which also pairs improving profitability with stronger recent momentum.After a move like this and fresh guidance on the table, the real tension is timing. Is James Hardie Industries already pricing in the rebound, or has the valuation not fully caught up yet?
Most Popular Narrative: 2% Undervalued
On the analyst consensus Narrative on Simply Wall St, James Hardie Industries screens as modestly undervalued, with a fair value of A$43.58 set against the last close at A$42.79. That Narrative leans heavily on quantified revenue, margin and capital allocation plans rather than short term sentiment.
The integration of AZEK has more than doubled James Hardie Industries' North American serviceable addressable market to about US$23b, and management continues to focus on capturing material conversion from wood and vinyl exteriors, which directly targets higher long term revenue growth.
What is behind 40 investors see James Hardie Industries as 2% undervalued.
Result: Fair Value of A$43.58 (UNDERVALUED)
Still, the James Hardie Industries story can break the other way if AZEK integration synergies disappoint or if raw material and freight costs bite harder than planned.
Find out about the key risks to this James Hardie Industries narrative.
Another View: What P/E Says About James Hardie Industries
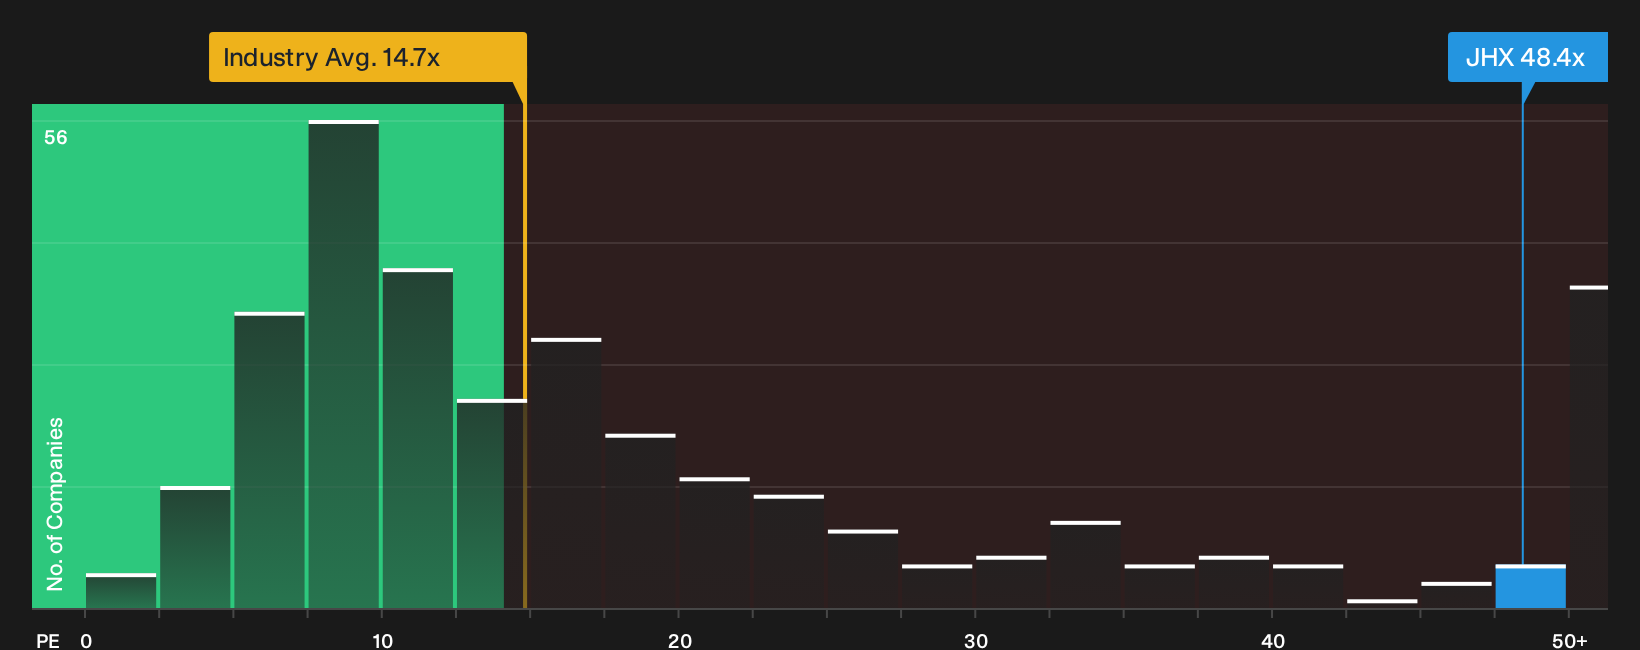
The first narrative casts James Hardie Industries as modestly undervalued. The simple earnings multiple tells a tougher story. JHX trades on a P/E of 48.3x, compared with 14.7x for the global Basic Materials group, 29.6x for peers, and a fair ratio of 18.4x that the market could move towards.
That gap means a lot of future profit improvement is already baked into the price, which raises a practical question for you as an investor. Is that kind of valuation gap a risk worth carrying, or do you prefer situations where the market is closer to the fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this blend of optimism and concern around James Hardie Industries seems finely balanced, consider acting promptly. Review the underlying data and evaluate both the potential opportunities and risks for yourself with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond James Hardie Industries?
James Hardie Industries may fit your thesis today, but wider opportunities are always moving. Use focused stock lists to quickly surface ideas that match your style.
- Target potential mispricings by scanning a curated pool of under-the-radar value opportunities through 2 high quality undervalued stocks.
- Strengthen capital preservation by focusing on companies that pair durable balance sheets with solid fundamentals using the list of solid balance sheet and fundamentals (12 results).
- Hunt for tomorrow's potential standouts by filtering for quality enterprises that the market has not fully focused on through 14 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com