


EN
Is DHT Holdings (DHT) Undervalued After Blowout Q3 Earnings?
DHT Holdings (DHT) put up a striking third quarter update, with net income of US$270.87 million and earnings per share of US$1.68, sharply above last year’s levels.
Despite the strong Q3 showing, DHT Holdings’ share price has recently given back some ground, with a 7 day share price return of down 13.83% and a 30 day move of down 16.56%. At the same time, the 1 year total shareholder return sits at 76.76% and the 5 year total shareholder return is over 4x. This indicates that longer term momentum remains in place, while shorter term sentiment cools after a sharp run up.
Spot 33 high quality undervalued stocks that, like DHT Holdings, pair strong recent profitability with balance sheets and cash flows that support the current earnings profile.DHT Holdings has packed years of return into a short window, then dropped hard just as earnings reached record territory. Is this the phase where most of the upside is already behind the stock, or is it not yet priced in?
Most Popular Narrative: 25% Undervalued
On the analyst consensus Narrative on Simply Wall St, DHT Holdings screens as undervalued, with a fair value of about $27.37 versus the last close at $20.56. That gap rests on a detailed set of shipping market assumptions, earnings forecasts and discount rate inputs.
The mix of existing high-rate time charters, including multi-year contracts around $75,000 to $100,000 per day on vessels like DHT Jaguar and DHT Panther, is building a sizeable backlog that can support visibility on future TCE revenue and EBITDA. This reinforces expectations for strong cash generation that current valuation multiples already capture.
See why 104 investors see DHT Holdings as 25% undervalued.
Result: Fair Value of $27.37 (UNDERVALUED)
Still, the narrative around DHT Holdings can crack if generous dividends outrun free cash flow or if a sharp P/E de-rating follows any earnings disappointment.
Find out about the key risks to this DHT Holdings narrative.
Another View: Cash Flows Paint A Tougher Picture
There is a catch. While the analyst narrative tags DHT Holdings as undervalued on earnings and price targets, the Simply Wall St DCF model points the other way, with an estimated future cash flow value of $13.33 against a share price of $20.56. This implies the stock screens as expensive on that basis. Which lens do you trust more: earnings power or cash generation risk?
For a closer look at how those long term cash assumptions are built and discounted in practical terms, Look into how the SWS DCF model arrives at its fair value..
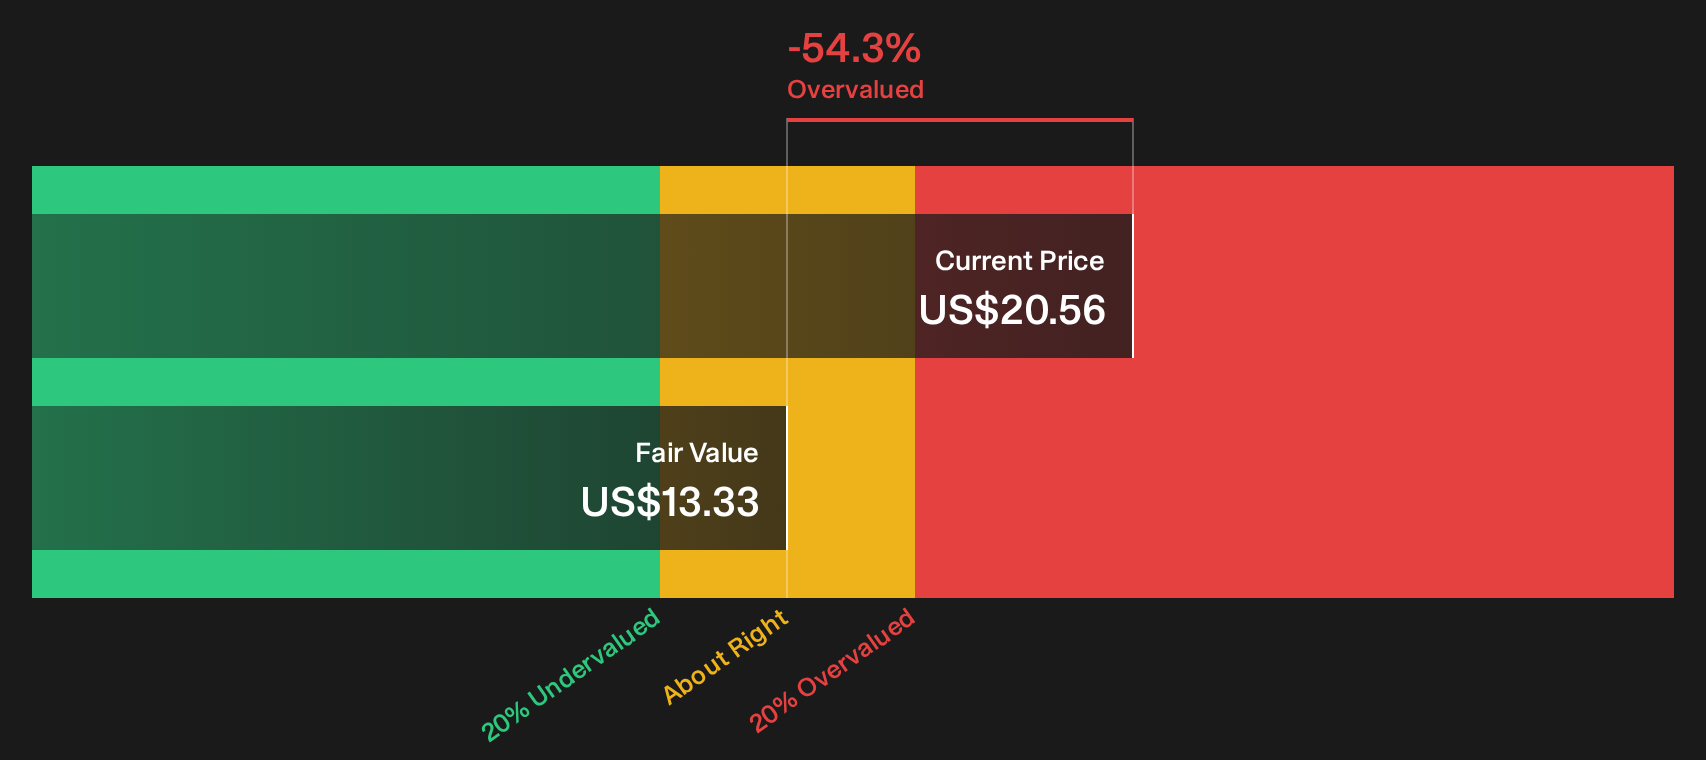
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DHT Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Confused by the mixed signals around DHT Holdings and whether the recent share pullback changes the story? Take a few minutes to review the underlying numbers, weigh the long term track record, and balance the upside against the downside using the 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond DHT Holdings?
If DHT Holdings has you thinking harder about risk, reward and timing, do not stop your research here. Broaden your watchlist with targeted screeners built to surface focused ideas fast.
- Target resilient cash generators by scanning a 6 dividend fortresses that can help you focus on payout strength backed by financial robustness.
- Hunt for mispriced opportunities by reviewing a 19 high quality undiscovered gems before the broader market catches on and reprices them.
- Prioritise stability and capital protection through a 30 resilient stocks with low risk scores that can help you filter for companies with steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com