


EN
Is D Wave Quantum (QBTS) Fully Priced Or Priced For Perfection?
D-Wave Quantum has seen sharp swings in its share price over recent years, which puts fresh attention on a simple question for investors who focus on fundamentals. Is the current valuation of the stock meaningfully supported by the company’s book value, or has the price run ahead of what its balance sheet can justify?
- Over the past 3 years, D-Wave Quantum has delivered a very large share price gain of about 1,479%, which makes the link between today’s market value and its underlying net assets a key issue.
- Recent contract wins, funding access and product rollouts point to management targeting faster commercialization of quantum services. This can influence how much weight investors place on current book value compared with future capital needs and potential returns on that investment.
- There is a second opinion on D-Wave Quantum worth weighing. See what analysts think D-Wave Quantum's shares could be worth.
The issue now is whether the price investors pay today for D-Wave Quantum aligns closely enough with the company’s book value to look well grounded on this single lens.
To put D-Wave Quantum’s valuation story in context, it helps to compare it with other quantum computing stocks using 25 quantum computing stocks.
Does D-Wave Quantum Look Pricey on Book Value?
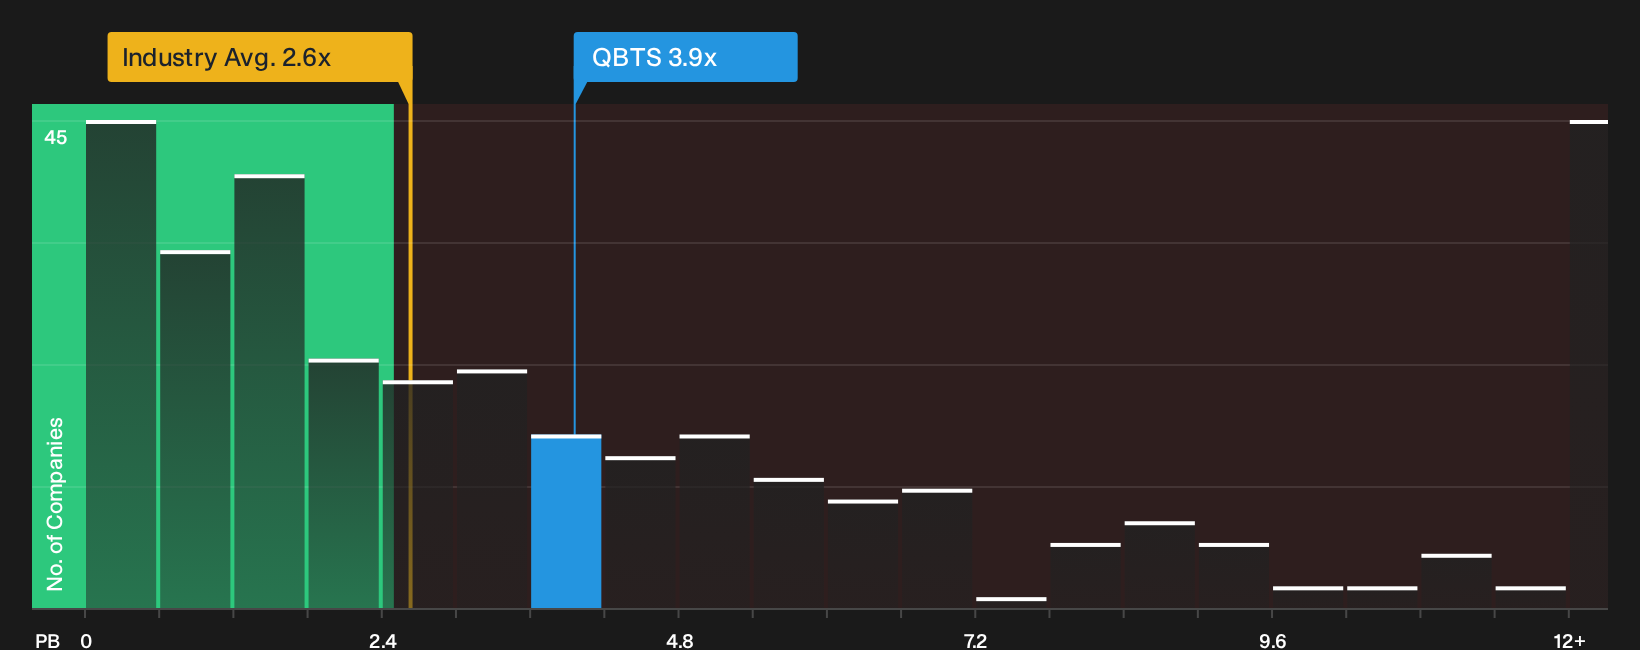
P/B is a useful lens for D-Wave Quantum because the business is still loss making, so book value can act as a rough anchor when earnings do not. On this measure, D-Wave trades at a P/B of about 3.9x, which is below the peer group average of roughly 6.8x but above the broader software sector at about 2.6x. That mix suggests the stock is priced richer than the typical software company on balance sheet value, even though it does not carry the highest valuation within its more focused quantum set, so the market is already assigning a premium to its equity base.
The recent funding access under the US CHIPS and Science Act may help explain why investors are comfortable paying a higher multiple to book for D-Wave Quantum despite ongoing free cash flow losses. For a holder, the key judgment is whether that near 4x P/B ratio is a reasonable price for a capital intensive quantum platform that still relies on external funding to support its roadmap, or whether the implied premium to the broader industry leaves less room for balance sheet driven upside. Explore the numbers behind D-Wave Quantum's P/B valuation.
The D-Wave Quantum Narrative: What Would Justify Today's Price?
Narratives for D-Wave Quantum pick up where the P/B puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today's market price on Simply Wall St's Community page. Instead of relying on a single ratio or model output, they break that figure into a concrete future you can watch over time to see whether it is actually unfolding.
On D-Wave Quantum, the bullish crowd sees a cash rich quantum platform while the skeptics focus on near term revenue delivery and positioning.
Bull case: 72% undervalued
According to Wil_Analyst, an investor in the Simply Wall St Community, fresh capital and deals reshape how upside in D-Wave Quantum is framed.
"Through a massive $550 million acquisition, a record-breaking month of sales, and a newly fortified balance sheet, D-Wave has moved the "Quantum Era" off the whiteboards and into the executive boardroom..."
Discover why this Narrative puts D-Wave Quantum at 72% undervalued.
Bear case: 11% overvalued
DanielOliveira, a Simply Wall St Community investor who wrote the Narrative, argues that near term expectations for D-Wave Quantum look stretched.
"The consensus is $32.2 million, and I forecast $14.9 million..."
Explore why this Narrative puts D-Wave Quantum at 11% overvalued.
D-Wave Quantum's valuation still leaves one crucial relationship unexplored
Prices reflect balance sheets and promises, but for D-Wave Quantum the people steering the roadmap and how their rewards line up with shareholder outcomes could be just as important to understand. See who runs D-Wave Quantum and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com