


EN
How Investors Are Reacting To RTX (RTX) Earnings Beat
- RTX reported third quarter 2026 adjusted earnings per share of $2.26 that exceeded the Zacks Consensus Estimate, alongside 11.1% year over year revenue growth supported by commercial aftermarket and defense demand and underpinned by a record $340b backlog that includes $164b of defense projects.
- The combination of higher profit than analysts expected and very large contracted defense work gives RTX unusual visibility into future workload and operating scale compared with many aerospace and defense peers that report smaller or less diversified backlogs.
- We will now look at how RTX’s earnings beat and record defense backlog shape the investment narrative going forward for investors.
RTX Investment Narrative Recap
To own RTX, you need to believe that its large defense and commercial aerospace backlog keeps converting into steady revenue and cash flow, as set out in the analyst consensus Narrative on Simply Wall St. The key short term swing factor is execution on that backlog, including supply chain capacity and on time deliveries. Recent DeepStrike JR3 test success supports the idea that Raytheon can field new systems for live programs rather than just concepts.
The biggest near term risk still sits with policy and cost pressures. Heavy dependence on U.S. and allied defense budgets, together with exposure to tariffs and elevated engineering and capital spending, could squeeze margins if contracts are delayed or costs stay sticky. The JR3 update does not materially change those risks, but it does underline RTX’s operational workload in missiles and training rockets.
The recent DeepStrike JR3 flight test series is the clearest operational link to RTX’s defense backlog story. A reusable training rocket that fits the Multiple Launch Rocket System pod speaks directly to high volume munitions and training demand, which is one of the major themes behind RTX’s large contracted pipeline in missiles and related systems.
In terms of potential catalysts, successful JR3 testing supports the view that Raytheon can absorb and execute multi year munitions agreements that feature higher planned volumes. That matters if you already see capacity expansion and backlog conversion as the main route to earnings growth. The remaining watchpoint is whether supply chain constraints in rocket motors and electronics stay manageable as programs like JR3 move toward qualification and production ramp.
RTX's narrative projects US$113.0b revenue and US$10.9b earnings by 2029. This implies revenue growth of 6.5% per year and an earnings increase of about US$3.2b from US$7.7b today.
Discover why RTX's fair value suggests a 17% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
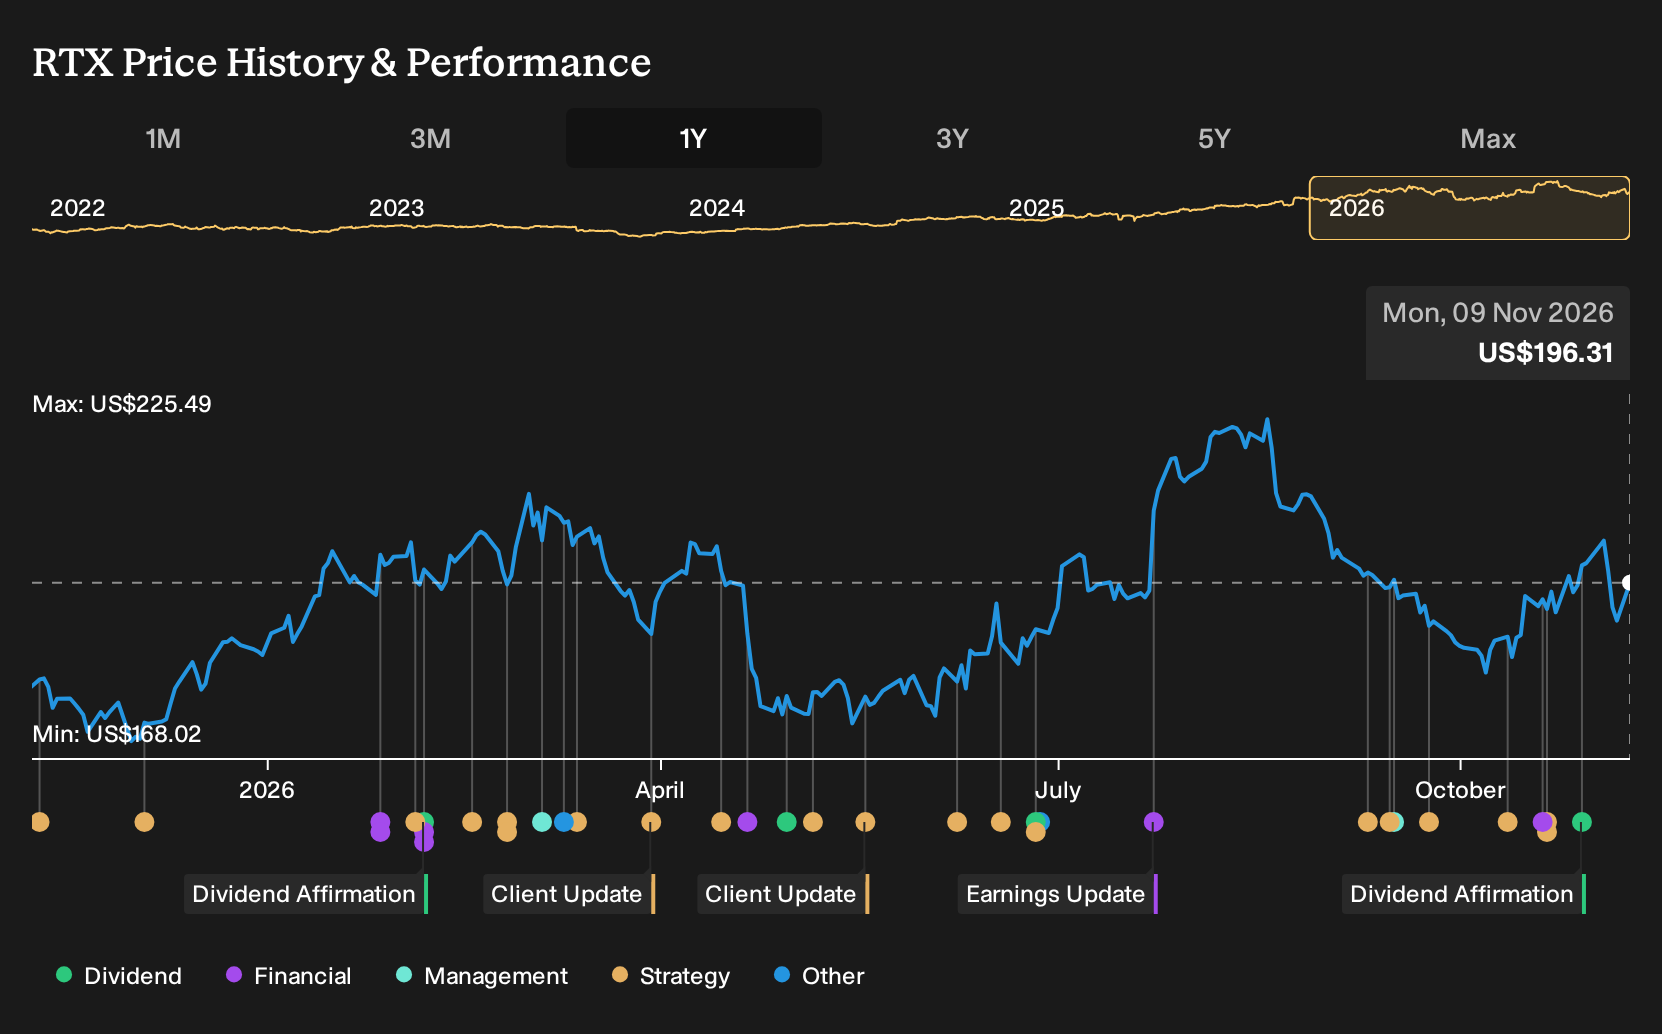
Three fair value estimates from the Simply Wall St Community cluster between about US$206 and US$229 per share, so you are seeing a tight band rather than outliers. That sits alongside fresh catalysts such as RTX’s DeepStrike JR3 progress, dividend affirmation, and ETF outflows, which together illustrate how sharply investor opinions can differ. Explore the full spread of views before considering how RTX may fit within a portfolio.
Explore 2 other RTX fair value estimates, including one that suggests it could be worth just $205.99.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis.
- A great starting point for your RTX research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RTX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RTX's overall financial health at a glance.
Looking For More Investment Ideas Beyond RTX?
If RTX has sharpened your interest in defense and aerospace, it can help to line it up against other opportunities that share similar qualities. A focused stock screener lets you quickly filter for balance sheet strength, income potential, or overlooked quality, so you can build a watchlist that really matches your risk tolerance and goals.
- For investors who care most about financial resilience and lower volatility, start with companies that clear strict balance sheet and fundamentals checks using the list of solid balance sheet and fundamentals (25 results).
- If dependable income is a priority, focus on businesses that combine higher yields with a track record of sustaining payouts by reviewing the 6 dividend fortresses.
- To uncover potential future leaders before they attract broad attention, scan financially sound smaller players that screen well on quality metrics through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com