


EN
Should Strong Earnings Report Require Action From Par Pacific Holdings (PARR) Investors?
- Par Pacific Holdings reported third quarter 2026 sales of US$3,052.44 million and net income of US$353.31 million, with basic earnings per share from continuing operations of US$7.27.
- Across the first nine months of 2026, Par Pacific Holdings recorded US$7,845.05 million in sales and US$869.89 million in net income, which provides a basis for comparing earnings per share from continuing operations with the prior year’s levels.
- We will now look at how Par Pacific Holdings' sharp uplift in third quarter net income could influence the existing investment narrative.
Scan how Par Pacific Holdings' earnings profile compares with other fuel and energy players by reviewing a hand picked list of solid balance sheet and fundamentals (25 results) that may warrant a closer look alongside PARR.
Par Pacific Holdings Investment Narrative Recap
To own Par Pacific Holdings, you need to be comfortable with a refining-heavy business that is closely tied to Pacific Basin fuel markets, older plants and regional conditions in Hawaii and the Western U.S. The analyst consensus Narrative on Simply Wall St leans on tight product markets and strong margin capture. The latest quarterly figures, including US$3,052.44 million of sales and US$353.31 million of net income, support that earnings power for now.
The near-term catalyst remains operational execution. That means keeping refineries running reliably, holding high distillate and jet yields and managing the Hawaii Renewables ramp. The biggest current risk is still asset- and region-specific disruption, whether from outages, regulation or weather, combined with the expected step up in cash taxes as loss carryforwards are used.
The most relevant data point here is the nine-month 2026 performance. Par Pacific Holdings reported US$7,845.05 million in sales and US$869.89 million of net income from continuing operations over that period, with basic EPS of US$17.94. Those numbers give you a clearer run rate as you weigh how much of current refining strength is already visible in reported earnings.
When you set that against the analyst consensus Narrative on Simply Wall St, which factors in tighter markets, renewable diesel contributions and fading tax benefits, the recent earnings update becomes a check on execution rather than a new thesis. It shows how the business is converting the current environment into profit while the same old risks around refinery reliability, regional exposure and future tax cash outflows still frame the story.
Par Pacific Holdings' current earnings are reported at US$856.9 million, with analysts projecting earnings of US$386.7 million by 2029 and forecasting roughly US$7.2 billion in revenue in that same year. This implies a 6.0% yearly decline in revenue and an earnings decrease of about US$470 million from current levels to the 2029 consensus figure.
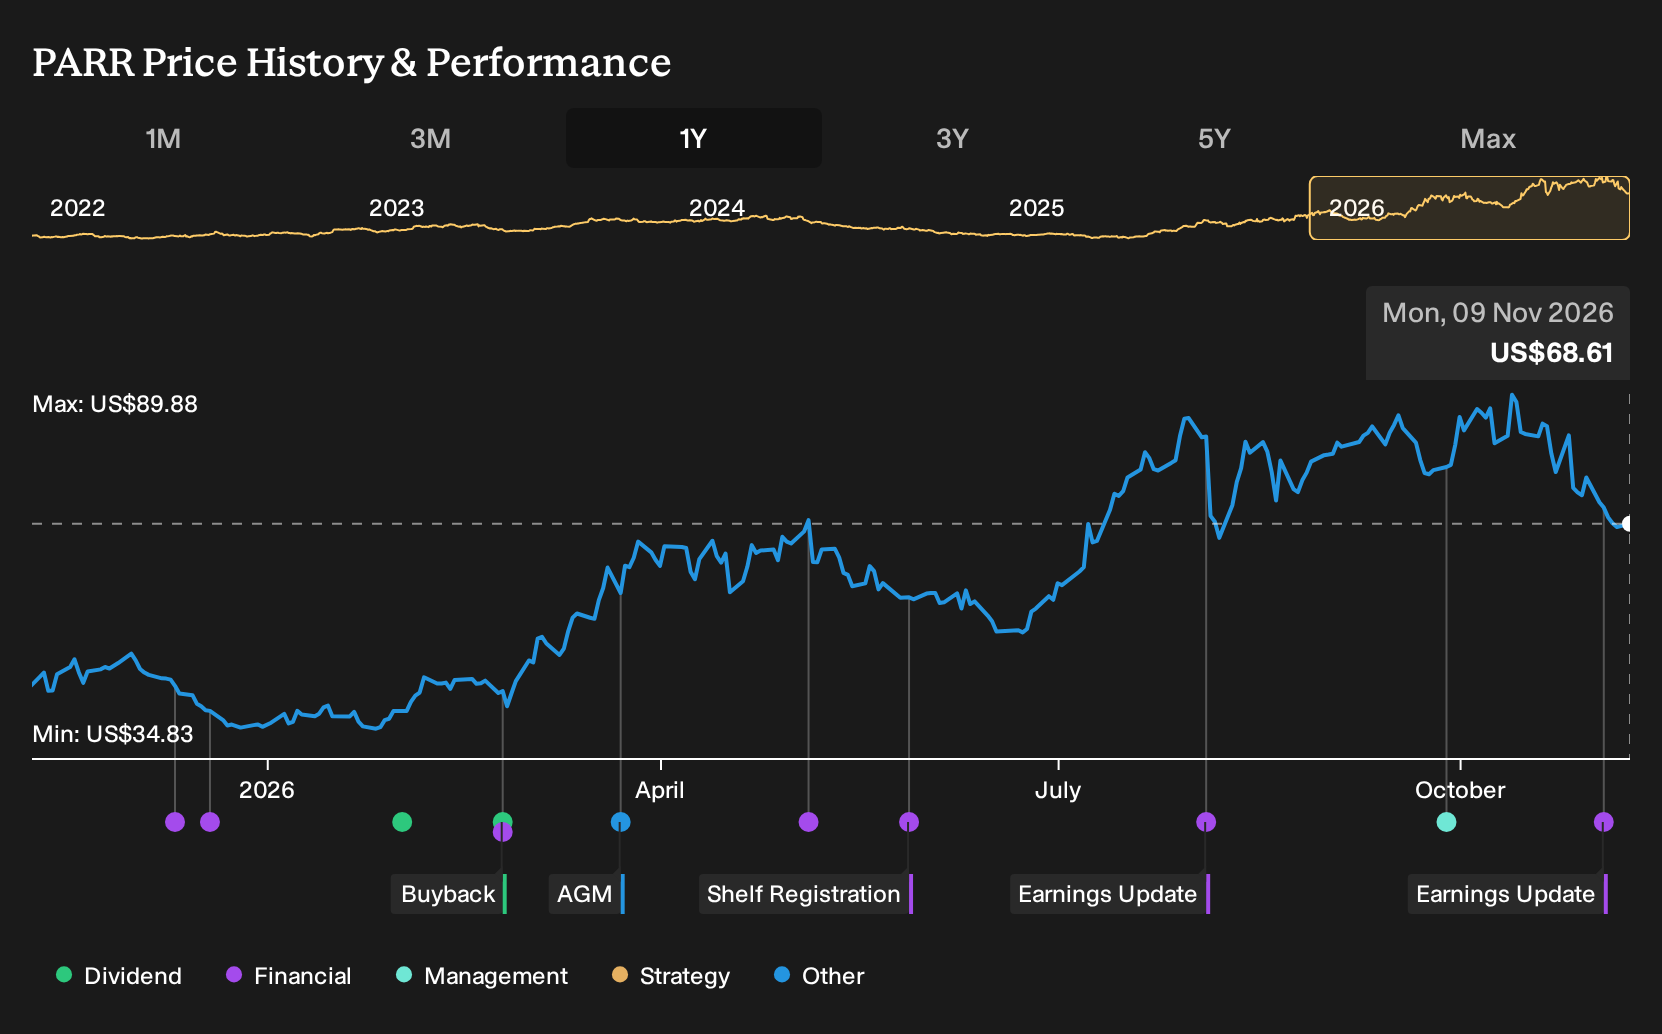
Uncover why Par Pacific Holdings' fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Par Pacific Holdings zooms in on future cash taxes rather than refinery strength. The most cautious analysts were pencilling in 9.1% yearly revenue declines and earnings of about US$293.6 million by 2029, well below consensus. Those estimates were set before this earnings surprise, so opinions may change over time.
Explore 3 other Par Pacific Holdings fair value estimates, including one that suggests as much as 44% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Par Pacific Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Par Pacific Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Par Pacific Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Par Pacific Holdings?
Once you have a view on Par Pacific Holdings, it can help to set that against a broader watchlist built from other companies with different profiles and balance sheet strengths.
- If you want potential upside with tighter risk controls, start by scanning a 30 resilient stocks with low risk scores that screens for resilience first and excitement second.
- For investors focused on price versus quality, check a 33 high quality undervalued stocks that highlights businesses where fundamentals and current valuations appear out of sync.
- To widen your opportunity set beyond the usual large caps, consider a 19 high quality undiscovered gems that surfaces under-followed companies with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com