


EN
How Investors May Respond To Harmonic (HLIT) Stronger Earnings Guidance
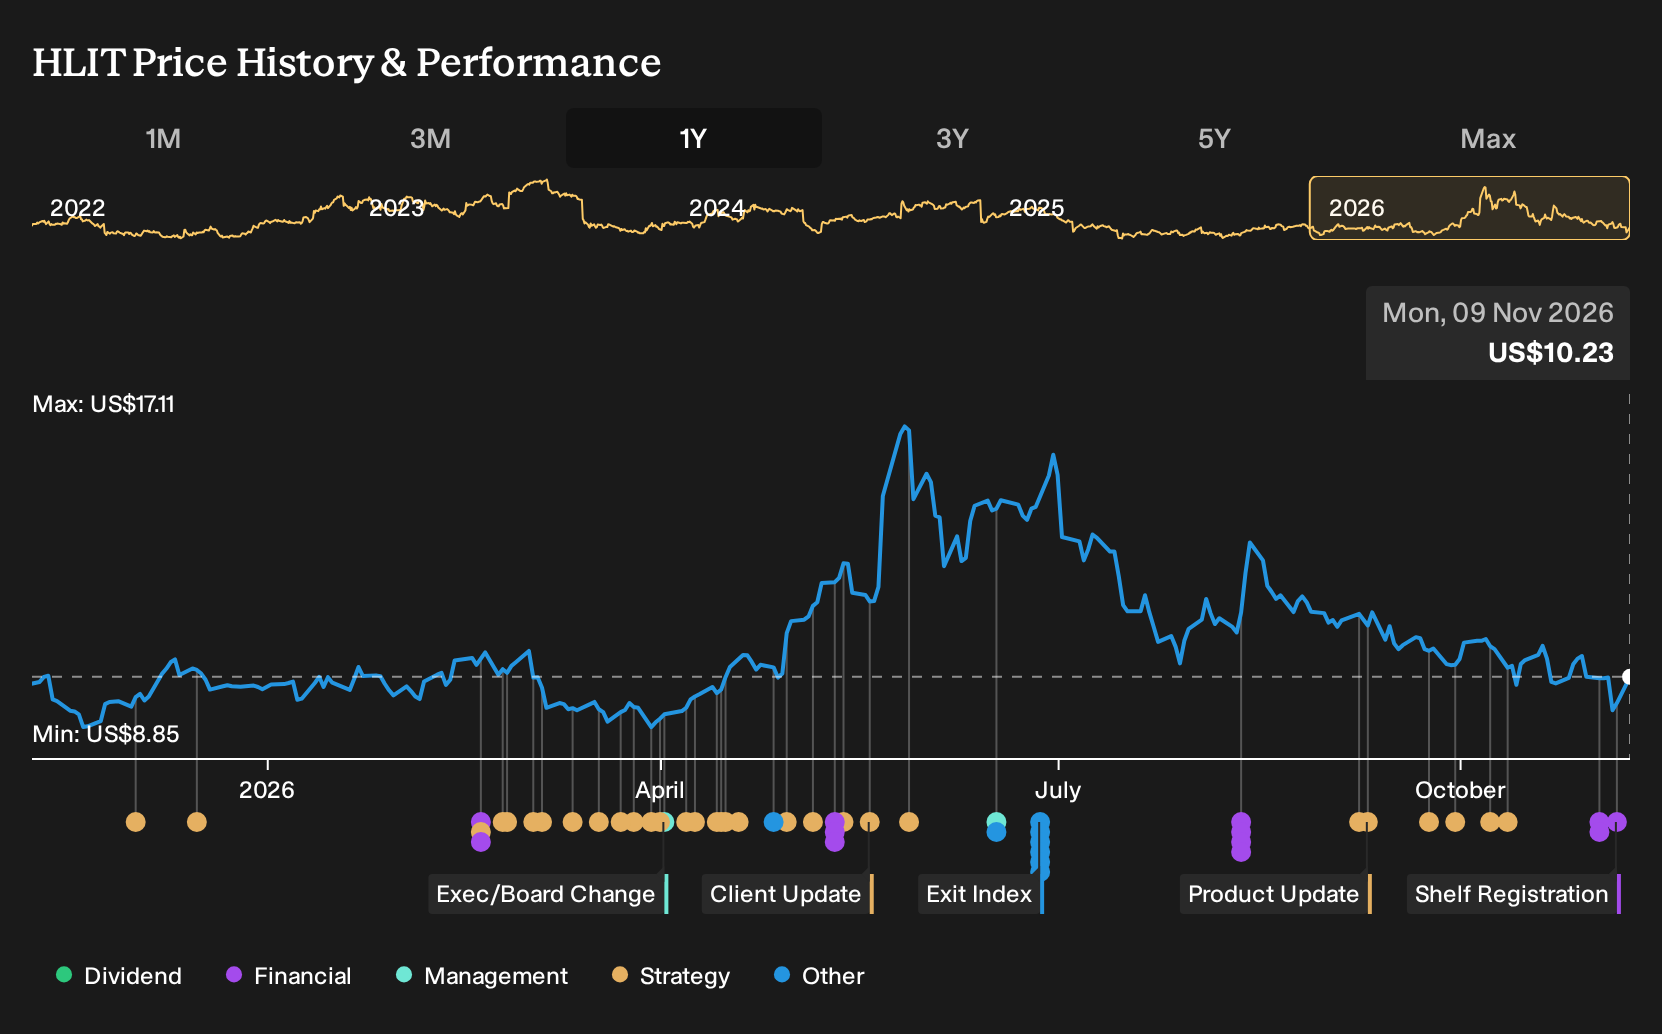
- Harmonic reported third quarter 2026 revenue of US$148.84 million and net income of US$14.64 million, issued full year 2026 guidance, and filed a US$27.93 million shelf registration for 3,000,000 common shares tied to an ESOP offering.
- The combination of stronger earnings and fresh guidance provides a clearer picture of how Harmonic’s broadband and software driven model is scaling in practice. The ESOP related shelf also highlights a focus on employee ownership during this phase of operational execution.
- The next area of attention is how Harmonic’s stronger quarterly earnings and raised full year guidance might reshape the broader investment narrative.
Harmonic Investment Narrative Recap
To own Harmonic, you need to believe the broadband access and software model can turn today’s cOS and intelligence footprint into steadier, higher-margin earnings over time. The analyst consensus Narrative on Simply Wall St leans on recurring and AI-driven software becoming a larger slice of the mix. The recent Q3 beat and full-year guidance sharpen that story but do not remove the usual execution questions.
In the near term, the key catalyst is Harmonic’s ability to hit its 2026 revenue and profitability targets while keeping large operator rollouts on track. The biggest risk still sits with customer concentration and hardware cost pressure, especially if memory expenses or deployment pacing move against the business in the next few quarters.
The updated fiscal 2026 outlook looks most relevant here. Management now expects full-year GAAP revenue of US$545 million to US$555 million and net income of US$59 million to US$63 million, which provides a clearer yardstick to judge how well Harmonic is converting broadband demand into earnings. It also links directly to the margin story that analysts are watching.
These guidance ranges matter because they frame whether the shift toward software, services and intelligence is offsetting factors such as memory costs and competitive pricing. If Harmonic executes close to the upper end of its net income and operating profit guidance while broadening its customer base beyond the top two operators, that would speak directly to the catalysts and risks described in the analyst consensus Narrative on Simply Wall St.
Harmonic's narrative points to revenues of US$630.9 million and earnings of US$93.8 million by 2029. This assumes revenue growth of 12.4% per year and an earnings increase of about US$67.4 million from US$26.4 million today.
Uncover why Harmonic's fair value indicates a 58% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist you might explore is how the highest analysts lean on Harmonic turning its broadband backlog and ESOP related shelf into fuel for a richer software mix. That group was penciling in 13.6% annual revenue growth and US$103.9 million in 2029 earnings before this Q3 update; their forecasts may shift again as fresh data lands.
Explore 3 other Harmonic fair value estimates, including one that suggests as much as 96% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your Harmonic research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harmonic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harmonic's overall financial health at a glance.
Looking For More Ideas Beyond Harmonic?
If you want to put Harmonic in context, it can help to scan a broader set of companies that share similar financial traits, whether you care more about value, resilience, or balance sheet strength.
- For investors who like paying less for quality, run a quick screen for 33 high quality undervalued stocks that combine solid fundamentals with more modest pricing.
- If income reliability matters most to you, focus on payout strength and stability by screening for 6 dividend fortresses that might better fit a yield focused portfolio.
- For a sturdier core around ideas like Harmonic, look for companies on our list of solid balance sheet and fundamentals (25 results) to help you concentrate on financially resilient options.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com