


EN
Citizens Financial Stock: Analyst Estimates & Ratings
Providence, Rhode Island-based Citizens Financial Group, Inc. (CFG) provides retail and commercial banking products and services. Valued at $27.3 billion by market cap, CFG offers consumer and commercial loans, mortgage finance, deposit products, retail and commercial banking, asset management, and trust services.
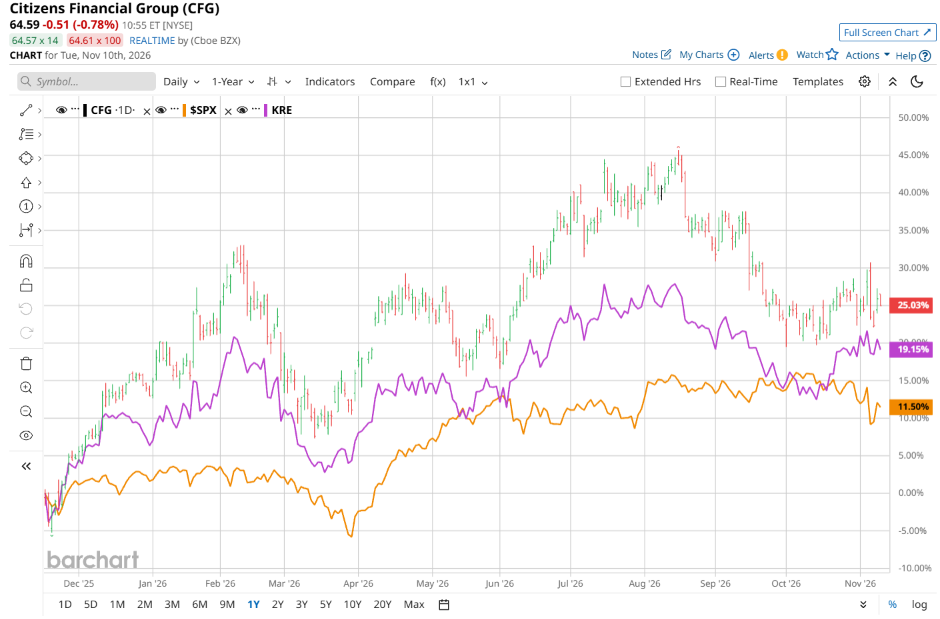
Shares of this bank holding company have outperformed the broader market over the past year. CFG has gained 24.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. In 2026, CFG stock is up 11.4%, surpassing the SPX’s 10.3% rise on a YTD basis.
Zooming in further, CFG’s outperformance looks less pronounced compared to the State Street SPDR S&P Regional Banking ETF (KRE). The exchange-traded fund has gained about 19% over the past year. However, the ETF’s 12.7% returns on a YTD basis outshine CFG’s gains over the same time frame.
CFG delivered record Q3 revenues, paced by a 2.7% sequential and 13% year over year increase in net interest income driven by disciplined deposit cost management and strong private banking expansion across California, Florida, and the Northeast. While fee income dipped slightly due to capital markets volatility and deferred transactions, wealth management fees and M&A advisory pipelines remained strong, and efficiency gains from the "Reimagine the Bank" program continued to deliver productivity improvements. Looking ahead, management expects net interest income to grow an additional 2.5% to 3% on further margin expansion while keeping expense growth below 5% through technology and artificial intelligence initiatives.
For the current fiscal year, ending in December, analysts expect CFG’s EPS to grow 37.3% to $5.30 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 22 analysts covering CFG stock, the consensus is a “Strong Buy.” That’s based on 16 “Strong Buy” ratings, two “Moderate Buys,” and four “Holds.”
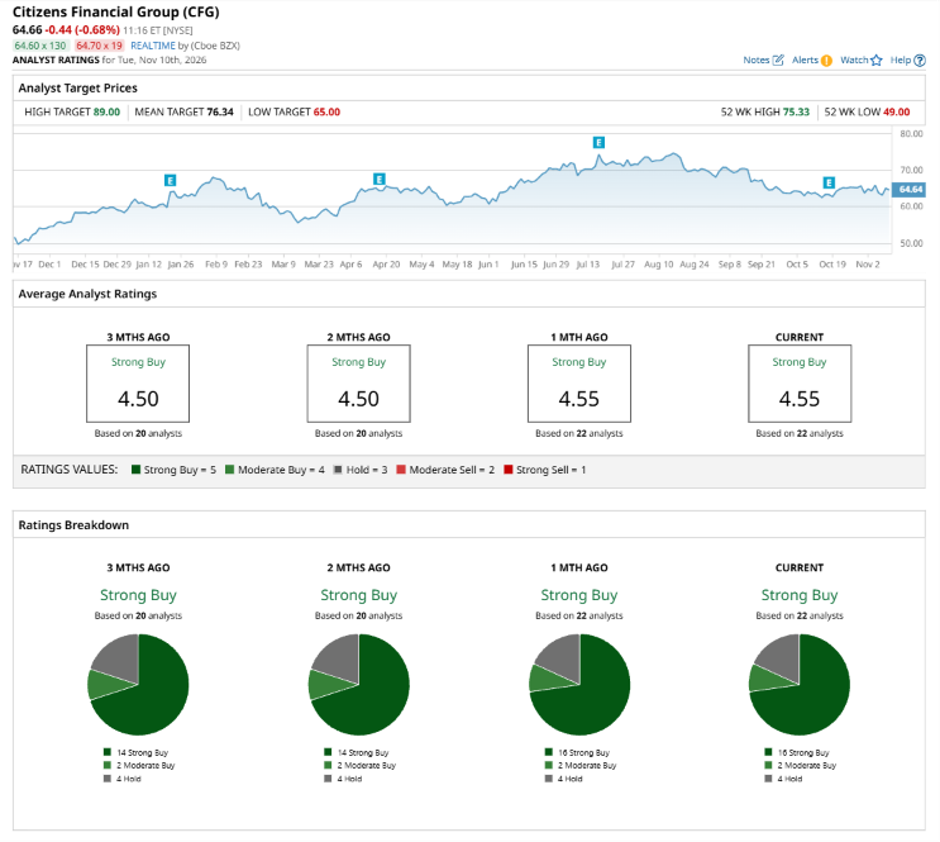
This configuration is more bullish than two months ago, with 14 analysts suggesting a “Strong Buy.”
On Oct. 29, Barclays PLC (BCS) analyst Jason Goldberg maintained a “Buy” rating on CFG and set a price target of $81, implying a potential upside of 25.3% from current levels.
The mean price target of $76.34 represents an 18% premium to CFG’s current price levels. The Street-high price target of $89 suggests an ambitious upside potential of 37.6%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.