


EN
Does Regulatory Progress Change The Bull Case For Immunome Stock (IMNM)?
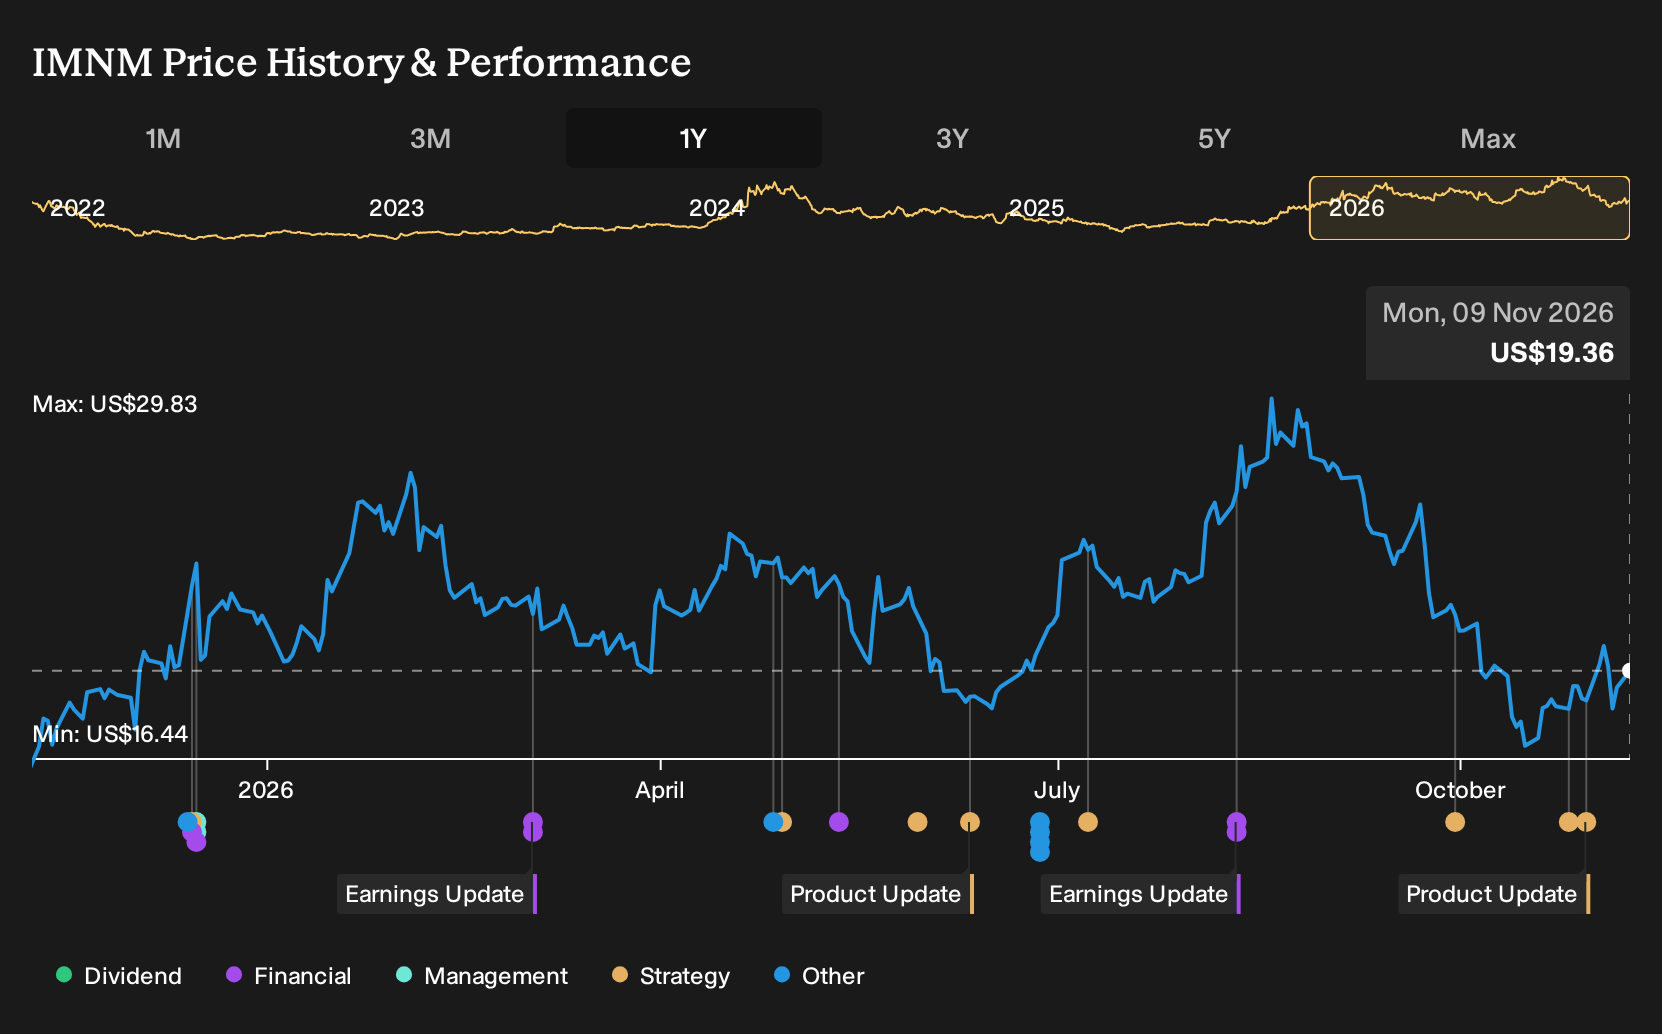
- Immunome reported third quarter 2026 results with a net loss of US$85.78 million and broadened its financing options through multiple shelf registrations covering equity, debt and warrants.
- Alongside deeper losses, Immunome advanced varegacestat, with EU regulatory review now underway, and highlighted early oncology pipeline progress that could reshape its future revenue mix if products reach market.
- This article examines how Immunome’s investment narrative is influenced by varegacestat’s EMA review progress and the broader oncology pipeline updates.
Scan how Immunome’s oncology story compares with other potential breakouts by sizing it up against a curated set of 36 healthcare AI stocks pushing new therapies toward regulators and real-world use.
Immunome Investment Narrative Recap
To own Immunome, you need to buy into a story where varegacestat and the early oncology portfolio eventually fund the whole operation. Right now the business is still all cost and no product revenue, with a third quarter net loss of US$85.78 million and losses over nine months of US$212.75 million. The analyst consensus Narrative on Simply Wall St expects revenue growth in future years, but the near term remains about execution, not earnings.
The key near term swing factor is still regulatory progress and eventual commercialization for varegacestat. The biggest risk is that higher spending and ongoing losses persist without a clear path to meaningful product sales, especially if desmoid tumor uptake, label terms, or timing undercut expectations. Recent results reinforce that Immunome is likely to rely on external capital while it advances the pipeline.
The fresh shelf registrations matter most in that context. Immunome now has an omnibus shelf covering common and preferred stock, debt securities, and warrants, plus a separate shelf of up to US$82.8 million tied to 4,425,487 common shares. This toolkit gives management flexibility to raise funds as clinical and regulatory milestones approach.
For you, the link to catalysts is straightforward. Varegacestat’s FDA PDUFA date in April 2027 and the EMA review sit on one side, while IM-1021 and IM-1340 progress sit on the other. The new financing capacity helps the company keep these programs moving, but it also raises dilution and capital structure risk if losses stay heavy and product revenue takes time to emerge.
Immunome's narrative projects US$306.2 million revenue and US$52.8 million earnings by 2029. This implies yearly revenue growth from effectively zero commercial sales today and an earnings increase of about US$307.1 million from current earnings of a US$254.3 million loss.
Uncover why Immunome's fair value indicates an 88% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
You have analysts at the low end who frame varegacestat’s competition risk very differently. Before this latest loss and shelf news, the bearish camp was only modeling about US$113.8 million in 2029 revenue and US$19.6 million in earnings. That is a far more cautious Immunome story, and these fresh updates may push forecasts to shift again.
Explore 2 other Immunome fair value estimates, including one that suggests it could be worth just $35.33!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and decision-making.
- A great starting point for your Immunome research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Immunome. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Immunome's overall financial health at a glance.
Looking For More Immunome-Sized Investment Ideas?
If Immunome’s story has sharpened your thinking about risk, cash burn, and upside, use that same lens across a wider watchlist. The Simply Wall St Screener lets you filter for businesses that better match your preferred mix of balance sheet strength, valuation, and income potential.
- For investors who prize financial resilience first, scan a list of solid balance sheet and fundamentals (25 results) that can help support operations through tougher periods.
- If you focus on finding quality at a sensible price, sort through a 33 high quality undervalued stocks that may align more closely with your return targets and risk tolerance.
- For those who care about steady cash returns, weigh up a 6 dividend fortresses that offer income while you wait for the thesis to play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com