


EN
Is Airbnb (ABNB) Fully Valued As New Guidance And A $12b Buyback Lift Expectations?
Why Airbnb’s New Guidance Matters Now
Airbnb (ABNB) reset expectations on 5 November 2026, pairing a fresh earnings outlook with a sizeable share repurchase plan that gives investors new data on growth, profitability, and capital allocation priorities.
Airbnb’s recent guidance update and fresh US$12b buyback come after a strong run, with the share price up 43.06% year to date and a 1 year total shareholder return of 58.31%. However, the 5 year total shareholder return still shows an 8.17% decline, which keeps longer term holders more measured about momentum building only over the last couple of years.
Scan beyond Airbnb and review other travel and platform stocks that match this earnings plus buyback setup using our curated list of 19 high quality undiscovered gems.
Airbnb is trading near fresh highs after the guidance lift and new US$12b buyback, so the real tension is simple: do you pay up today or wait for a pullback that may not show?
Most Popular Narrative: 4.6% Overvalued
Airbnb closed at $190.29 compared with a narrative fair value of $181.84, which frames the current valuation premium before exploring what is driving the story.
This narrative was written by TickerTickle, an investor in the Simply Wall St Community, who argues that recent execution finally gave the market a clear reason to re-rate Airbnb.
Airbnb generated about $4.8 billion of free cash flow over the last twelve months, equal to roughly a 37% FCF margin. They also repurchased another $1.1 billion of stock during Q2. Since Airbnb started buying shares back in 2022, fully diluted share count has fallen around 10%.
See why 90 investors see Airbnb as 5% overvalued.
Result: Fair Value of $181.84 (OVERVALUED)
Still, Airbnb’s narrative could be knocked off course if tougher short term rental rules hit key regions or if the US$1.3b IRS dispute ends unfavourably.
Find out about the key risks to this Airbnb narrative.
Another View: Airbnb Through The DCF Lens
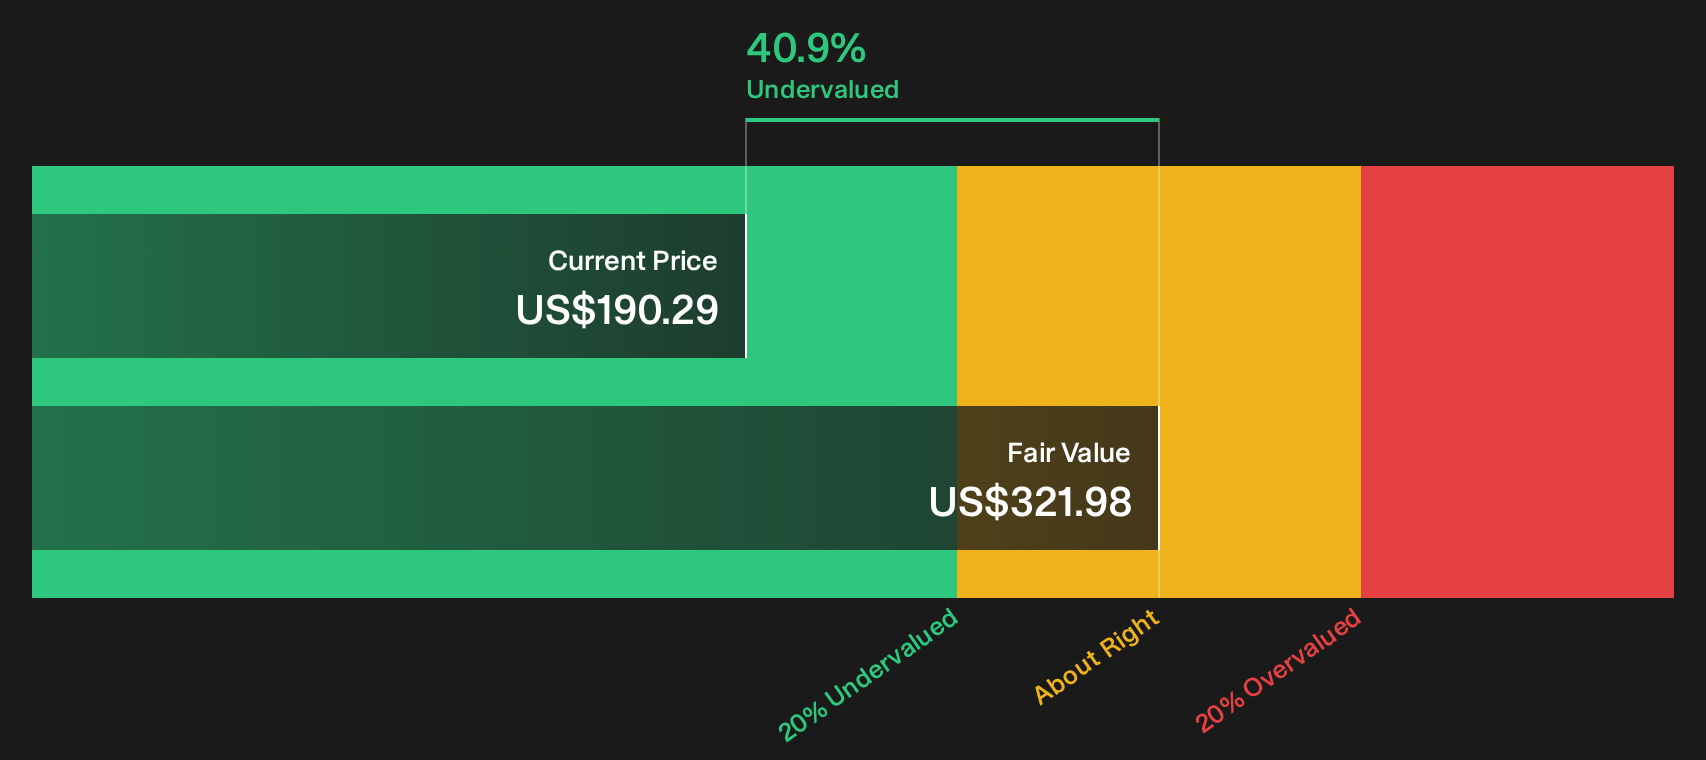
The community narrative pegs Airbnb at a fair value of $181.84 and calls the stock 4.6% overvalued, yet our DCF model points in the opposite direction. At $190.29, Airbnb is trading 40.9% below an estimated future cash flow value of $321.98, which frames the shares as undervalued instead.
That gap is large enough to matter in real money terms. The real question for you is simple: Which story feels more reasonable, the crowd’s earnings-multiple-based view or a cash flow model that leans much more heavily on long term assumptions?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Airbnb for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the split views on Airbnb yet? Act while the data is fresh, compare the upside signals yourself, then weigh what investors like in the 3 key rewards.
Looking For More Investment Ideas Beyond Airbnb?
Airbnb gives you one compelling case study, but your portfolio can also include a range of contenders built from different balance sheets, income streams, and risk profiles.
- Review companies screened for resilient finances and earnings quality in our list of solid balance sheet and fundamentals (25 results).
- Explore potential mispricing opportunities in the 33 high quality undervalued stocks that combine strong fundamentals with discounted market expectations.
- Build your watchlist with companies that may be earlier in their journey by examining our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com