


EN
Missed Piaggio & C's Run? Here Is What Changed
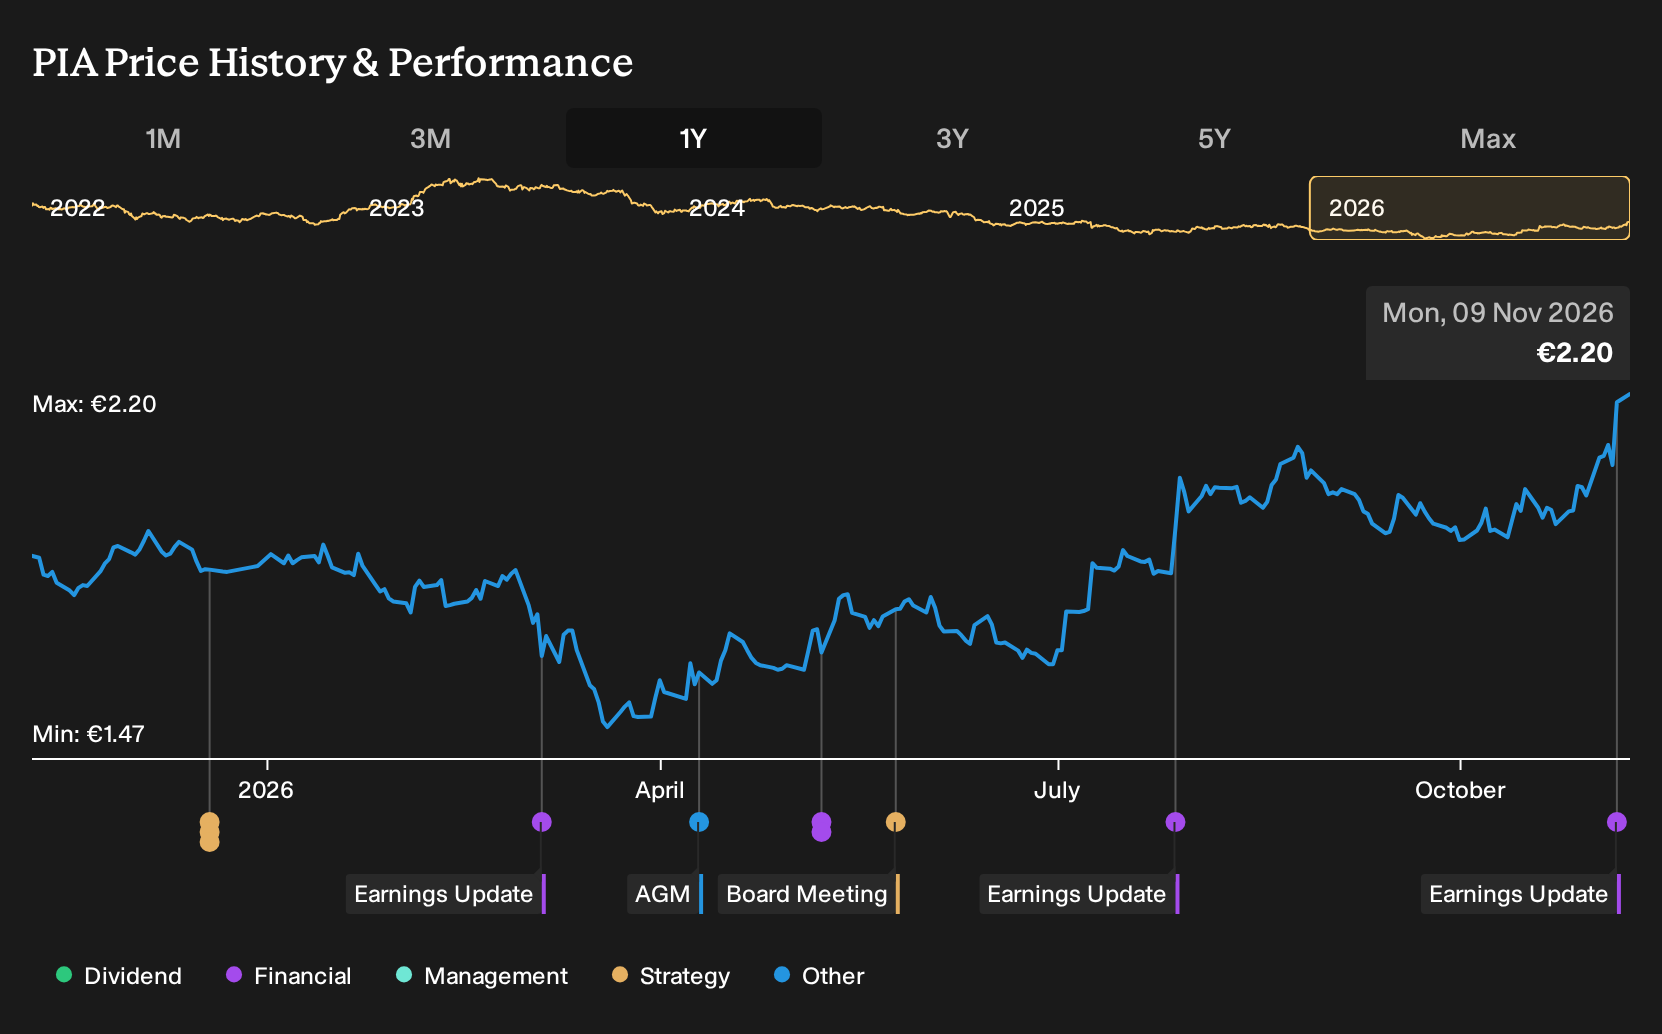
Piaggio & C closed Q3 2026 with €351.804 million in revenue and €6.836 million in net income on record, figures that left a very different impression than the muted Q3 2025 baseline. Holding Piaggio & C over the past year would have returned 23.1%, including dividends. If you had been deciding on 9 November 2025, what would you have needed to believe about future margins and urban mobility demand to act with confidence?
If the move has made Piaggio & C harder to judge, start where the gap is still open and scan 200 high quality undervalued stocks.
The Two Piaggio & C Stories Investors Had To Hold In Their Heads
The shares cost €1.85 at the start of the period, and investors in Piaggio & C were effectively choosing between two sharply different stories.
On the bullish side, the optimistic case pointed to a Fair Value of €4.1, the price implied if its urban electrification and premium mobility thesis played out. That view leaned on faster revenue expansion from new models, plus higher margins supported by electric, robotics, and digital offerings.
The bearish narrative instead anchored on a Fair Value of €1.6, the price implied if tighter regulations and weak electric vehicle profitability weighed on results. It highlighted shrinking demand in key regions, reliance on subsidies in India, and pressure from lower cost Asian competitors as core risks.
What The Results Changed For Piaggio & C
Q3 2026 put hard numbers on both stories. Piaggio & C reported revenue of €394.44 million and net income of €6.836 million, with net margin at 1.7% versus 0.4% a year earlier. Profitability moved closer to the optimistic margin thesis, yet the still low margin level kept the cautious view on long term earnings power alive. The evidence cut both ways.
The lesson to take elsewhere is simple. When a bullish pitch leans on better margins, track the actual net margin line each quarter and test whether it is moving toward that narrative or stalling well short.
What Piaggio & C's Recent Run Already Prices In
Piaggio & C trades at €2.2 after returning 23.1% over the past year, while the bearish analyst Narrative on Simply Wall St places its Fair Value below that level based on its own set of assumptions.
The Narrative focuses on heavy CapEx, premium positioning and limited valuation slack. A buyer today has to judge whether ongoing investment really sustains pricing power that is strong enough to cover regulatory, tariff and FX pressures.
"The main thing that has to go right is that Piaggio & C converts heavy annual CapEx and product investment into sustained demand and pricing power strong enough to offset regulatory, tariff and FX headwinds."
One Narrative disagrees with today's price. → See where this Narrative says Piaggio & C should trade
Where Piaggio & C’s Theme Echoes
Piaggio & C is wrestling with what mobility looks like next. You could look one step further out.
Somewhere else, another player is treating transport as a side effect of software and automation. Its pitch is not just moving people, but monetising how machines think and work.
This other business builds electric vehicles, yet its bigger story sits in robotics and AI. Hardware carries the idea, recurring software and services carry the economics.
If that shift takes hold, your Piaggio & C questions widen. How far could mobility stretch once cars, taxis and even factory shifts are all software problems?
That argument has a Narrative and a number behind it. → See the company one Narrative values 76% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com