


EN
What Just Happened With Jackson Financial (JXN)?
Jackson Financial (JXN) drew fresh attention after releasing third quarter 2026 results that showed higher revenue and a sharp jump in net income, alongside new preferred and common dividend declarations.
Those quarterly numbers and fresh dividend declarations landed alongside a share price of $135.51, with a 1-day share price return of 2.90% and a year to date gain of 26.10%, while total shareholder return over the past year reached 50.25% and extended to very large multi year gains of around 4x over five years, which indicates momentum that has been building rather than fading.
Spot momentum in Jackson Financial, then scan for other financials showing strong returns and active capital returns using our curated 6 dividend fortresses.Jackson Financial now carries a much higher share price and far stronger recent earnings. The real tension is simple: does that combination still leave room for value, or has the stock already done the heavy lifting?
Most Popular Narrative: 9% Undervalued
Against a last close of $135.51, the analyst consensus Narrative on Simply Wall St anchors Jackson Financial’s fair value at $148.50. This implies a modest valuation gap and puts the focus on whether its capital engine can keep doing the work.
The main thing that has to go right is that Jackson continues to turn strong statutory capital generation, its contingent capital facility and large liquidity buffers into reliable cash flows, without the emerging hedging and captive reinsurance scrutiny undermining confidence in Brooke Re or Jackson National Life.
See why 22 investors see Jackson Financial as 9% undervalued.
Result: Fair Value of $148.50 (UNDERVALUED)
Still, the narrative around Jackson Financial could shift quickly if scrutiny of its Brooke Re hedging structure deepens or if weaker private credit returns squeeze spread income.
Find out about the key risks to this Jackson Financial narrative.
Another View: Cash Flows Paint A Harsher Picture For Jackson Financial
While the analyst fair value for Jackson Financial sits at $148.50 and points to a modest undervaluation, the Simply Wall St DCF model is far more conservative. On that measure, JXN at $135.51 trades well above an estimated future cash flow value of $60.92, which frames the stock as expensive if those cash flow assumptions hold.
This split between earnings based targets and cash flow driven value puts the burden on you as an investor. Which lens do you trust more when the story and the spreadsheet disagree so sharply?
Look into how the SWS DCF model arrives at its fair value.
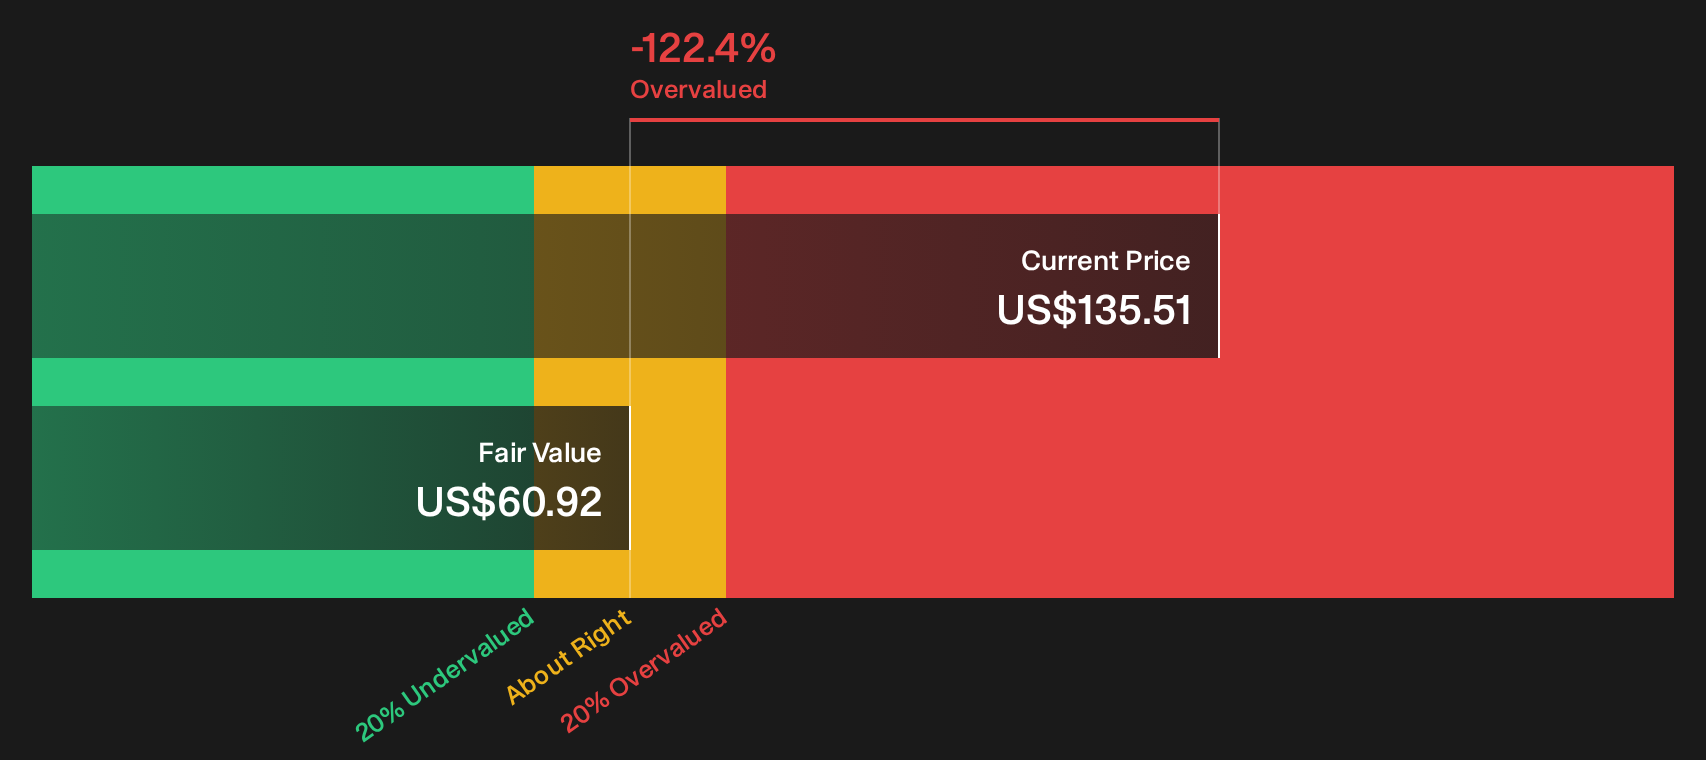
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jackson Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data can feel uncomfortable, especially with a stock like Jackson Financial that splits opinion on value and risk. Step into the detail yourself, weigh the concerns against the potential upside, and size your own conviction using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Jackson Financial?
Do not stop your research with Jackson Financial. Fresh opportunities often sit just outside your current watchlist, and a few minutes of focused screening can surface them.
- Target dependable cash generators by reviewing companies that feature in our 6 dividend fortresses for income that might complement your existing positions.
- Hunt for potential mispricing by scanning the 19 high quality undiscovered gems and see which quieter stocks pair quality fundamentals with under-the-radar coverage.
- Prioritise resilience in tougher conditions by filtering for companies on the 30 resilient stocks with low risk scores, where balance sheets and risk scores do more of the heavy lifting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com