


EN
ETF Launches Could Be A Game Changer For Lazard (LAZ)
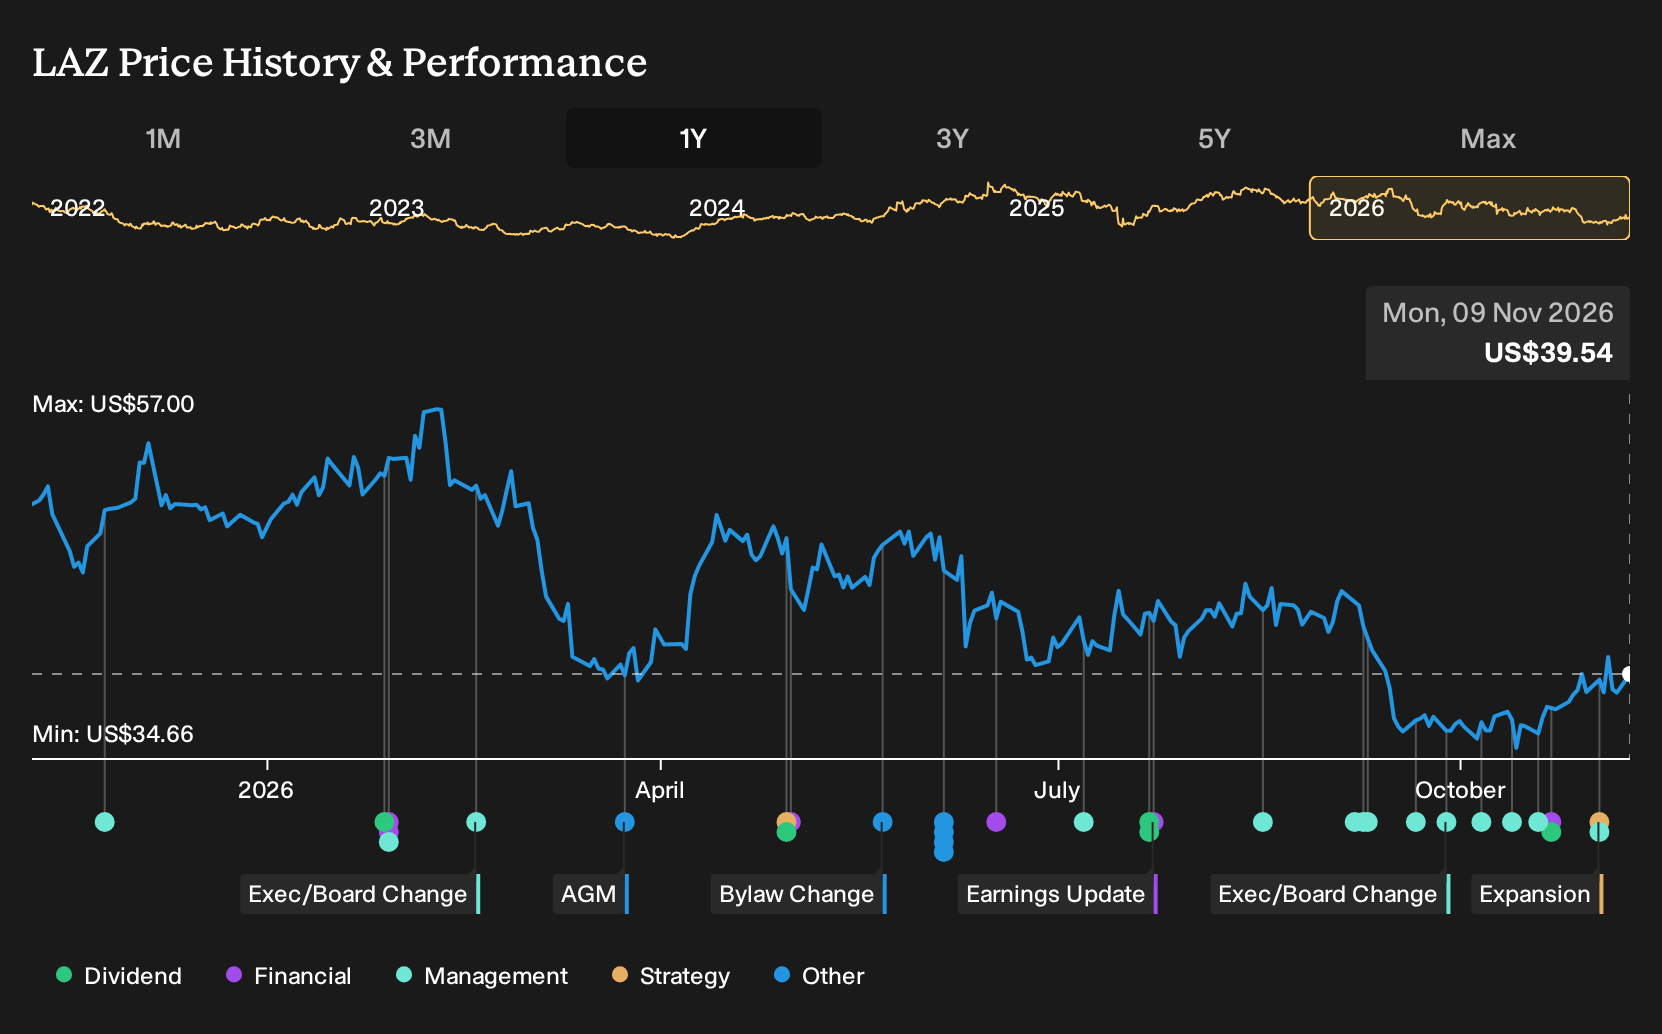
- Lazard completed its acquisition of Campbell Lutyens to form Lazard CL and also launched three actively managed fixed income ETFs, deepening its presence in private capital advisory and listed income products.
- The combination of a large dedicated private capital advisory platform and an expanding ETF suite indicates a broader fee mix and more diversified earnings drivers for Lazard.
- Next, the focus shifts to how Lazard's expanding fixed income ETF range could reshape its investment narrative for long term investors.
Scan Lazard's move into private capital advisory and fixed income ETFs against a wider opportunity set by reviewing the hand picked 19 high quality undiscovered gems now shaping similar themes in public markets.
Lazard Investment Narrative Recap
To own Lazard, you largely need to believe the firm can turn its rebuilt advisory franchise, private capital focus and asset management repositioning into steadier fee income and a lower compensation ratio. The analyst consensus Narrative on Simply Wall St leans on earnings forecasts that assume this mix shift works. The short term swing factor remains whether deal activity, fundraising and AUM flows support that fee pool.
The biggest risk right now is that Lazard carries a high compensation ratio and a meaningful debt load while margins have compressed and one off items have hit earnings. If private capital advisory, ETFs and AI enabled productivity do not translate into better profitability, that pressure on earnings and dividend coverage could linger.
The creation of Lazard CL through the Campbell Lutyens acquisition sits in the middle of the catalysts analysts are watching. Management has outlined about US$500 million of potential combined revenue in 2027 from this platform, and the analyst consensus Narrative on Simply Wall St builds in a larger share of advisory fees tied to private capital.
For shareholders, Lazard CL is less about headlines and more about execution risk. The enlarged team and datasets broaden the opportunity set, but if fundraising or secondary volumes disappoint or integration proves costly, the hoped for diversification and operating leverage could fall short and leave earnings and the P/E rating under pressure.
Lazard's current analyst narrative points to revenues of US$4.6b and earnings of US$501.8m by 2029, built on assumed revenue growth of 12.6% a year and an earnings increase of about US$282.8m from US$219.0m today.
Uncover why Lazard's fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest analysts focus less on Lazard CL as a growth engine and more on the risk that high pay costs keep biting. They were working off roughly US$4.4b of 2029 revenue and about US$544.3m in earnings, yet still saw value capped. You can treat those pre news views as one possible, more cautious script that may now shift.
Explore 4 other Lazard fair value estimates, including one that suggests as much as 24% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lazard research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Lazard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lazard's overall financial health at a glance.
Looking for more investment ideas beyond Lazard?
If Lazard's story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you line up other candidates that fit how you like to invest.
- If quality at a discount is your priority, scan a curated set of companies that currently screen as attractively priced with strong fundamentals through 33 high quality undervalued stocks.
- If capital preservation and smoother ride potential matter more to you, filter for businesses that show up in our 30 resilient stocks with low risk scores and compare how their profiles differ from Lazard.
- If you care most about balance sheet strength, start with a list of solid balance sheet and fundamentals (25 results) and look for businesses that pair financial resilience with business models you understand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com