


EN
SK hynix (NasdaqGS:SKHY) Stock May Be Reasonable On Export License Delays
SK hynix has seen a sharp pullback over the past month, and that slide is now colliding with big expectations built on its earnings power. With memory chips at the center of recent headlines, the question for investors is whether today's valuation still lines up with what the business is currently earning.
- The share price has fallen about 20.5% over the past month, which puts fresh pressure on the case that the current multiple on SK hynix's earnings is still appropriate.
- Recent news around record profitability, heavy AI related demand for high bandwidth memory and large planned investments means the timing and durability of future earnings may matter more than ever for how this stock is priced today.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
The stock's next move may depend on whether SK hynix's current share price can be squared with the earnings investors are paying for right now.
To see whether SK hynix's recent slide and earnings-driven story represents a broader pattern or a one-off exception, compare it directly with 53 AI infrastructure stocks.
Does SK hynix Look Undervalued on Earnings?
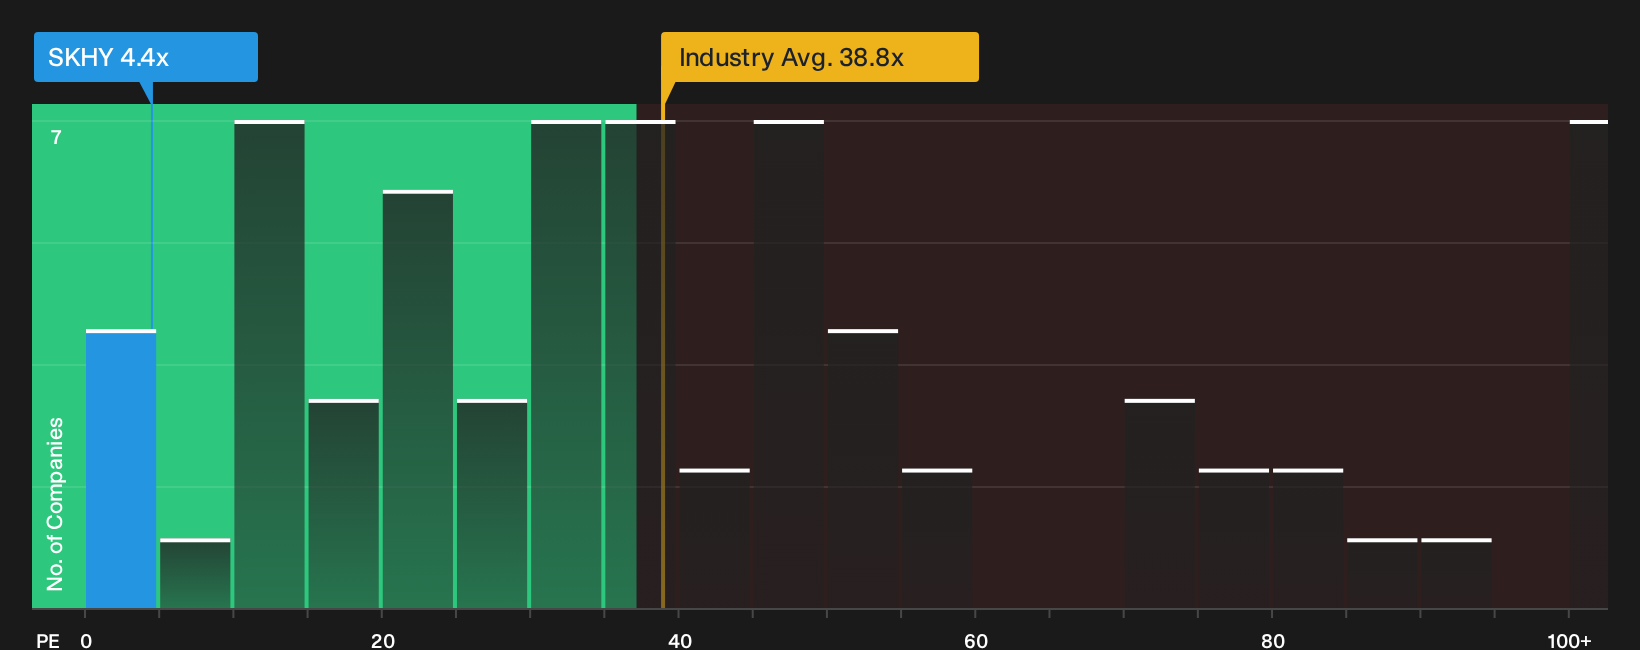
The P/E lens fits SK hynix because earnings are now a key reference point for how investors frame the memory cycle. On this measure, the stock trades on a P/E of 4.4x, far below the broader semiconductor sector at about 38.8x and well under the peer group around 45.0x. That gap flags a steep earnings discount, even after the recent pullback in the share price.
Because SK hynix has reported very strong recent results tied to AI related demand, such a low multiple suggests the market is baking in meaningful risk around the durability or volatility of those profits. For you as a shareholder or prospective buyer, the question is whether export license delays on its planned US$45b New York chip investment justify such a large gap to industry P/E levels, or whether the current price offers compensation for those uncertainties. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Narratives for SK hynix pick up where the P/E puzzle leaves off, spelling out what kind of path for growth, margins and earnings would need to play out for the share price to sit meaningfully above or below today's level, and they sit on Simply Wall St's Community page. Where a single ratio or model gives you one valuation figure, these narratives lay out the future that figure leans on so you can judge over time whether SK hynix's reality still matches the story.
One of the top community narratives on SK hynix: 64% undervalued
According to MarkoVT, a Simply Wall St Community investor who wrote the Narrative, SK hynix may warrant a closer look on both cash flow and spending.
"Numbers appear to be explosive, however, the 'high level of non-cash earnings' flag is driven by a massive, one-off non-operating investment asset valuation and disposal gain…"
Discover why this Narrative puts SK hynix at 64% undervalued.
One more SK hynix check that belongs beside the price tag
Valuation only tells part of the story, because internal checks on SK hynix have also flagged specific risk indicators that deserve space in your thinking before you decide what to do next. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com