


EN
AI trading “made matters worse”! The US CPI wiped out signs of a rebound, and the Federal Reserve raised interest rates by 50 basis points in December
The Zhitong Finance App learned that the US CPI in October exceeded expectations, further pushed the Federal Reserve to raise interest rates, and reignited discussions on the “50 basis point rate hike”. The Bureau of Labor Statistics announced on Tuesday that the overall CPI rose 0.4% month-on-month, although down from 0.6% in September, higher than market expectations of 0.3%; the core CPI excluding food and energy rose 0.3% month-on-month, higher than the expected 0.2%, which is the same as the previous value. This is the last CPI report we can see before the Federal Reserve's December 8-9 meeting.
After the data was released, US bond yields jumped, and the three major US stock indices opened and fell. The 2-year US Treasury yield jumped about 12 to 15 basis points above 4.68%, and the 10-year bond rose more than 7 basis points to around 4.94%; the US dollar strengthened, and spot gold fell more than 1.5% at one point. Just a day ago, the S&P 500 just recorded its biggest one-day increase since April.
The core month-on-month pass is 0.3%, which is exactly on the threshold mentioned by Waller
Overall CPI: 0.4% in October, expected 0.3%, previous value 0.6%; core CPI: 0.3%, expected 0.2%, previous value 0.3%. What needs to be specified is that the year-on-year will not be published this month — during the federal government shutdown in October 2025, the Bureau of Labor Statistics was unable to collect price data, lacked a comparable base period, and only published the month-on-month ratio. The most recent comparable year-on-year reading was 3.7% in September.
The breakdown shows that pressure is still spreading: groceries rose 0.4% month-on-month, the biggest increase since April; entertainment and medical prices rose 0.9%; air tickets rose 0.4%, and takeout delivery service prices also rose — all suggest that the energy shock is still penetrating the rest of the economy. Equivalent rents for landlords rose 0.3%. Gasoline rose 1% month-on-month, although international oil prices fell sharply in the past week due to expectations of a cease-fire in the Middle East.
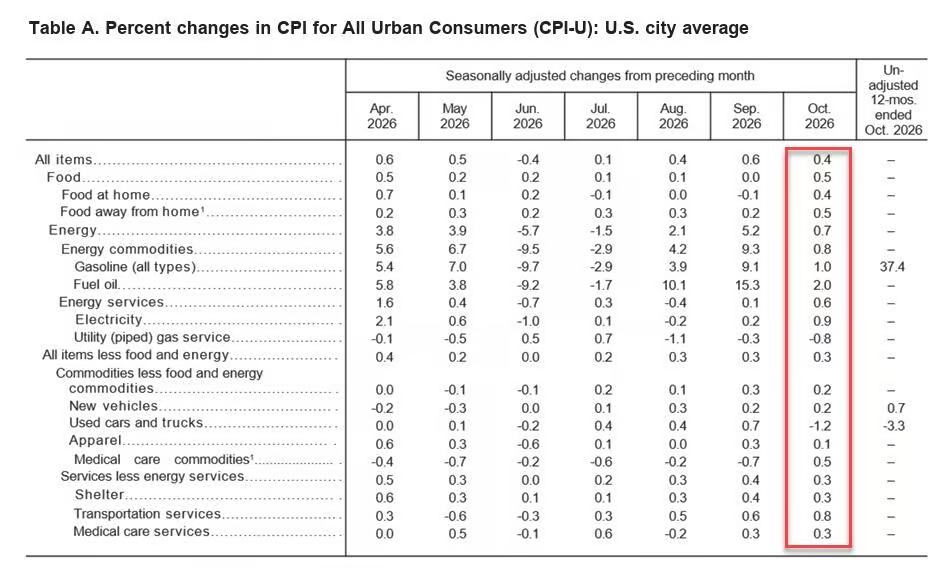
What is more indicative of the trend is the annualized scale: as of October, the core CPI rose 3.7% annualized for three months and 2.7% annualized for six months. The near end is faster than the far end, which indicates that inflationary pressure is not fading away, but is gathering again.
The report also has a clear political footnote: price pressure continued to build up just before the midterm elections, the Democratic Party took back both houses of Congress using the cost of living as the main axis, and the Republican Party's fiasco was generally attributed to high inflation.
Inflation: The three major fires have not been extinguished, and energy transmission is probably still to come
There are three types of inflation this year: the war in Iran that broke out in February pushed up energy prices, the Trump administration's import tariffs, and a boom in data center construction. None of the three went out naturally.
The latest trend on the energy side is “oil prices are falling, gas prices are not falling.” Brent crude fell below $90 on Tuesday for the first time since August; Trump said the war with Iran could end “soon” and that further crackdowns are no longer necessary, but the US is still “waiting hard.” However, the transmission chain is lagging behind: According to the American Automobile Association (AAA) data, the average price of gasoline was $4.32 per gallon in October, down only slightly from $4.34 in September, and still about 34% higher than before the outbreak of the war in Iran. Economists are worried that the sharp rise in energy prices over the past few months may be yet to be transmitted to a wider range of goods and services — energy-intensive industries are already showing pressure, and companies that buy fuel in large quantities are shifting costs.
The upstream evidence is also not optimistic: the producer price index (PPI) rose 6.3% year on year in September, the biggest increase in more than three years; Federal Reserve Governor Waller quoted Federal Reserve employees' analysis as saying that there will be more producer-side price increases in the future, and the energy shock may last longer than initially anticipated. The PCE price index tracked by the Federal Reserve is not affected by last year's lack of data. The overall and core are currently above 3% — far above the 2% target.
There is another side evidence at the micro level: according to the NFIB small business survey released on the same day, 37% of net owners plan to raise prices over the next three months, the highest in more than four years. Small businesses are the “last link” price makers in the service sector, and their intention to raise prices is more indicative of the direction of core service inflation than CPI itself.
Brian Jacobsen, chief economic strategist at Annex Wealth Management, said that the core CPI rate once again reached 0.3% per month. The problem is not only that the overall CPI is still high, but the impact on oil prices has also been transmitted to core inflation. Chicago Federal Reserve Chairman Goulsby did not have the right to vote this year, but when he pointed out that AI demand may be a factor that the Federal Reserve needs to curb, he probably represented the views of many Federal Reserve officials.
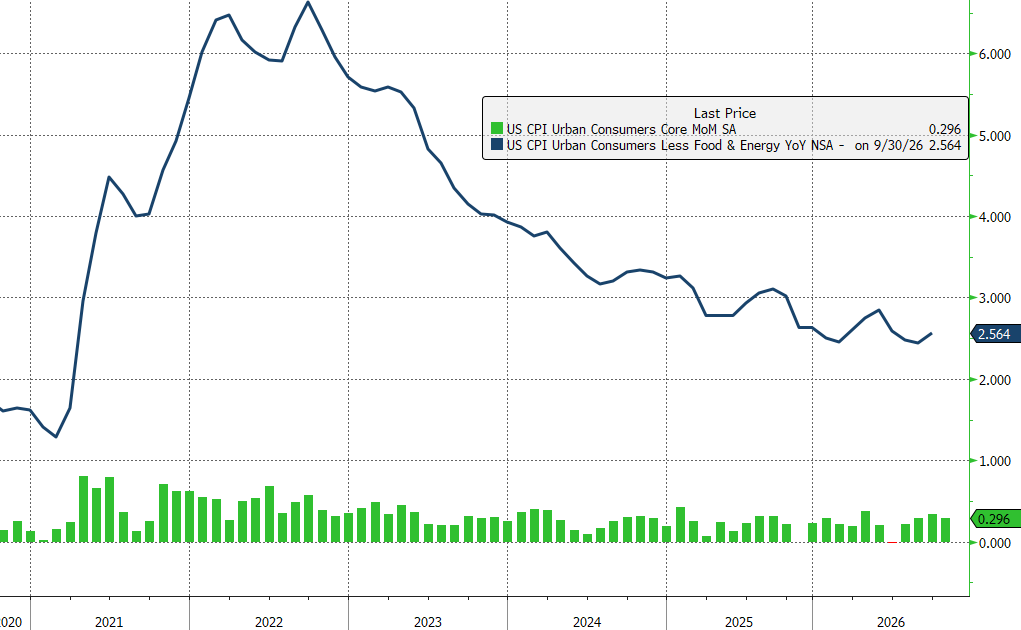
Furthermore, Federal Reserve Governor Waller said he might support a larger rate hike. The Federal Reserve may now be more concerned that demand for AI investment will crowd out resources from other economic activities and push up prices. Leaving aside oil prices, the Federal Reserve's new concern may be rising employment costs for skilled jobs such as plumbers and electricians.
Federal Reserve: The pricing of 25 basis points is almost complete, and 50 basis points are on the table
The policy context is a clear channel for interest rate hikes. The Federal Reserve voted to raise interest rates by 25 basis points at 12:0 in September, raising the federal funds rate target range to 3.75% — 4.00% for the first time since July 2023; the October meeting remained unchanged by a 10:2 vote. The two directors advocated continuing to raise interest rates, and a statement acknowledged that “inflation is still high.” Before the December 8-9 meeting, the non-agricultural sector added 165,000 new people in October, and the unemployment rate fell to 4.1%. The employment side is no longer a constraint at all — CPI is the last variable.
The real flashpoint was laid before the data was released. Federal Reserve Governor Waller said earlier on Tuesday that he would have preferred a 25 basis point hike in December; if the core CPI reached 0.3% or higher month-on-month — “I think we should consider raising interest rates by 50 basis points at the December meeting. Adding just 25 basis points would put our reputation at risk, a risk I don't want to take.” He also said that Federal Reserve employees' analysis shows that production-side prices will rise in the future, and the energy shock may last longer. He is particularly concerned about the extent of the price increase.
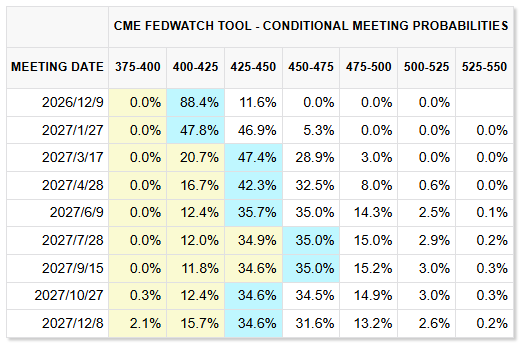
October's core CPI fell at just 0.3% — right on the threshold Waller had drawn. After the data was released, traders increased their bets on the December rate hike by 50 basis points and further increased the pricing for at least two more rate hikes before mid-2027. Previously, the market had fully taken into account the December interest rate hike of 25 basis points (the probability rose to about 100% after Waller's statement).
Skyler Weinand, chief investment officer of Regan Capital, said that the CPI data released on Tuesday was stronger than expected, laying the foundation for the Federal Reserve to raise interest rates again in December. Obviously, the Federal Reserve cannot ignore the fact that inflation data has clearly rebounded. Voters expressed dissatisfaction with inflation and rising prices in the midterm elections, so the Federal Reserve must act to curb the further rise in inflation by raising interest rates. The recently released employment report shows that employment growth in the US was strong in October, and the data for the previous few months was also revised up, which provided a basis for the Federal Reserve to continue to raise interest rates. Obviously, the Federal Reserve can raise interest rates a little more without harming the labor market to calm inflation, because the labor market is already well-rooted.
However, Natixis analyst Christopher Hodge cautioned that Waller's statement only represents his own, and does not necessarily represent the position of other board members or Federal Reserve Chairman Walsh — Walsh's style is to see continuous, complete, and cross-verified trends before acting, and not rely on month-long, flawed isolated data to make major policy adjustments. Second, most agencies (including the interpretations of Goldman Sachs and Morgan Stanley) still believe that given the lack of comparison in this CPI and the existence of monthly coincidences, the Federal Reserve is likely to prioritize 25 basis points in December and will not easily add 50 basis points in one step.
Goldman Sachs Asset Management's Lindsay Rosner put it most bluntly: “CPI continues to be strong, and the Federal Reserve may pursue a more aggressive cycle of austerity. The December rate hike is our firm benchmark situation — despite the AI market's turbulence — and stubborn inflation means further rate hikes in 2027 cannot be ruled out.”
There are also reverse variables: oil prices fell below $90 and the Middle East armistice progressed. It was this line that pulled the stock market back on Monday. Economists say that only a sharp sell-off in the stock market or a significant widening of credit spreads can stop the Federal Reserve from tightening in December.
AI trading: After only a day of rebound, CPI came out to smash the market
For the AI sector, this CPI came at the least time. Last week's script was politics: After the Democratic Party fully won the midterm elections, the market feared that the new government's regulation of data centers and AI infrastructure would drive up costs and limit construction, and AI-related stocks suffered a severe setback — CoreWeave fell 15% in a single week, 65% from a six-month high, and “new clouds” such as Nebius and IREN plummeted at the same time, and the yield of some new cloud bonds rose 15% and fell into a difficult range; the Texas governor elected has called for the immediate suspension of data center projects. The screenplay for Monday was moderation: the sharp drop in oil prices led the S&P 500 to record its biggest one-day increase since April. The NASDAQ 100 surged more than 3%, and AI trading seemed to have taken a breather.
Then, today the script was exchanged for interest rates. The CPI surpassed expectations, and the three major US stock indices opened and fell. The 2-year US bond yield jumped more than 12 basis points to 4.70%, and the market raised the cumulative interest rate hike expectations until mid-2027 even higher. For long-term, high-multiple AI targets, this is not an abstract macro background, but a direct rise in discount rates — in particular, one of the flames of the current round of inflation is AI's own data center construction boom. AI capital expenditure drives up inflation, and inflation leads to interest rate hikes, and interest rate hikes suppress AI valuations. This negative feedback is the closed loop that the market is most worried about right now.
The next two points of observation are almost connected. First, after the market tonight, CoreWeave released earnings reports. The options market implied a one-day fluctuation of about 18% — the market originally debated regulation and debt, but now it still has to add “interest rates to the next level.” Second, Anthropic's IPO pricing on November 18: The company has just given a fully diluted valuation of about 1.4 trillion US dollars in its prospectus and is seeking a total funding of up to $90.4 billion. Investors were already forced to judge whether AI valuation is a reasonable path or excessive confidence. Now the pricing window just hits the “at least two more interest rate hikes” path.
Goldman Sachs Asset Management's Rosner pinned two things into the same sentence: the December interest rate hike was the benchmark situation, “despite the turbulence of the AI market.” Translated into transactional language: What AI trading now has to hedge against is more than just regulation.