


EN
Johnson & Johnson (JNJ) Shares Just Moved, So What Is Driving Attention Now?
Johnson & Johnson (JNJ) is back in focus after early Phase 1 data on its pasritamig and JNJ-9401 antibody combo in advanced prostate cancer, raising fresh questions about how this oncology program fits into the stock’s long-term story.
All of this lands against a strong run in Johnson & Johnson’s own shares, with the US$282.11 price sitting on the back of a 7.91% 30 day share price return and a 36.05% year to date share price gain, alongside a 53.11% 1 year total shareholder return and more than a doubling of total shareholder return over three years, as oncology, immunology and MedTech updates keep feeding into how investors weigh both future opportunity and execution risk.
Scan how Johnson & Johnson's momentum in oncology and immunology compares with peers by reviewing a curated list of 36 healthcare AI stocks in the wider healthcare space.
Bulls view Johnson & Johnson’s run as a rerating supported by its pipeline. Bears point to a crowded oncology field, ETF selling and guidance risks. Which story does the current valuation actually align with next?
Most Popular Narrative: 17% Overvalued
Against Johnson & Johnson's last close at $282.11, the most followed narrative anchors fair value at $240.69. This frames the recent share price strength as running ahead of that estimate according to LunaRodas, an investor in the Simply Wall St Community who wrote the narrative.
Johnson & Johnson is a step from a milestone it has chased for three months: $100 billion in annual revenue, a first in its 140-year history. But the quarter that gets it there is also the one in which MedTech management labels its own performance as falling short of the standard it set for itself, a tonal admission more direct than the prior call's softer version, even as the same underlying businesses were already softening.
See why 5 investors see Johnson & Johnson as 17% overvalued.
Result: Fair Value of $240.69 (OVERVALUED)
Still, this 17% premium rests on a MedTech segment that management itself describes as underperforming, along with oncology assets operating in a crowded competitive field.
Find out about the key risks to this Johnson & Johnson narrative.
Another View: Cash Flow Says Undervalued
The community narrative pegs Johnson & Johnson at $240.69, which frames the current $282.11 share price as 17% rich. Our DCF model presents an estimated future cash flow value of $471.87, which implies that JNJ trades at a 40.2% discount instead.
This gap between a narrative fair value and a cash flow driven model raises a simple question for investors: Is the story too cautious, or are the DCF assumptions too generous?
Look into how the SWS DCF model arrives at its fair value.
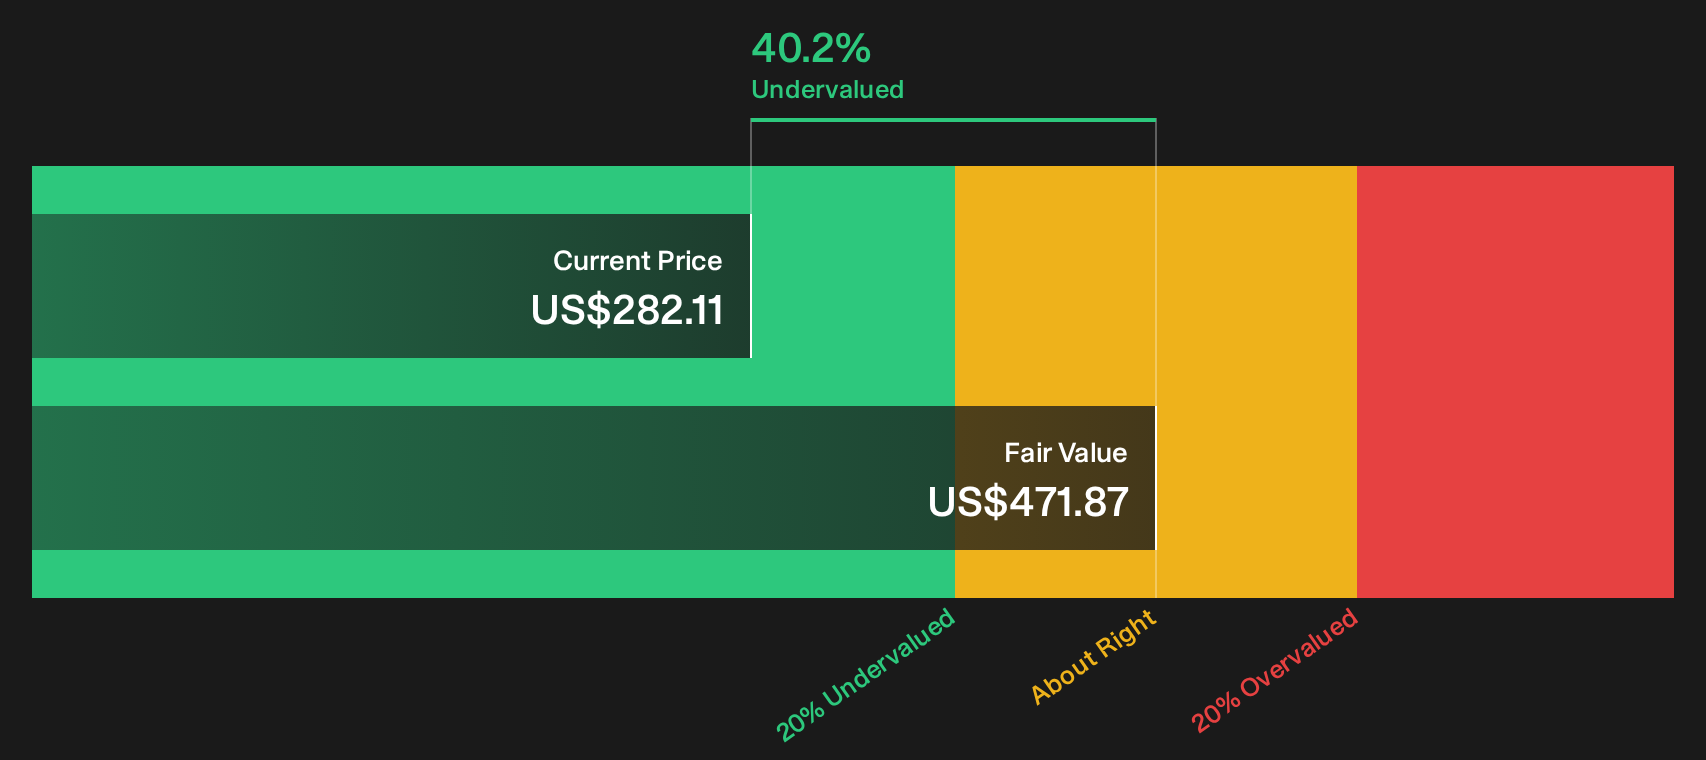
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Johnson & Johnson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in Johnson & Johnson is clearly split, with strong past returns on one side and pointed questions on execution and valuation on the other. Act while the debate is still live and weigh the trade off between opportunity and risk for yourself using the 3 key rewards and 2 important warning signs.
Looking for more Johnson & Johnson sized investment ideas?
Do not stop with Johnson & Johnson. Use the Simply Wall St screener to source fresh opportunities before everyone else is talking about them.
- Target stronger income potential by reviewing companies screened as 6 dividend fortresses and compare their payouts with the cash flows behind them.
- Hunt for mispriced quality and study a curated group of 33 high quality undervalued stocks that combine fundamentals with discounted market pricing.
- Prioritise resilience first by filtering for 30 resilient stocks with low risk scores that pair sturdier balance sheets with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com