


EN
Glacier Bancorp (GBCI) Could Be 12% Undervalued Following Its $200 Million Buyback Plan
Glacier Bancorp (GBCI) has introduced a new US$200 million share repurchase plan, authorized by its Board of Directors and running through the end of 2027, giving investors a new capital return signal.
Glacier Bancorp’s new buyback plan lands after a sharp 14.86% 1 month share price return and a 9.95% share price gain year to date to US$49.08. Total shareholder return of 19.01% over one year and 72.23% across three years points to momentum that investors are already rewarding over time.
Scan how Glacier Bancorp’s buyback compares with peers by reviewing hand-picked banks and lenders in the list of solid balance sheet and fundamentals (25 results) that are also returning cash to shareholders.
Glacier Bancorp is now buying its own shares after a strong run, which puts you at a fork in the road. Is this the moment to step in, or does waiting for a potentially cheaper entry make more sense once valuation is on the table next?
Most Popular Narrative: 12% Undervalued
Glacier Bancorp’s last close at $49.08 sits below the analyst consensus Narrative on Simply Wall St, which places fair value near $55.83 based on projected earnings and margins under a 7.24% discount rate.
Analysts expect Glacier Bancorp to continue translating margin expansion, improving efficiency, and the 2025 acquisitions into further earnings growth that is not yet fully reflected in reported results. The current valuation implies that the market is discounting Glacier Bancorp’s recent net interest margin gains, efficiency ratio improvement, and earnings growth. This supports the view that the stock may be undervalued and that the narrative remains positive.
See why 4 investors see Glacier Bancorp as 12% undervalued.
Result: Fair Value of $55.83 (UNDERVALUED)
Still, the Glacier Bancorp story depends heavily on net interest margin remaining resilient, as well as on loan and deposit growth not drifting into lower quality or lower yielding segments.
Find out about the key risks to this Glacier Bancorp narrative.
Another View On Glacier Bancorp’s Valuation
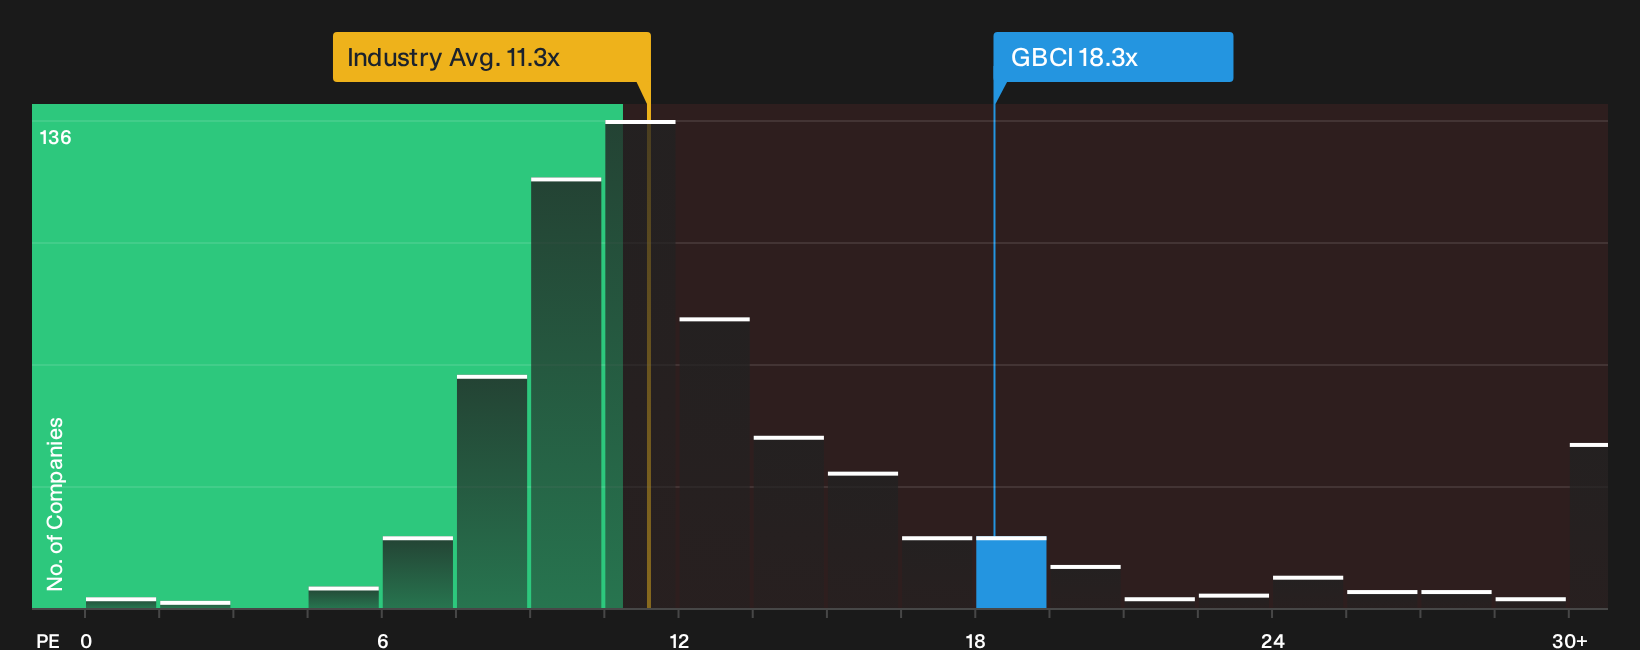
The first narrative leans on discounted future earnings and a fair value near $55.83. A simpler yardstick tells a different story. Glacier Bancorp trades on a P/E of 18.3x, compared with 11.3x for the broader US banks group, a peer average of 11.2x, and a fair ratio of 14.4x that the market could move toward. That premium suggests investors are already paying up, so the key question is whether the earnings path justifies that higher multiple or leaves less room for error.
For a closer look at how this earnings based view stacks up against the implied price today, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether Glacier Bancorp’s momentum really lines up with the story so far? Put the numbers side by side, weigh the trade offs, and then check the 3 key rewards and 1 important warning sign.
Looking for more Glacier Bancorp sized investment ideas?
If Glacier Bancorp has sharpened your focus, do not stop there. Spread your research across other opportunities so one ticker never dictates your whole outcome.
- Target resilient uptrend potential by scanning a curated set of underpriced opportunities in the 33 high quality undervalued stocks that pair quality fundamentals with appealing entry points.
- Strengthen income potential by lining up your watchlist with the 6 dividend fortresses, highlighting businesses that currently offer higher yields backed by solid metrics.
- Reduce portfolio stress by filtering for sturdier financial footing using the 30 resilient stocks with low risk scores, which focuses on companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com