


EN
Raised Outlook Might Change The Case For Investing In Nojima Stock (TSE:7419)
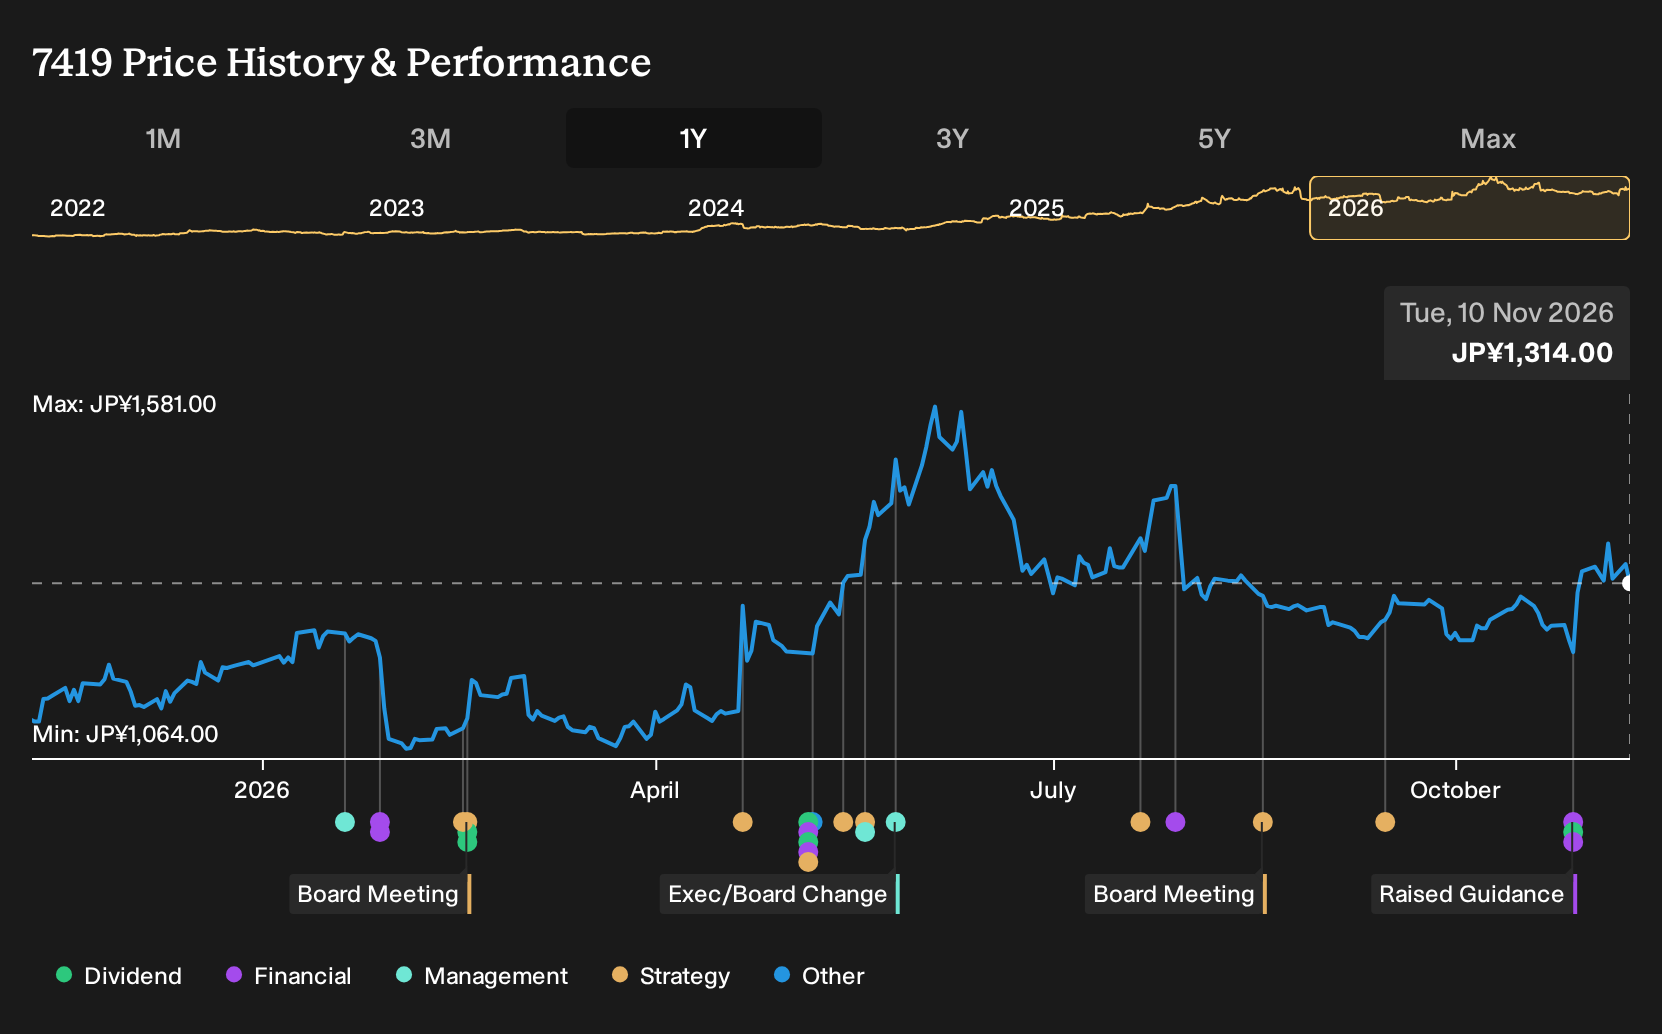
- Nojima reported half year results to September 30, 2026 with sales of ¥503,756 million and net income of ¥33,590 million, alongside a raised full year forecast and a ¥10.00 second quarter dividend payable on December 4, 2026.
- Stronger guidance linked to record net sales in seasonal home electronics, mobile carrier stores, product business, and overseas operations highlights how broad based demand is supporting Nojima's operating performance.
- The focus now is on how Nojima's upgraded full year guidance could reshape the investment narrative that investors use to judge the business.
Pressure-test Nojima's momentum against other retailers by scanning a curated 20 high quality undervalued stocks with solid cash flows and balance sheets that could also be pricing in stronger guidance.
What Is Nojima's Investment Narrative?
Nojima’s story hinges on whether you buy into a fairly simple idea. This is a retailer and services group that tries to turn foot traffic and device upgrades into steady earnings across several income streams, from home electronics to mobile carrier stores and overseas operations. The raised full year guidance and the Q2 2027 earnings call scheduled for October 30, 2026 keep the near term focus on execution quality, not just on headline growth.
The upgraded forecast and JPY 10.00 second quarter dividend point to management confidence in demand, pricing power, and cash generation. In the short term, the key catalysts are whether seasonal electronics, carrier shops, and overseas units can sustain this momentum without stretching working capital or capital expenditure. The main watchpoint is that part of Nojima’s profit profile relies on non cash earnings, so reported strength and underlying cash conversion may not always move in lockstep.
That said, set against all the upbeat guidance and dividend signals, there is a quieter issue in the background that could still...
There's only one way to know the right time to buy, sell or hold Nojima. Head to Simply Wall St's company report for the latest analysis of Nojima's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Nojima research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nojima. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nojima's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nojima?
If you want to pressure test what you think about Nojima against other opportunities, a broader sweep across the market can help you see where the risk and reward trade offs really look most attractive.
- For investors hunting for stability first, scan a curated 18 resilient stocks with low risk scores that screens for businesses with more resilient risk profiles and fewer unpleasant surprises.
- If you want balance sheet strength to do more of the heavy lifting, filter candidates using a list of solid balance sheet and fundamentals (23 results) that highlights companies with cleaner debt positions and solid fundamentals.
- When you are looking for less crowded situations, take a look at a 76 high quality undiscovered gems that surfaces higher quality companies the market may not be paying full attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com