


EN
Badger Infrastructure Solutions (TSX:BDGI) Shares Just Moved, What Is Driving Attention Now?
Badger Infrastructure Solutions (TSX:BDGI) just reported third quarter results that paired a 21% revenue jump with essentially flat year to date earnings, and then backed that up by affirming its quarterly dividend.
Badger Infrastructure Solutions has had a choppy run into these results, with the share price at CA$76.88 after a 2.86% one day gain. However, the 30 day share price return is down 15.10%, while the 3 year total shareholder return of 99.02% shows how strong the longer term ride has been. Recent updates on fleet expansion, capital spending plans and the dividend affirmation help explain why analysts remain engaged, even as the 7 day and 90 day share price returns are down 8.91% and 13.78%. The 1 year total shareholder return of 4.68% is now only modestly ahead of the year to date share price gain of 5.36%.
Spot emerging peers benefiting from similar utility and energy project tailwinds by scanning our hand picked list of 42 power grid technology and infrastructure stocks.The swing between a weaker 30 day return and a near doubling over three years puts Badger Infrastructure Solutions at an interesting crossroads. Are you looking at a reset in sentiment or a fair read on the business?
Most Popular Narrative: 32% Undervalued
On the analyst consensus Narrative on Simply Wall St, Badger Infrastructure Solutions screens as undervalued, with a fair value of CA$113.28 against the latest close at CA$76.88, which puts the spotlight on how the underlying business plan is expected to play out.
The accelerating buildout of critical infrastructure projects such as data centers, airports, light rail and power transmission continues to support demand for Badger Infrastructure Solutions’ non destructive excavation services. This can feed into revenue as contractors draw on hydrovac capacity for longer project backlogs.
Ongoing urbanization and the maintenance needs of aging underground utilities still support a long project pipeline for Badger Infrastructure Solutions. This can underpin recurring revenue and support earnings through municipal and utility contracts.
See why 29 investors see Badger Infrastructure Solutions as 32% undervalued.
Result: Fair Value of CA$113.28 (UNDERVALUED)
Still, the story around Badger Infrastructure Solutions can shift quickly if U.S. truck tariffs persist longer than planned or if fleet growth adds leverage without matching utilization.
Find out about the key risks to this Badger Infrastructure Solutions narrative.
Another View: Badger Infrastructure Solutions On Earnings Multiples
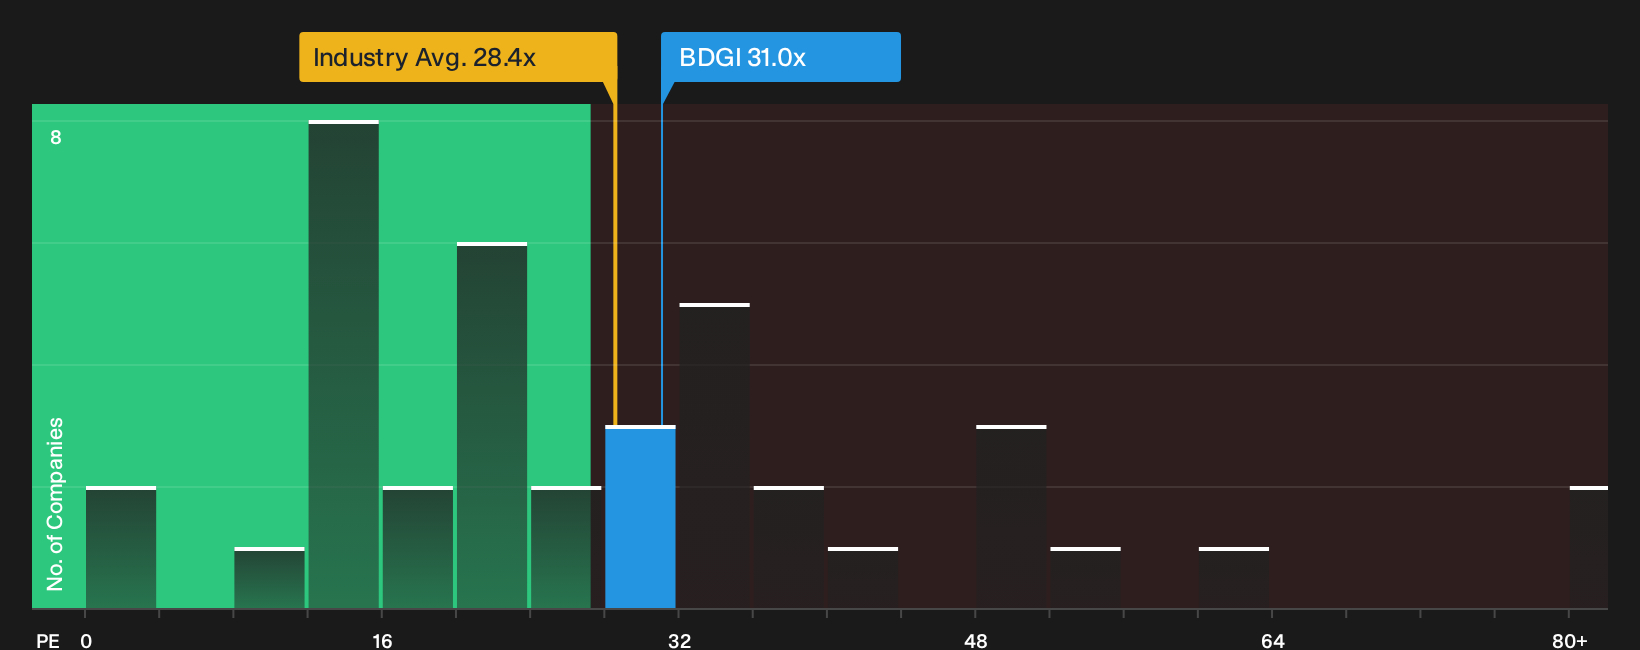
On a simple earnings lens, Badger Infrastructure Solutions looks less cheap. The shares trade on a P/E of 31x, compared with 26.6x for the wider North American Construction group and a fair ratio estimate of 24.9x, which suggests less room for error if growth or margins disappoint.
That kind of gap on P/E can signal investors are paying a premium for execution on the current plan rather than getting a clear bargain. It is therefore worth asking whether the story justifies that valuation stretch or if expectations have crept ahead of the fundamentals. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a genuine opportunity around Badger Infrastructure Solutions; either way, the best move is to test the numbers yourself and weigh the trade off between concerns and optimism. To frame that decision with more structure, start with its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Badger Infrastructure Solutions?
If Badger Infrastructure Solutions is already on your radar, do not stop there. Broaden your watchlist with a few focused idea lists that can surface opportunities you might otherwise miss.
- Target resilient compounding potential by reviewing a 3 dividend fortresses that can help you focus on income plus staying power.
- Hunt for mispriced quality and scan a 7 high quality undiscovered gems that can highlight companies the crowd is not paying attention to yet.
- Prioritize capital preservation first and check a 9 resilient stocks with low risk scores that can help you narrow in on steadier performers when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com