


EN
Don’t Chase the Arm Stock Dip Yet. What Patient Investors Should Wait for Before They Buy.
Arm Holdings (ARM) just did everything right on paper, and the stock still tanked. The stock fell more than 11% on Thursday right after the earnings report.
In its fiscal second-quarter report, Arm delivered revenue of $1.44 billion, up 27% year over year and above the $1.38 billion analysts were expecting. Adjusted earnings per share hit $0.52, up from $0.39 a year ago and ahead of the $0.47 consensus.
So, yes, Arm topped estimates on both revenue and EPS. Still, investors headed for the exit. That’s a puzzling reaction, but a closer look at the numbers explains it.
Why Arm Stock is Sinking
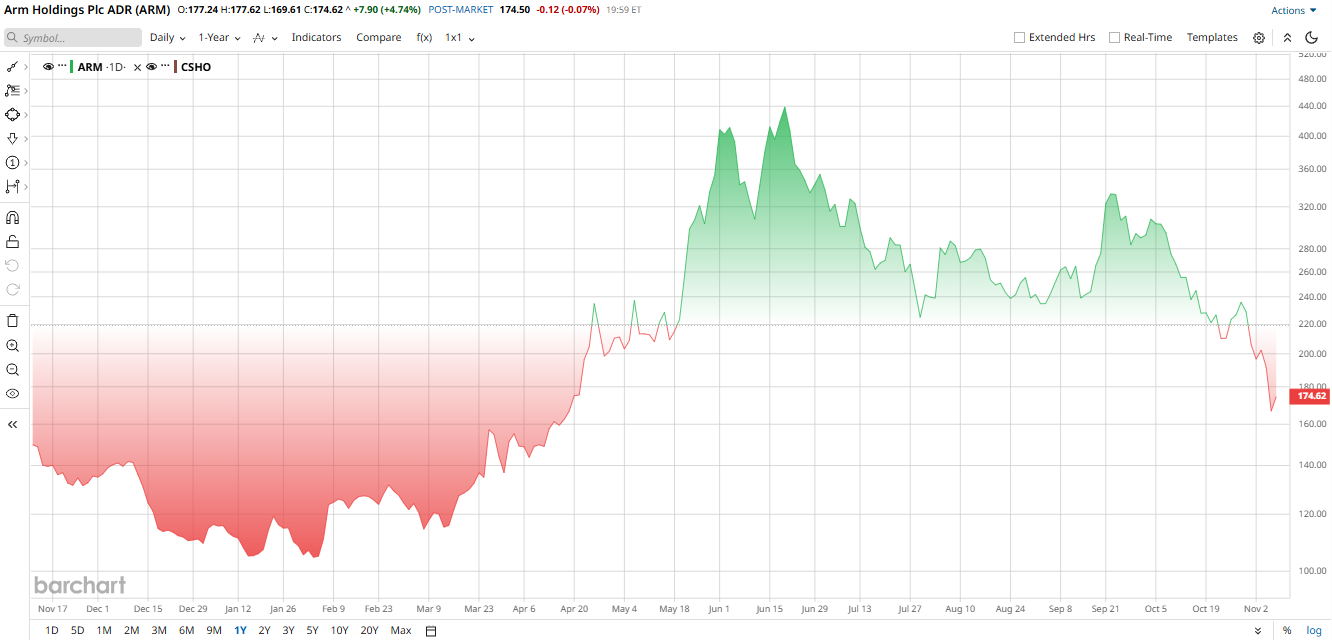
The selling momentum was not abated after just one poor session; ARM stock is down by over 42% in the last month, but is still up by nearly 60% for the year.
The stock reached a 52-week high of over $450 earlier this year, fueled by the soaring frenzy surrounding artificial intelligence, but has returned most of it. That indicates that the rally was a weak one.
Add to that a frosty atmosphere behind them. The demand for phones is being impacted by high pricing of memory, which has been under pressure in the broad chip industry. In addition, the royalties failed to take off. The increase in royalty revenue was 8% to $670 million, which was less than the estimated 13% increase Arm told investors in July.
Turning to valuation, Arm isn’t cheap, even after the drop. Its Price-to-Earnings (P/E) is 83x, far higher than the sector median of 21x, while its Price-to-Sales is 33x, compared to the sector median of 3.1x. These stretched ratios indicate ARM shares trade at a significant premium, making the stock very costly for new investors.
What’s Really Happening Under the Hood
The most important thing is that it was an authentic beat, but it wasn't from the right spot. The numbers for licenses, which pay for the rights to use equipment, increased 50% to $773 million, compared with only an 8% increase for royalties, the category that correlates with the number of chips sold.
Licensing is lumpy. Investors pay the stream of revenues called royalties. Last fiscal year, smartphones accounted for approximately 43% of the royalty revenue, while the actual revenue from royalties was relatively unchanged.
Guidance didn’t help either. Third-quarter Arm revenue is expected at $1.54 billion, while adjusted earnings per share (EPS) are forecast at $0.56, still just a hair below the midpoint of the $1.53 billion and $0.55 reported consensus.
Arm’s Bigger Plan Beyond Phones
The good news is that Arm is no longer just a licensor. Its first real chip, the Arm AGI CPU, is built for agentic AI, with Meta Platforms (META) as the lead customer and shipments starting in the fiscal fourth quarter.
Arm now expects up to $2 billion in cumulative AGI CPU revenue across fiscal 2027 and 2028, double its prior forecast. The long-term target is $15 billion a year by fiscal 2031.
Elsewhere, data center royalties doubled and now make up about a quarter of the total, while physical AI royalties grew 50% on auto strength. However, first-generation gross margins should be just 30% to 40%, and real volume doesn’t arrive until fiscal 2028.
Wall Street Can’t Agree on Arm Stock
There is a divide among analysts, and it is growing. Among the most vocal bears is Goldman Sachs, which still has a $160 target and a Sell rating. It argues that the price is slow to move and more often than not, that price is determined by licensing, not royalties or by using an AGI CPU.
More conservative groups have been Morgan Stanley, which maintained an Overweight rating on the stock but reduced its target price to $245 from $255. It noted that results were solid, with a 50% increase in licensing revenue to $773 million, as well as several AGI CPU purchase orders and a new SoftBank project.
Lee Simpson of Morgan Stanley held an Equal-Weight rating and a $212 target, noting execution concerns with scaling up production of CPUs. Susquehanna's Mehdi Hosseini maintained a Positive rating on Arm and kept the $320 target unchanged, topping their list with Arm's aim to ramp up to $2 billion of AGI CPU sales by fiscal 2028.
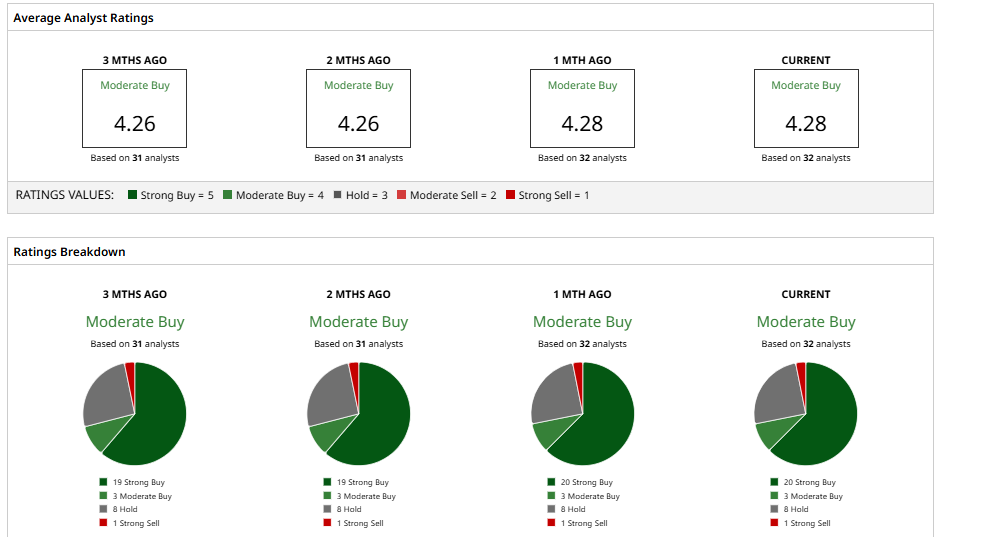
The 32 analysts have a consensus "Moderate Buy," and the 12-month average price target is $270, which suggests the stock could climb up to 74% from here. We have targets from $130 to $480, so no one agrees on what Arm is worth.
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.