


EN
Are Wall Street Analysts Predicting Mastercard Stock Will Climb or Sink?
Mastercard Incorporated (MA), headquartered in Purchase, New York, provides transaction processing and other payment-related products and services. Valued at $571.3 billion by market cap, the company offers payment processing services for credit and debit cards, electronic cash, automated teller machines, and travelers checks.
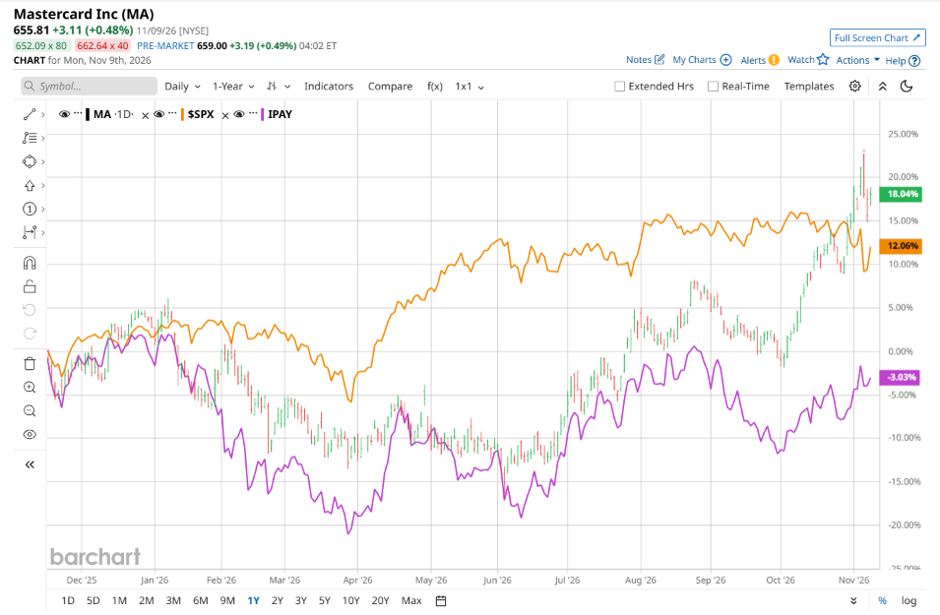
Shares of this payments giant have outperformed the broader market over the past year. MA has gained 18.8% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. In 2026, MA stock is up 14.9%, surpassing the SPX’s 10.3% rise on a YTD basis.
Zooming in further, MA’s outperformance is also apparent compared to the Amplify Digital Payments ETF (IPAY). The exchange-traded fund has declined about 3.2% over the past year. Moreover, MA’s double-digit returns on a YTD basis outshine the ETF’s 2.3% dip over the same time frame.
Mastercard strong performance was driven by a 20% expansion in merchant acceptance locations through innovations like Pay Local and Tap on Phone, accelerated affluent consumer spending, and the rollout of Essential Debit to bring unbanked adults into the digital ecosystem. Value-added services grew 19% year over year behind a network-linked flywheel effect, while major international wins in Germany, China, India, and the Nordics helped offset intra-Europe cross-border headwinds. Looking ahead, management maintains a positive growth outlook, targeting high-single to low-double-digit revenue growth while strategically investing in emerging areas like agentic commerce and stablecoins.
On Oct. 29, MA shares closed up more than 4% after reporting its Q3 results. Its adjusted EPS of $5.31 exceeded Wall Street expectations of $5.14. The company’s revenue was $9.8 billion, topping Wall Street forecasts of $9.6 billion.
For the current fiscal year, ending in December, analysts expect MA’s EPS to grow 17.6% to $20 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 42 analysts covering MA stock, the consensus is a “Strong Buy.” That’s based on 33 “Strong Buy” ratings, four “Moderate Buys,” and five “Holds.”
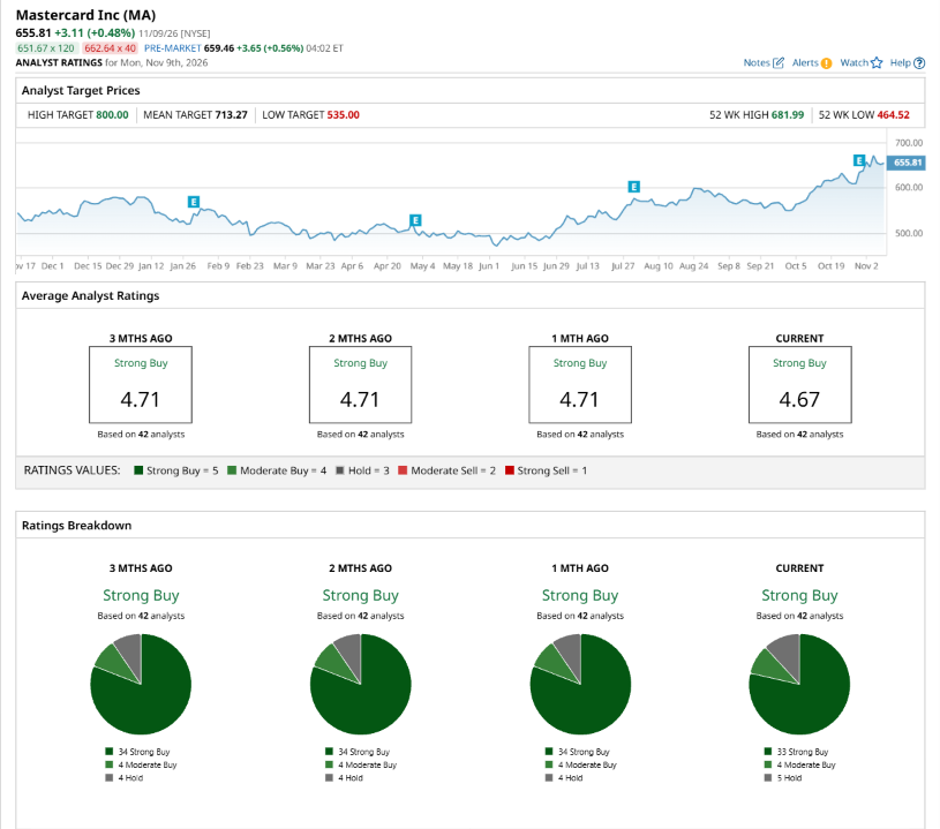
This configuration is less bullish than a month ago, with 34 analysts suggesting a “Strong Buy.”
On Nov. 5, Freedom Broker downgraded MA to a “Hold” rating with a price target of $725, implying a potential upside of 10.6% from current levels.
The mean price target of $713.27 represents an 8.8% premium to MA’s current price levels. The Street-high price target of $800 suggests an upside potential of 22%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.